
Trading Insights
Friday Morning Rebel Brief: A Mixed Bag of Earnings
While some of the hardest hit names in the tech sector are getting their reprieve from recent selling, the story is becoming a mixed bag for brick-and-mortar retailers. While Ross Stores and Deere & Company have taken a hit this morning, retailers like Deckers Outdoor and Foot Locker have become the latest names to buck […]

While some of the hardest hit names in the tech sector are getting their reprieve from recent selling, the story is becoming a mixed bag for brick-and-mortar retailers.
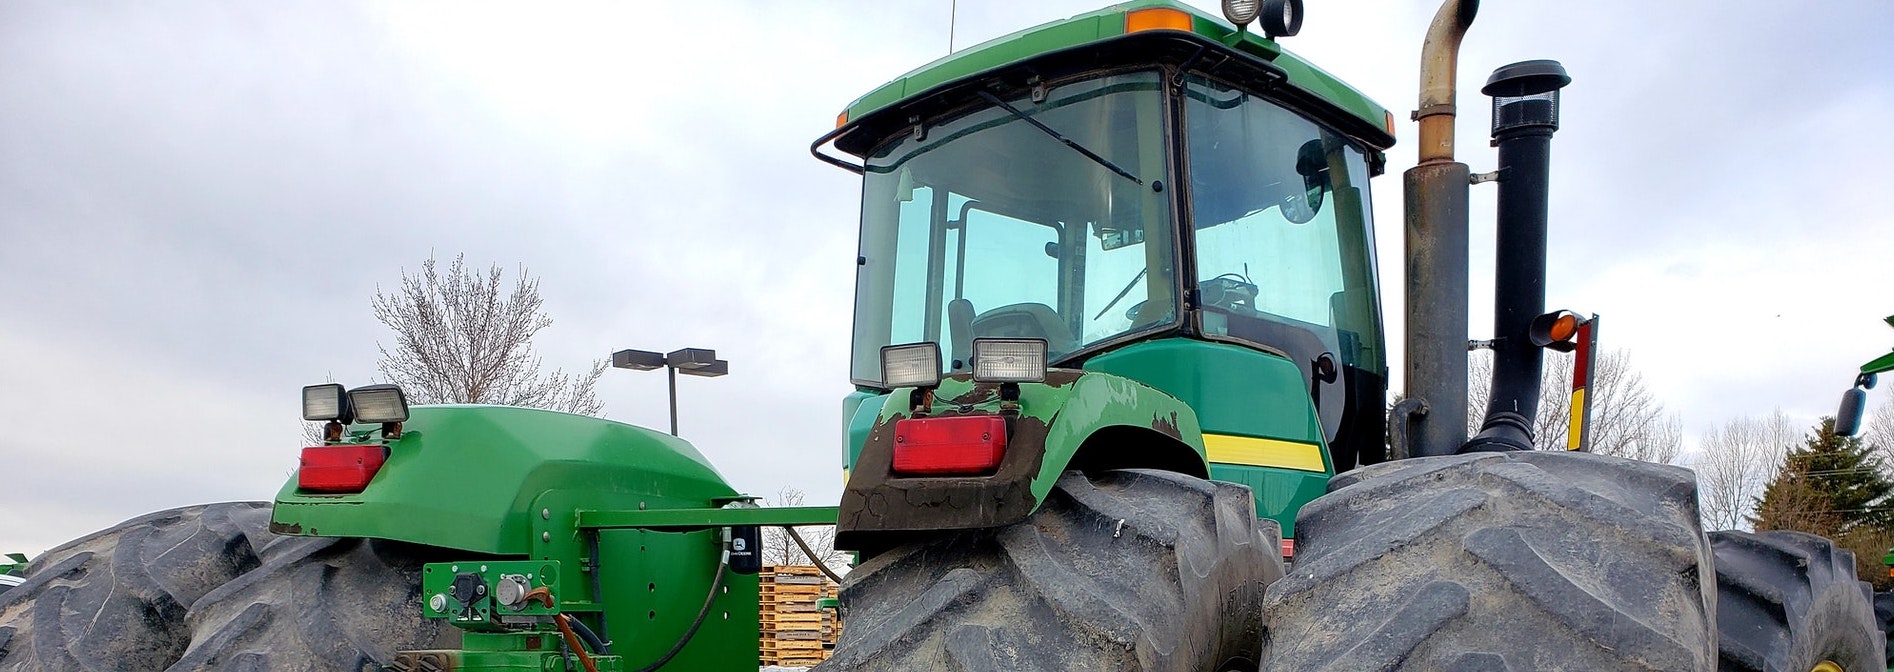
While Ross Stores and Deere & Company have taken a hit this morning, retailers like Deckers Outdoor and Foot Locker have become the latest names to buck the trend. Despite the assorted nature of earnings this morning, the major indices are getting a much-needed reprieve from the recent selling. Let’s dive into how those earnings went.
Ross Stores Inc. ($ROST) Becomes the Next Victim of Inflation
Ross missed EPS by -2.94% ($0.97 vs $1.00 expected) and missed revenue by -4.48% ($4.33B vs $4.54B expected). Ross is currently down more than 23% in premarket trading.
Ross stock was interestingly one that wasn’t down heavily this Wednesday alongside Target, Dollar Tree, Dollar General and other department stores. But they couldn’t escape the retail curse today. Ross cut its outlook for both profit and sales, experiencing many of the same inflationary pressures that many other retailers have mentioned.
Deere & Company ($DE) Slips 6% Despite Positive Earnings
Deere & Company beat EPS by 19.9% ($6.81 vs $6.65 expected) and beat revenue by 10.9% ($13.37B vs $13.10B expected). The heavy machinery stock is currently down more than 6% in premarket trading.
Not only did the company report positive earnings, the agricultural titan raised its full-year profit outlook. Still this wasn’t enough to keep the stock from slipping into negative territory.
Deckers Outdoors ($DECK) Defies the Retail Trend
Deckers Outdoors beat EPS by 90% ($2.51 vs $1.32 expected) and beat revenue by 15% ($736.01M vs 639.81M expected). The footwear company is currently up more than 15% in the premarket.
Deckers Outdoor showed the bright side of retail Friday morning, with a robust top and bottom line beat and positive full-year guidance. And they weren’t the only footwear company to defy the odds and post better-than-expected earnings this morning…
Foot Locker ($FL) Stays a Step of Expectations
Foot Locker beat EPS by 3.2% ($1.60 vs $1.55 expected) but missed revenue by -1.6% ($2.18B vs 2.21B expected). Foot Locker is currently up more than 3% in premarket trading.
But wait, a mixed quarter? A revenue miss? Why is the stock trading higher? It all comes down to the earnings commentary, and CFO Andrew Page had a bright outlook. “We now expect to achieve the upper end of our revenue and earnings guidance for the full year.”
Palo Alto Networks ($PANW) Sets a Positive Trend for “High-Flying Tech”
Palo Alto beat EPS by 6.6% ($1.79 vs $1.68 expected) and beat revenue by 2.2% ($1.39B vs $1.36B expected). The stock is currently higher by more than 11% in the premarket.
The cloud-company grew its revenue 29% year-over-year, on top 30% in the prior quarter. Unlike many other companies, the conflict between Ukraine and Russia has not harmed Palo Alto Networks, which provides a suite of cybersecurity software. According to the CEO, Palo has actually seen increased interest in cyber-protection from businesses and even government agencies. In short: unlike many, inflation did not hurt Palo Alto’s story.
The Bottom Line
For anyone who was listening to the common stock market rhetoric over the past year, this is a really interesting development. SAAS stocks with dubious PE ratios like Palo Alto Networks were really looked down upon as potential victims of the upcoming rate hikes.
Instead, staples like Costco and Walmart were preferred due to their staying power, low relative P/E ratios, and consistent ability to turn a profit. If you’ve been paying attention this week, you know how silly that sounds in hindsight.
The lesson: sometimes the loudest and most well-respected voices in the market get it wrong. Think for yourself, do your own research, and stay true to your stock market convictions.