
Announcement
MARKET OUTLOOK 8-9: NEW HIGHS, INFLATION REPORTS, FX & METALS
Good Afternoon REBELS!
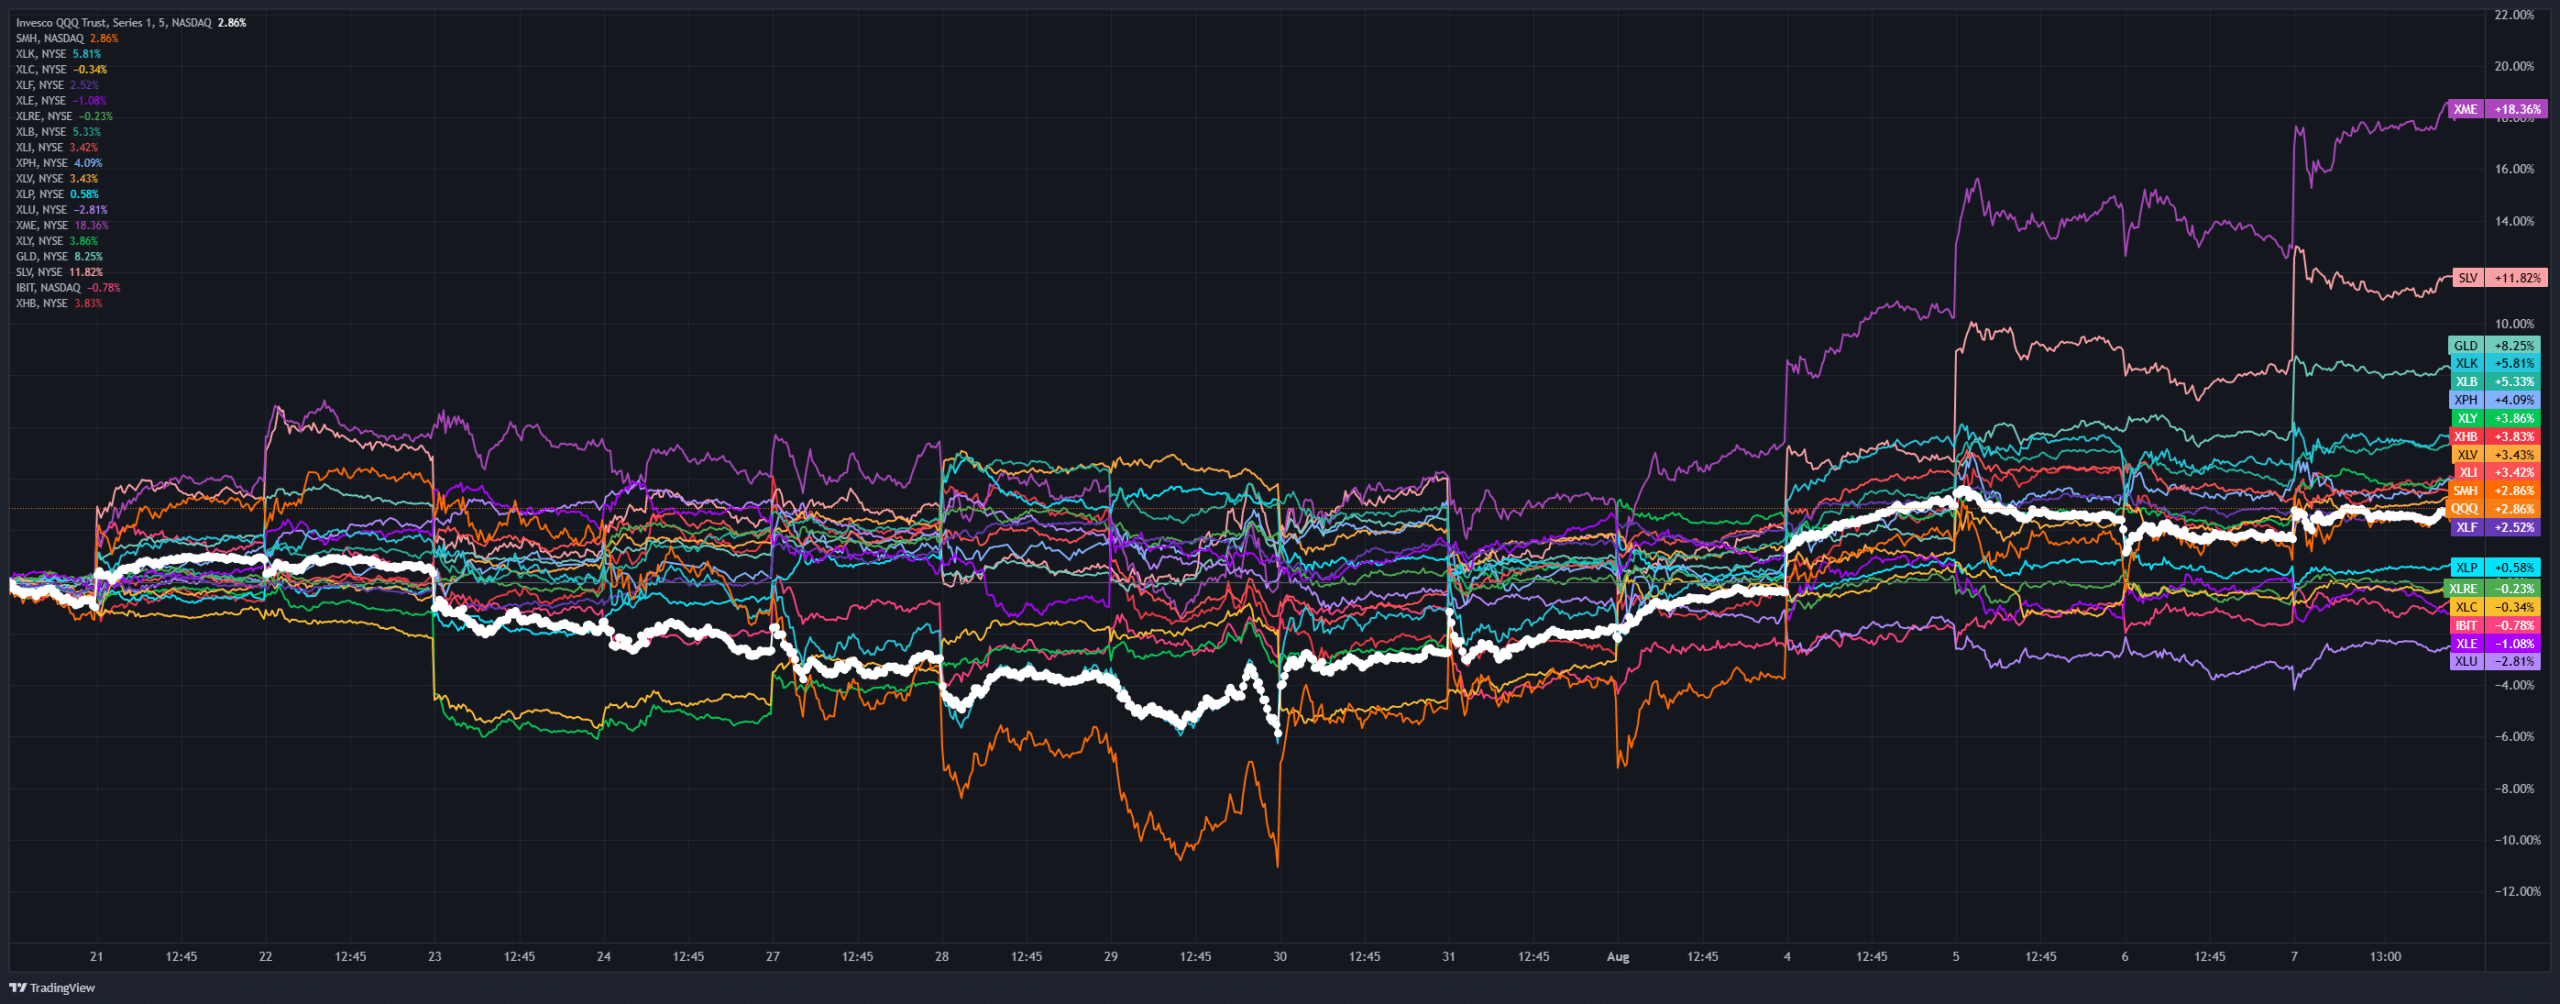
Metals and Miners have outpaced the recovery in technology from the Leo low. Over the last 3 weeks, metals are up over 18%. In the graph below, we can see that XLK +5.8% beat out the rest of the broad market that was in general recovery with an awesome bounce. This was assisted by new money from the new month! As always, a top down approach takes a little work to analyze the stocks inside these ETFs to see if trends are sustainable. There really wasn’t a sector that was sold into. Maybe utilities and energy with what was going on in Iran, but nothing worth exploring from a price movement perspective.
Note: Click on Charts to see a larger view!
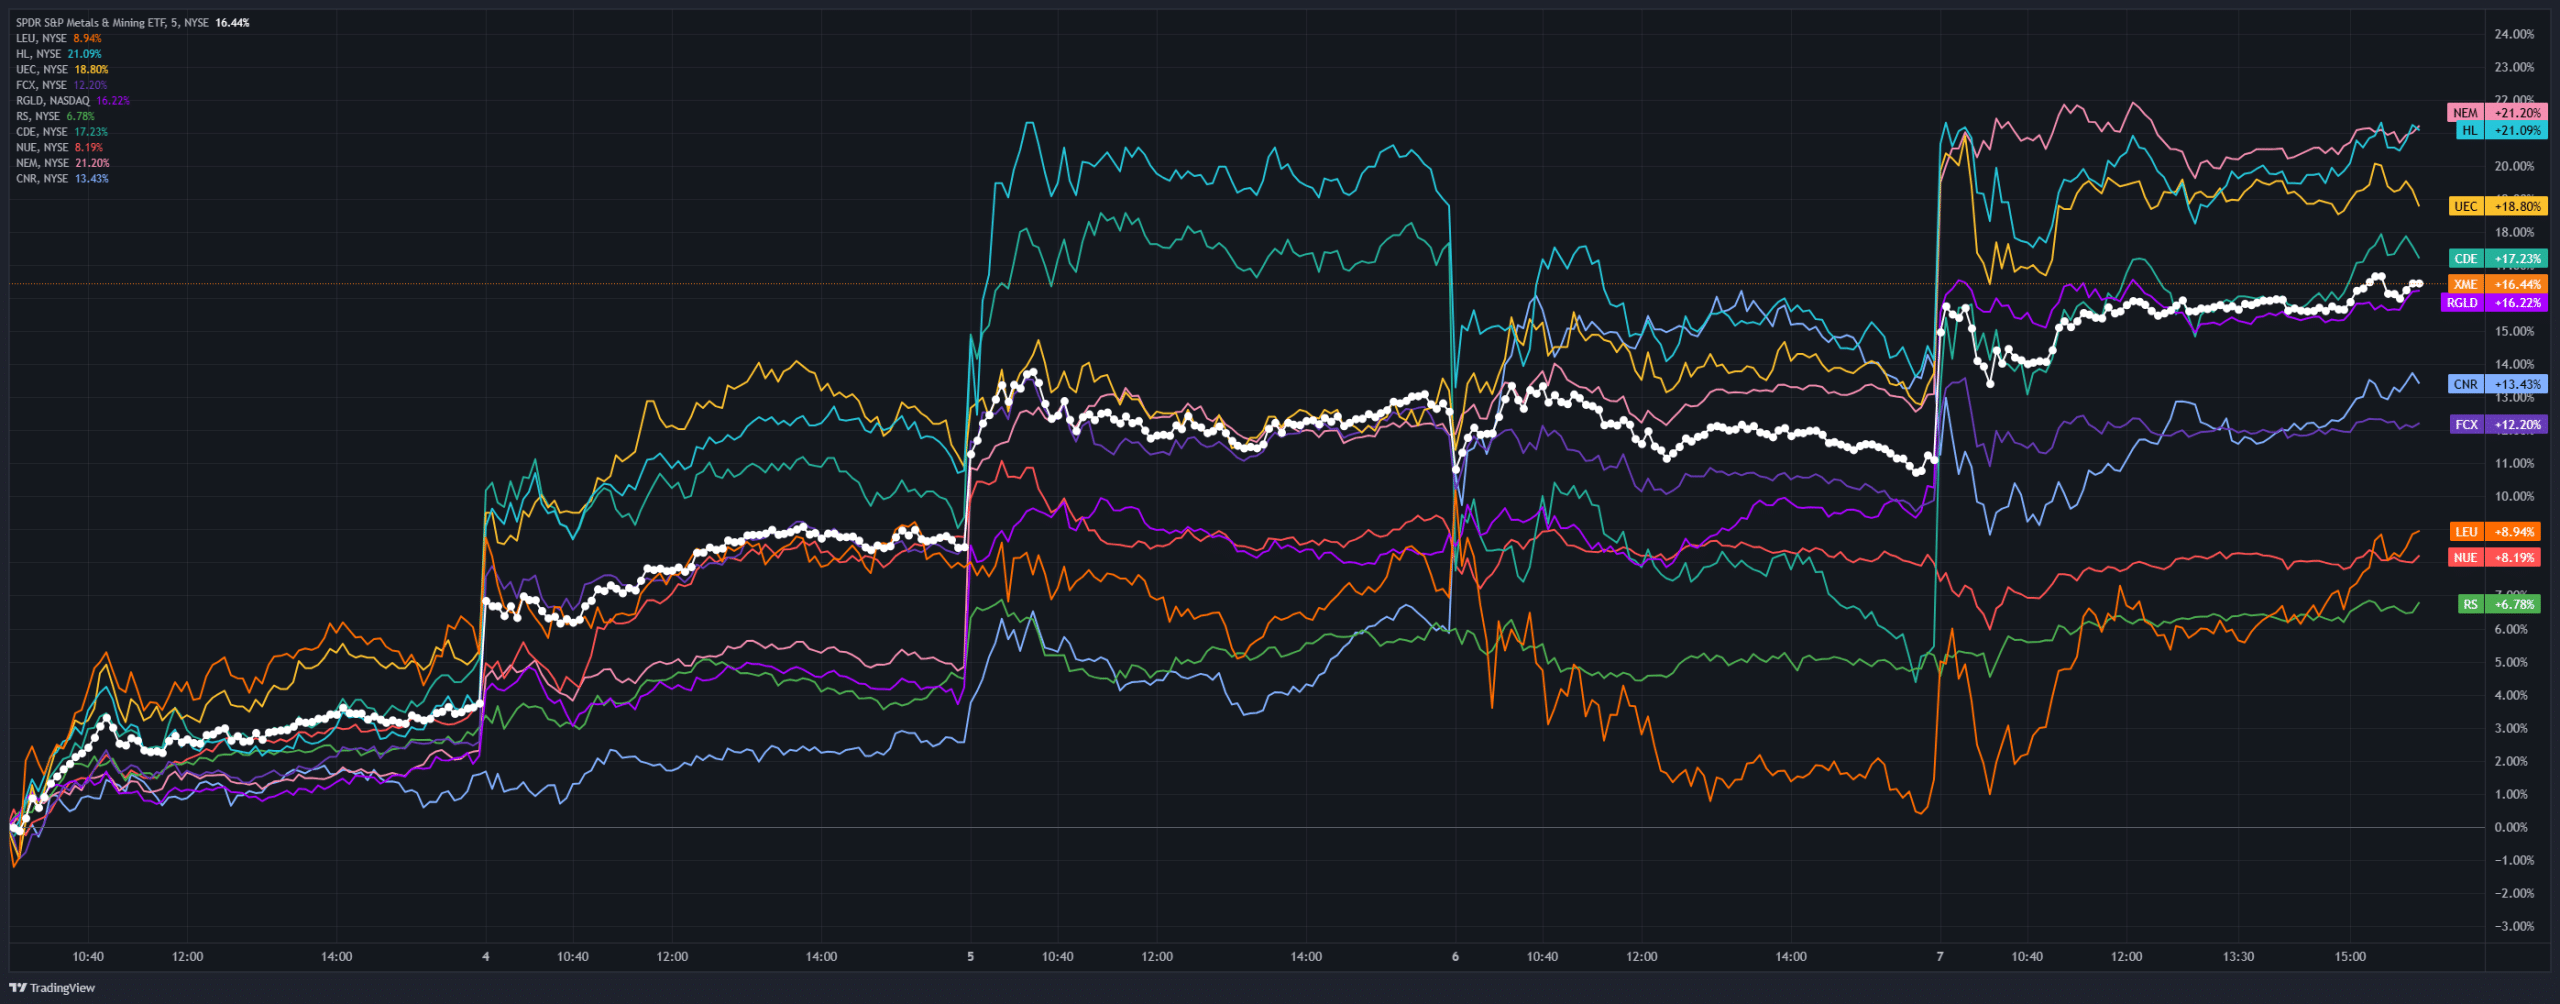
XME
This ETF holds 82% in metals and mining and 18% in energy( just 6 stocks). All 6 of the energy names were up on the week. Their outlook looks positive with bullish seasonality on every name. The metals found a bid early and this may have more to do with nervousness in the FX markets around currency manipulation from Japan & US. All of the miners were positive and some did better than others based on their primary metals. Some of the bigger names have reached short term overbought, but historically, when these trends finally turn and move they tend to stay in that direction.
GLD
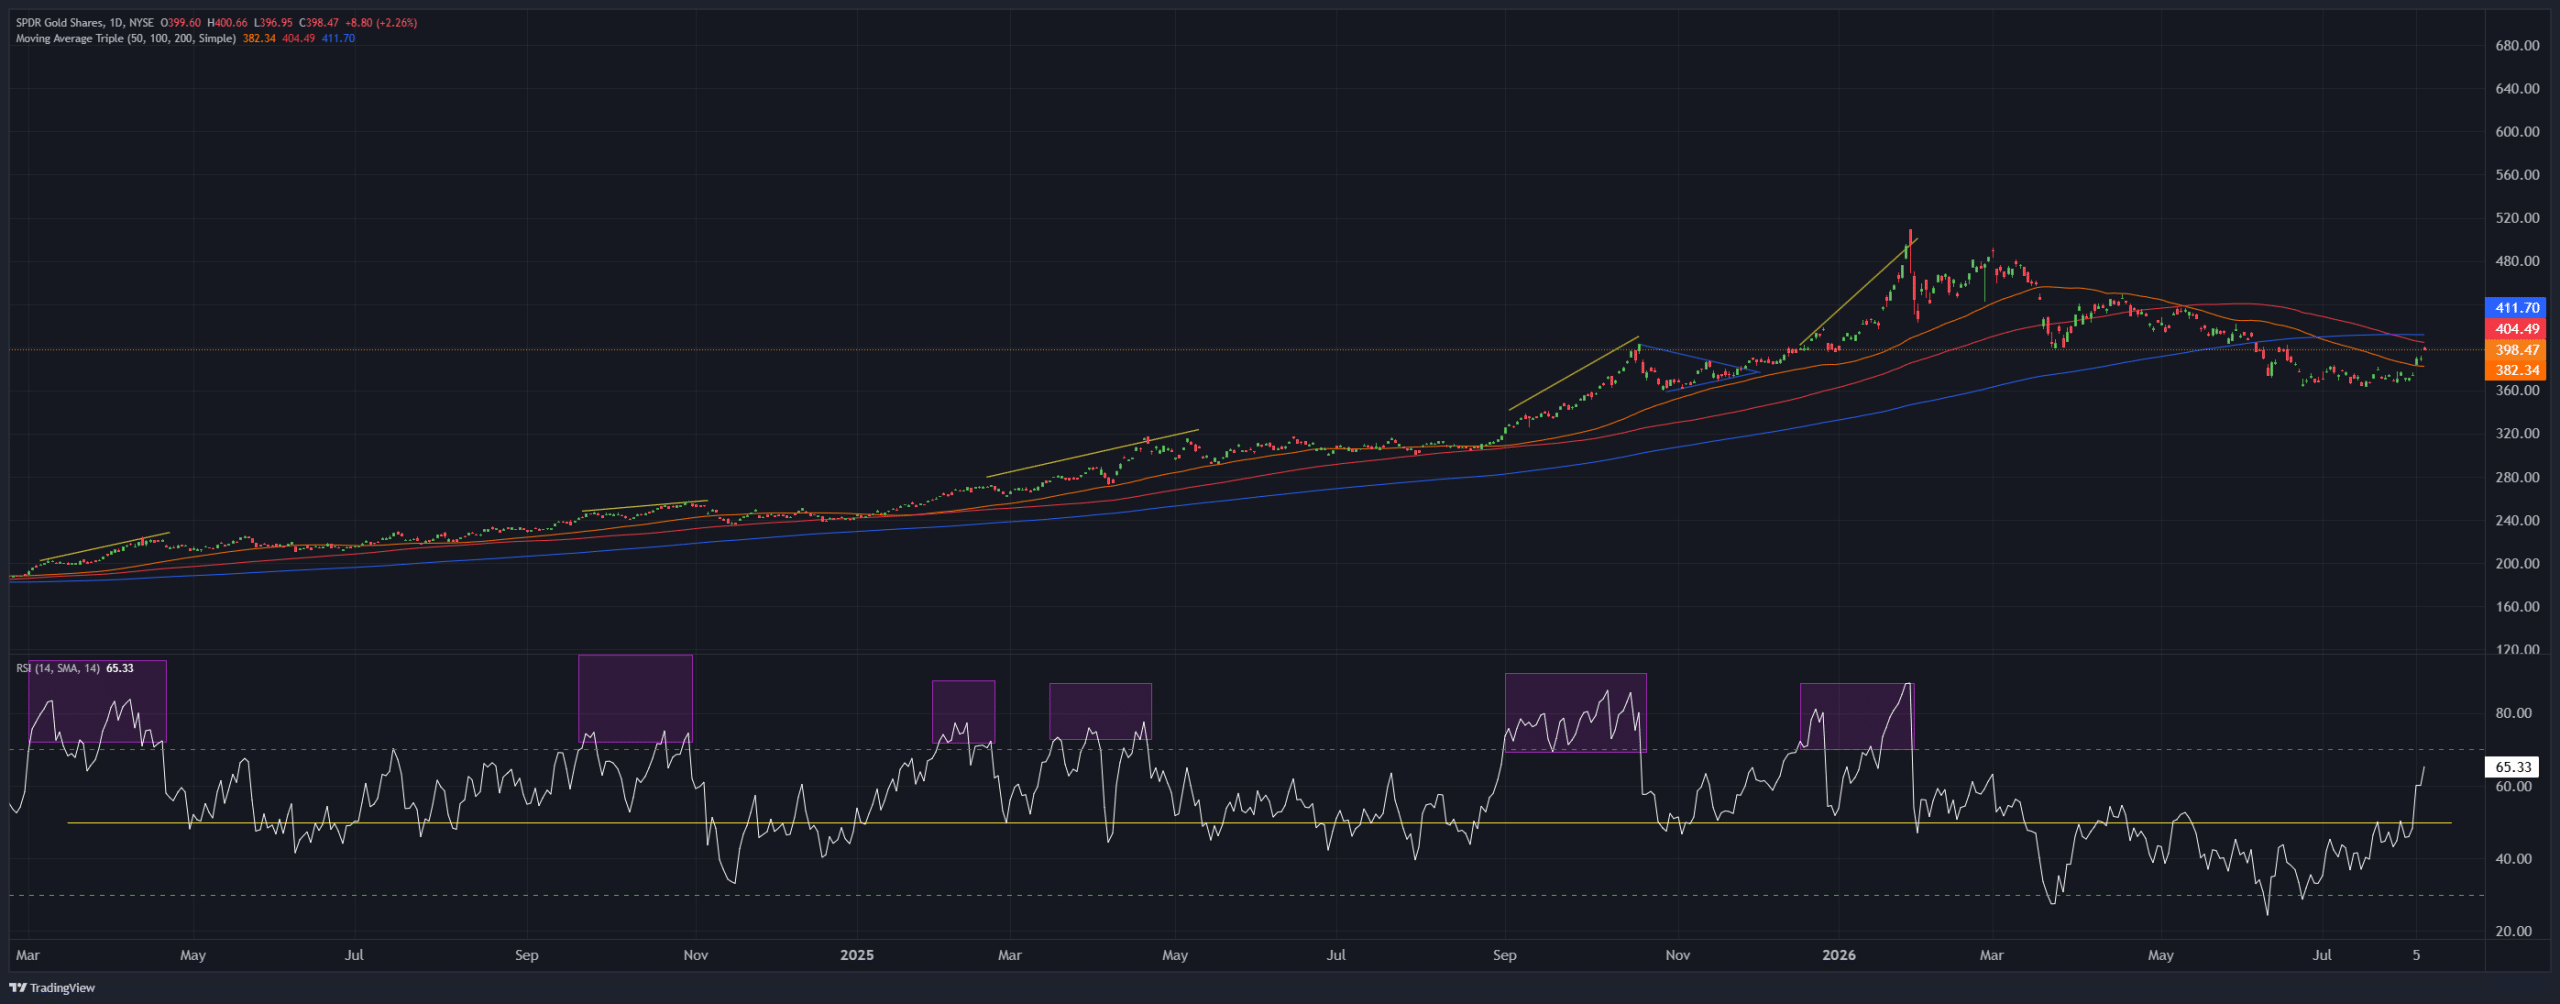
A little trend analysis after GLD becomes overbought. We can see the last 6 times that gold can continue to push higher even with some modest pullbacks in the RSI to the 50 line. The ETF is not overbought yet, but some of the individual names are so it may be time to get in a roll!
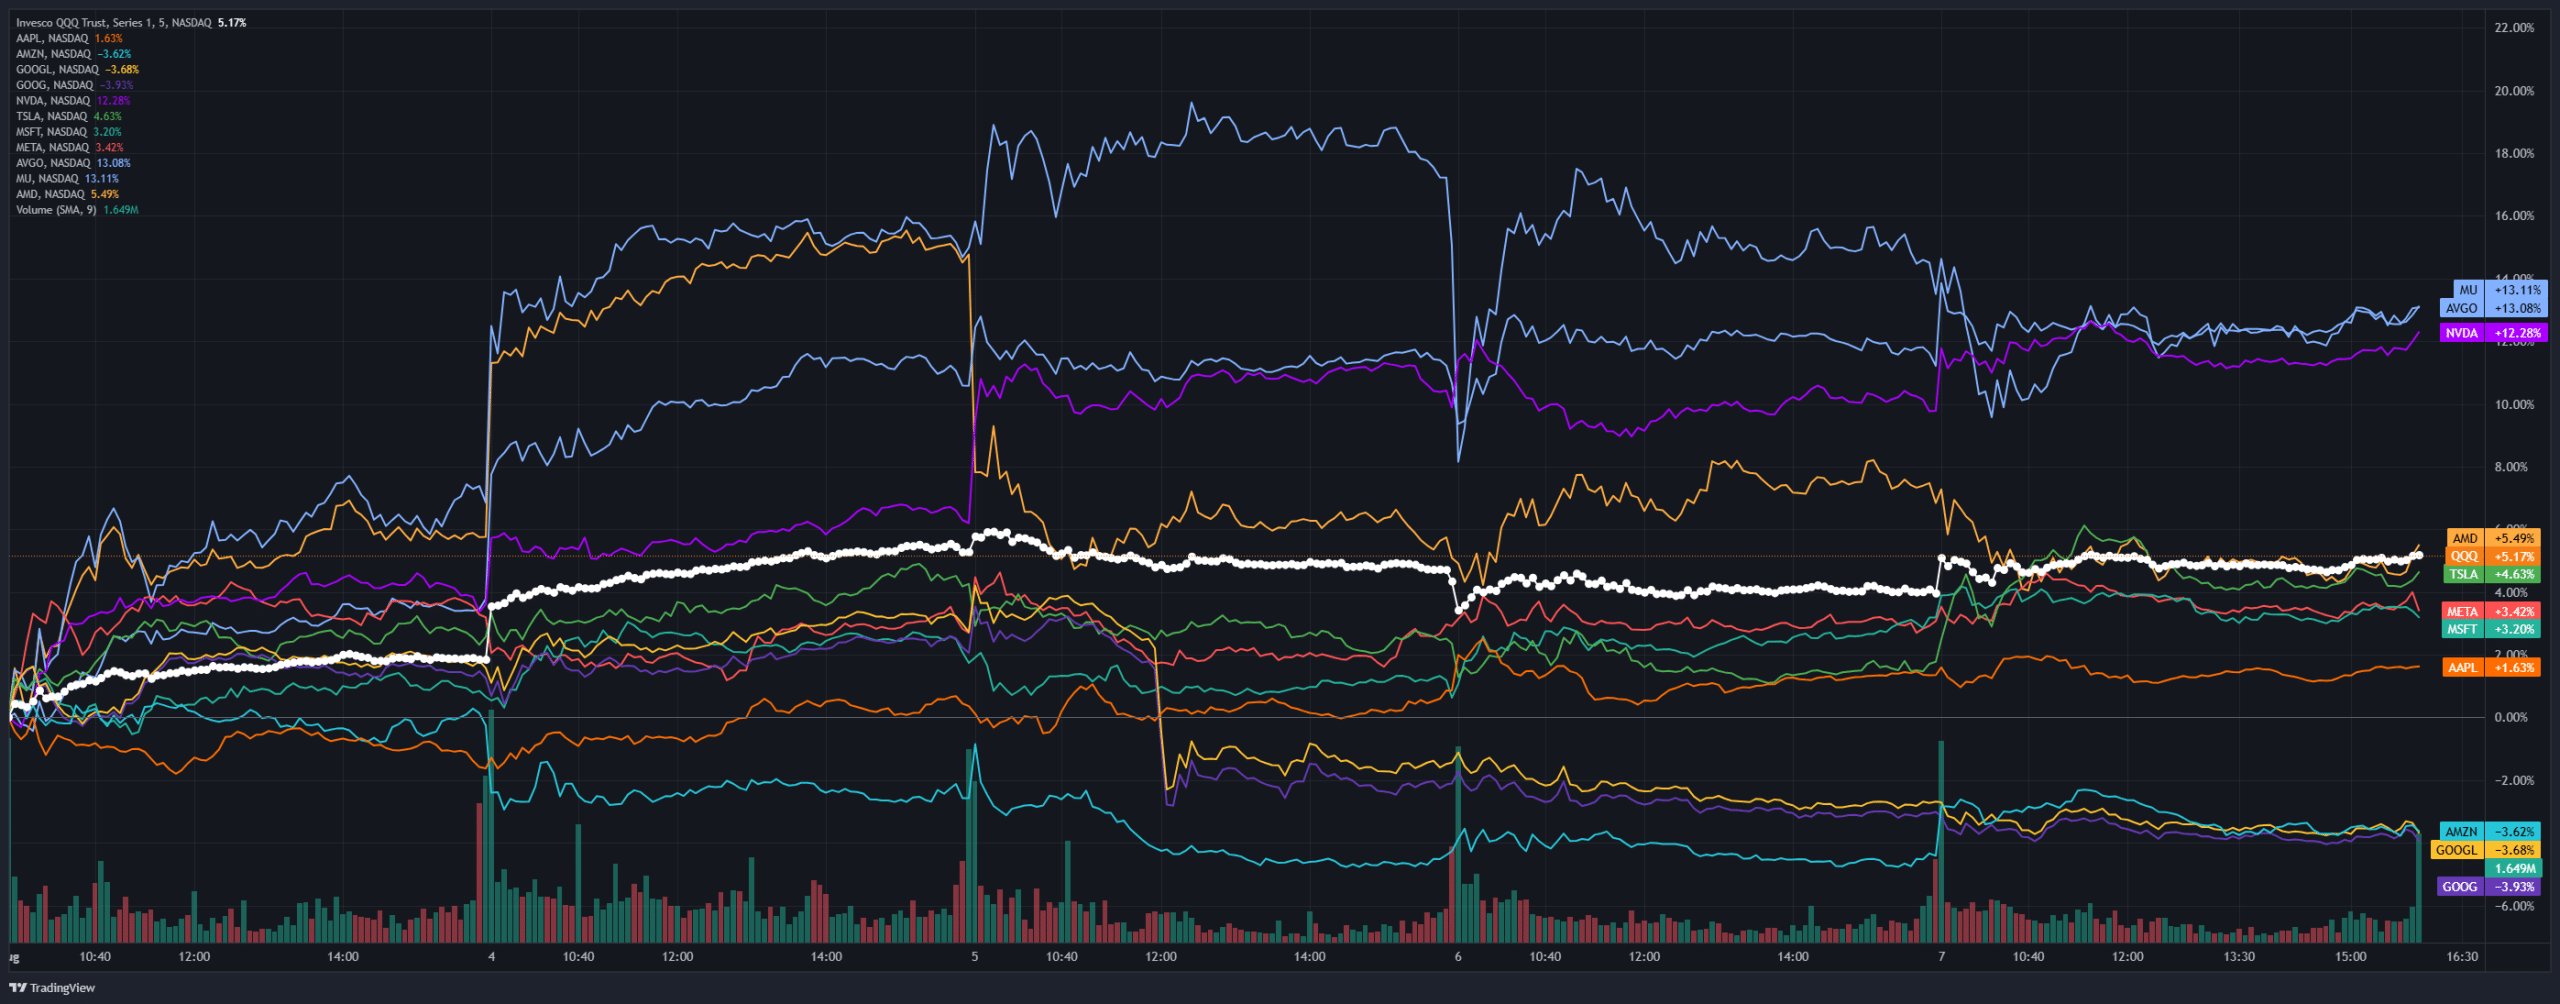
QQQ Top 10
We had a nice follow through in the market on Monday and Tuesday in tech. On Wednesday, the QQQ gapped higher was closed lower only to have a big gap down on Thursday that was bought. We were not able to retake the highs in the QQQ on the week while SPY, DIA, IWM all made new all time highs on the week. QQQ, SMH, XLK, XLC are all still lagging the broader market. This suggests that breadth has picked up. This also provides an incredible catalyst if the market starts to push the SMH back through the 50 sma. It is still 90 points off of its high. The opposite should also be taken into consideration. Tech led the market up and if we continue to see weakness, how much further can the market go if tech fails to rally or even worse moves lower.
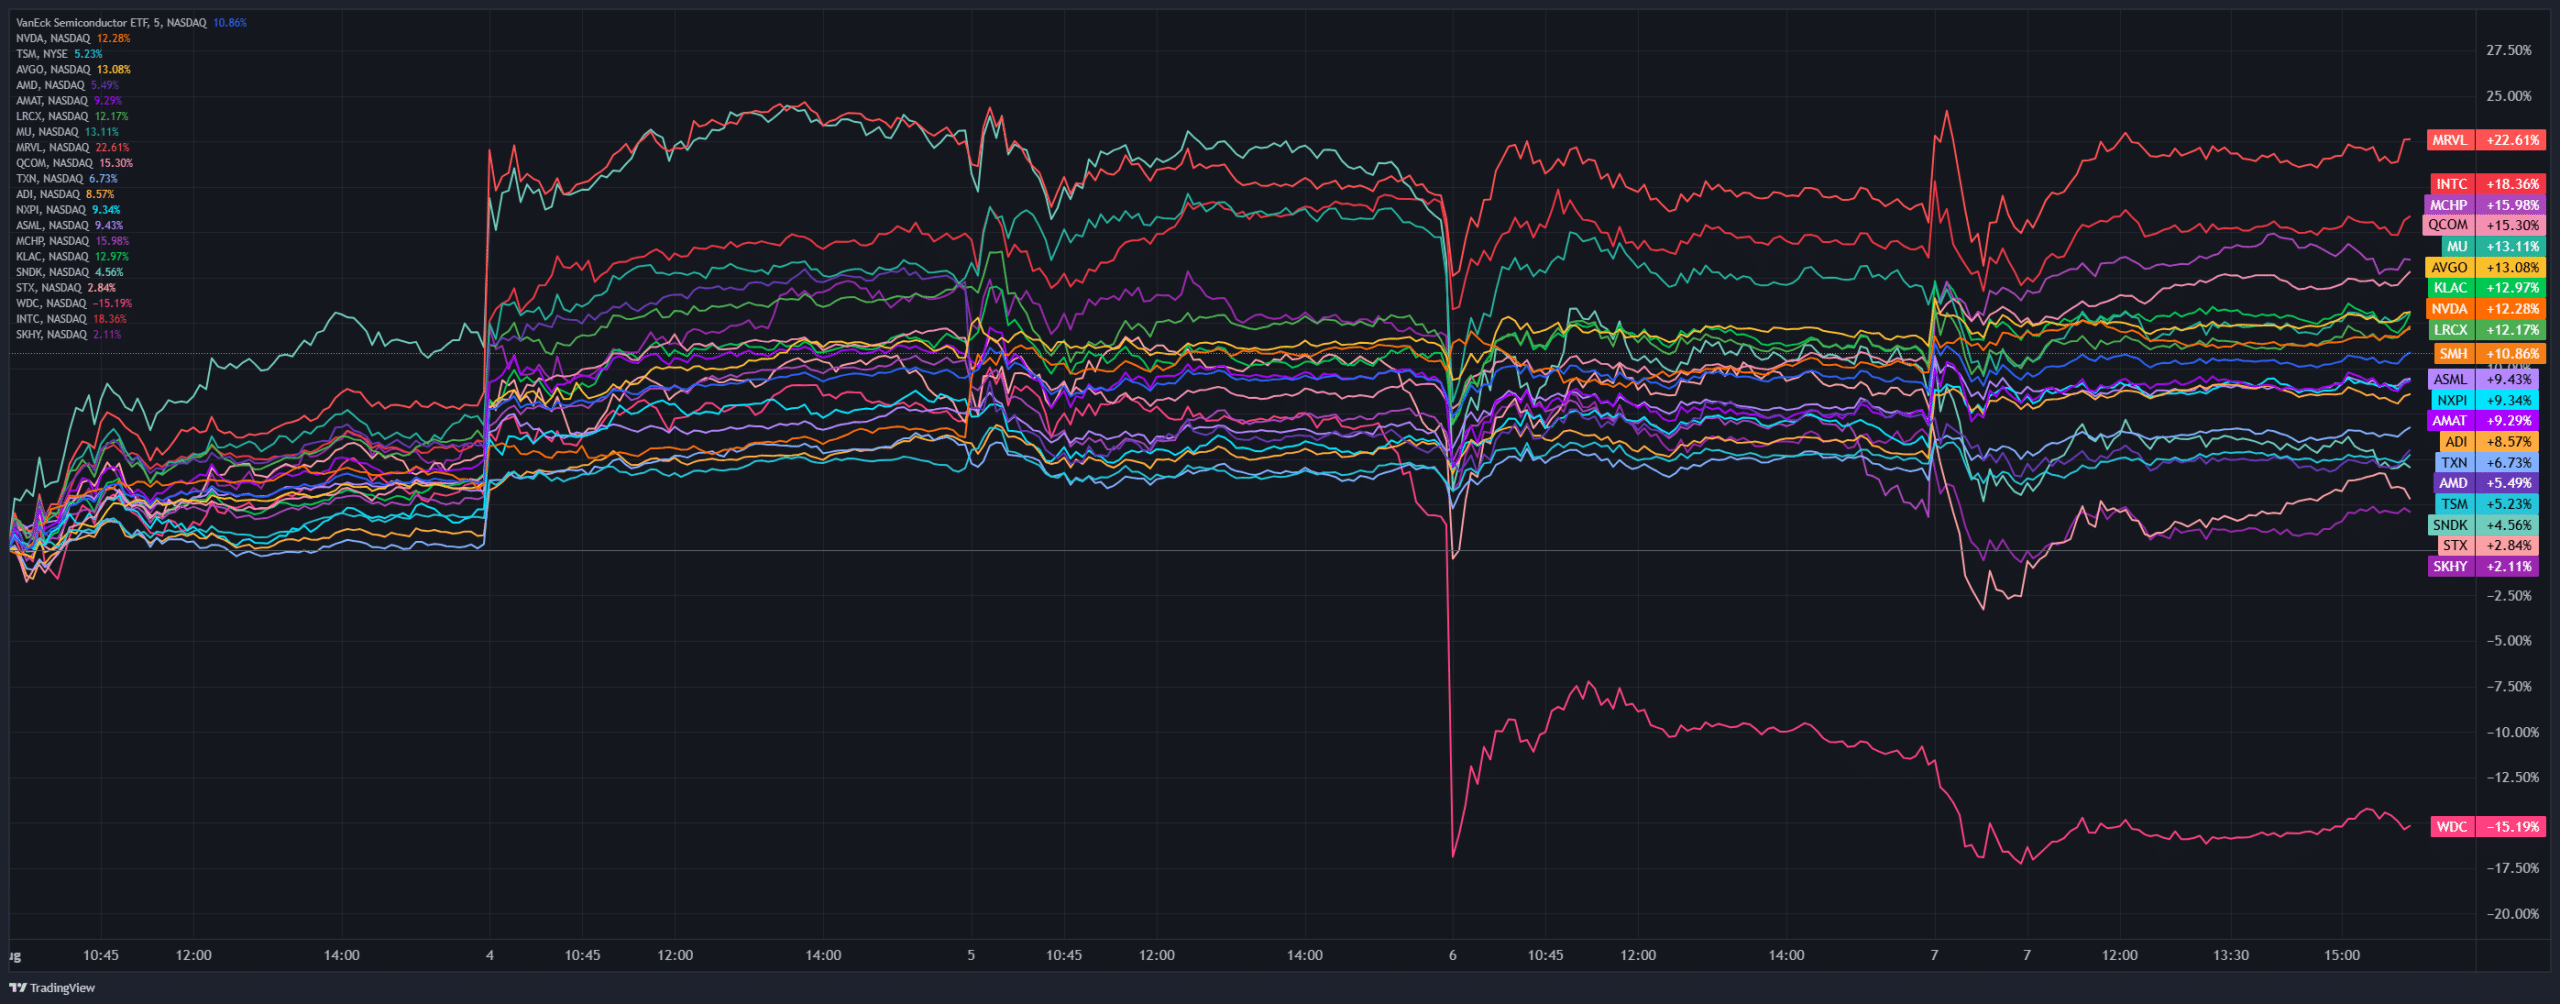
SEMICONDUCTORS
The first chart is of the prior week to see what moved within the sector. It does not include all of the names, just the top 20 in the SMH. The standouts are MRVL at the top and WDC at the bottom from earnings!
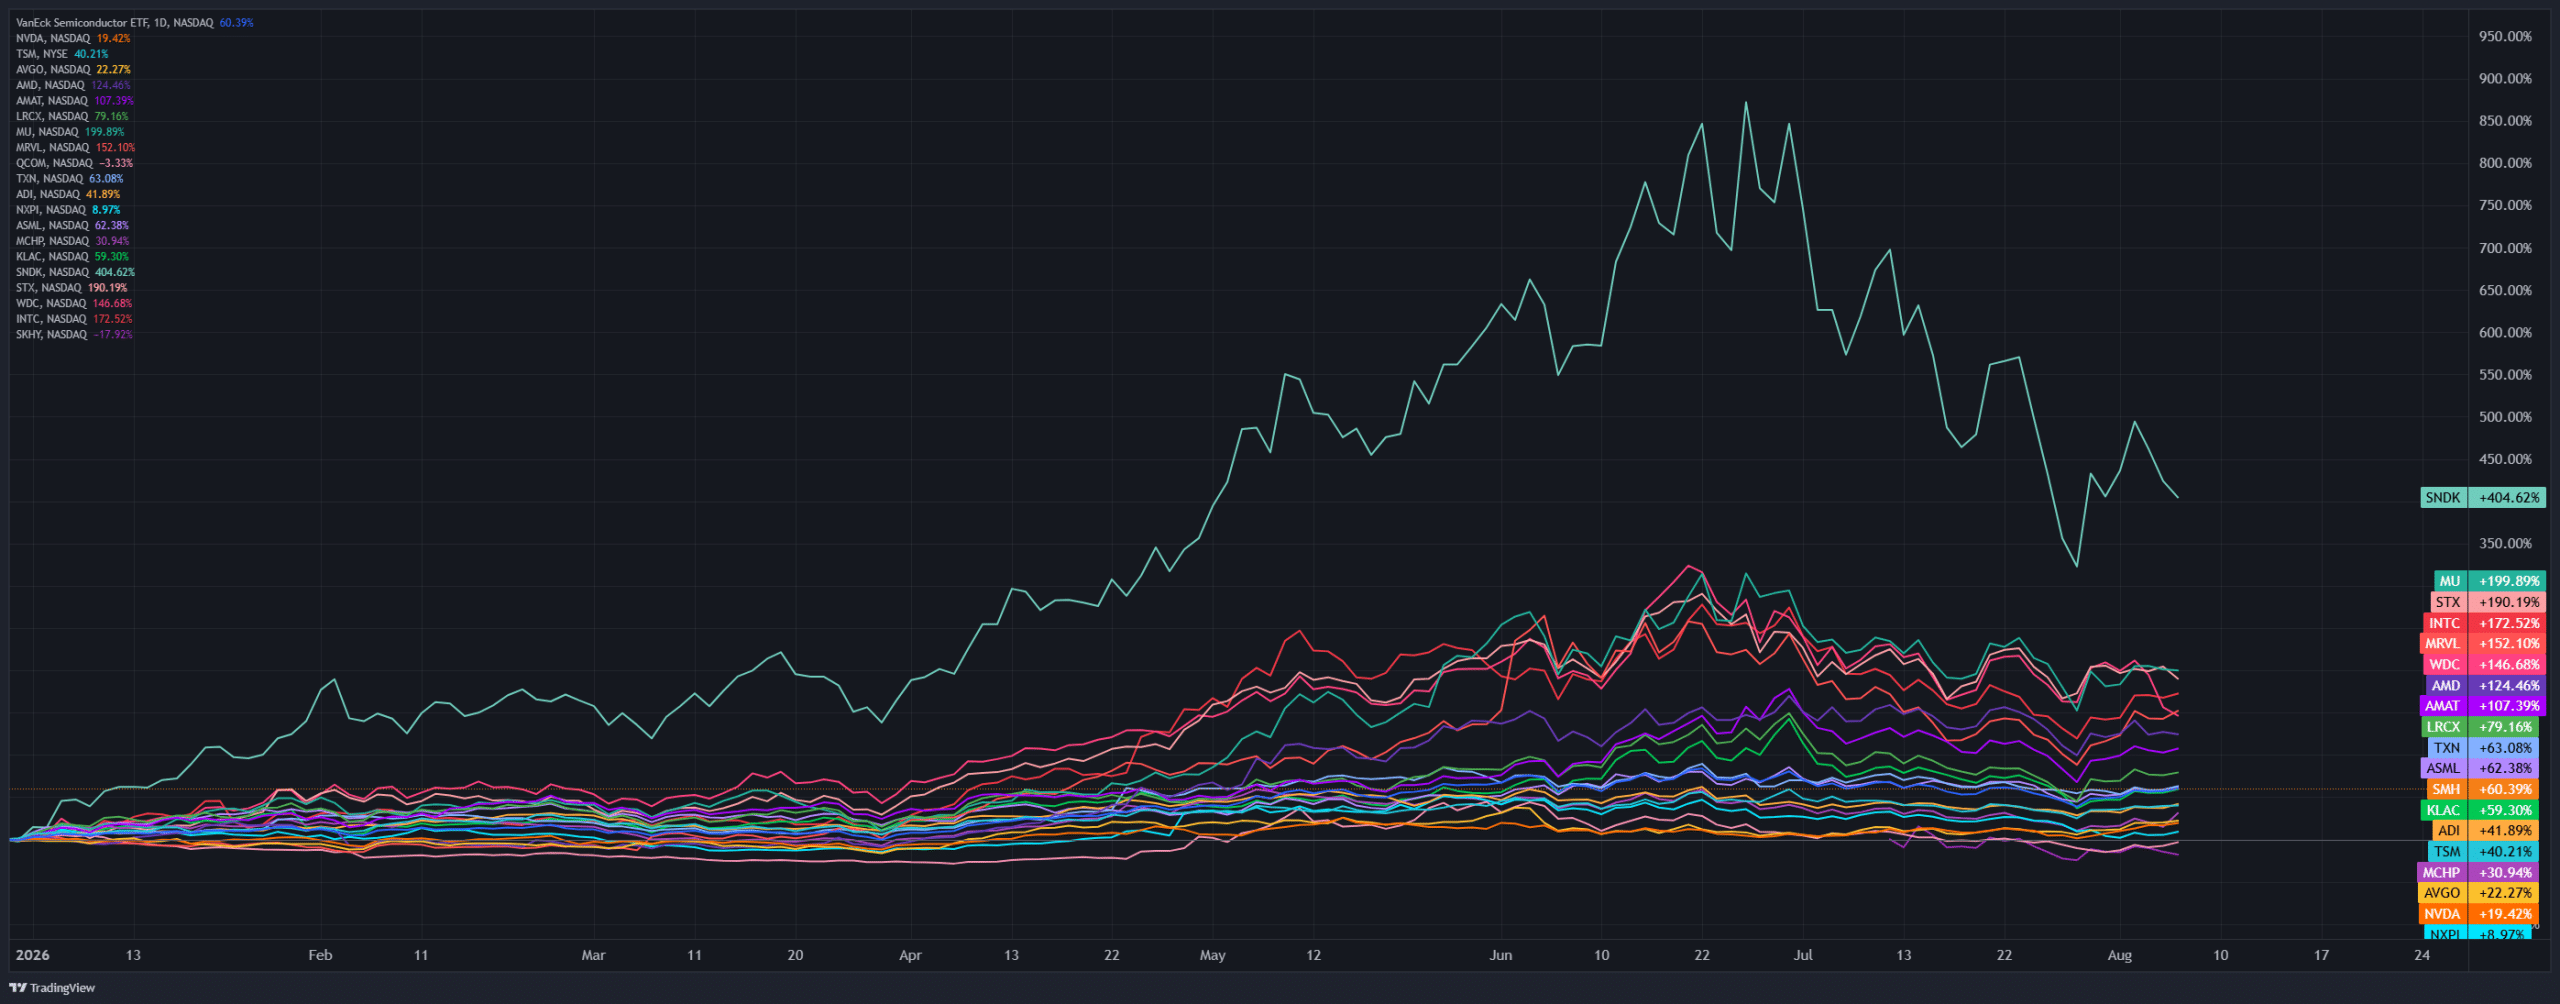
A year to date chart paints a crazy picture. Memory names helped drive SMH higher with SNDK still up roughly 400% on the year and only a couple names like QCOM and SKHY down small on the year. Now that the deleveraging has wiped out South Korea investors and Leo’s Situational Awareness Fund, can the memory names have the same type of speculative capital needed to push them back to highs? Demand for memory has not stopped and supply has not increased in any way yet to make a difference. AAPL looking at CMXT memory because it is cheaper, so we could see AAPL make a deal there if the current administration allows it. The next area investors have been pushing is photonics. This sub-sector aims to replace copper wire with high-speed optical connections.
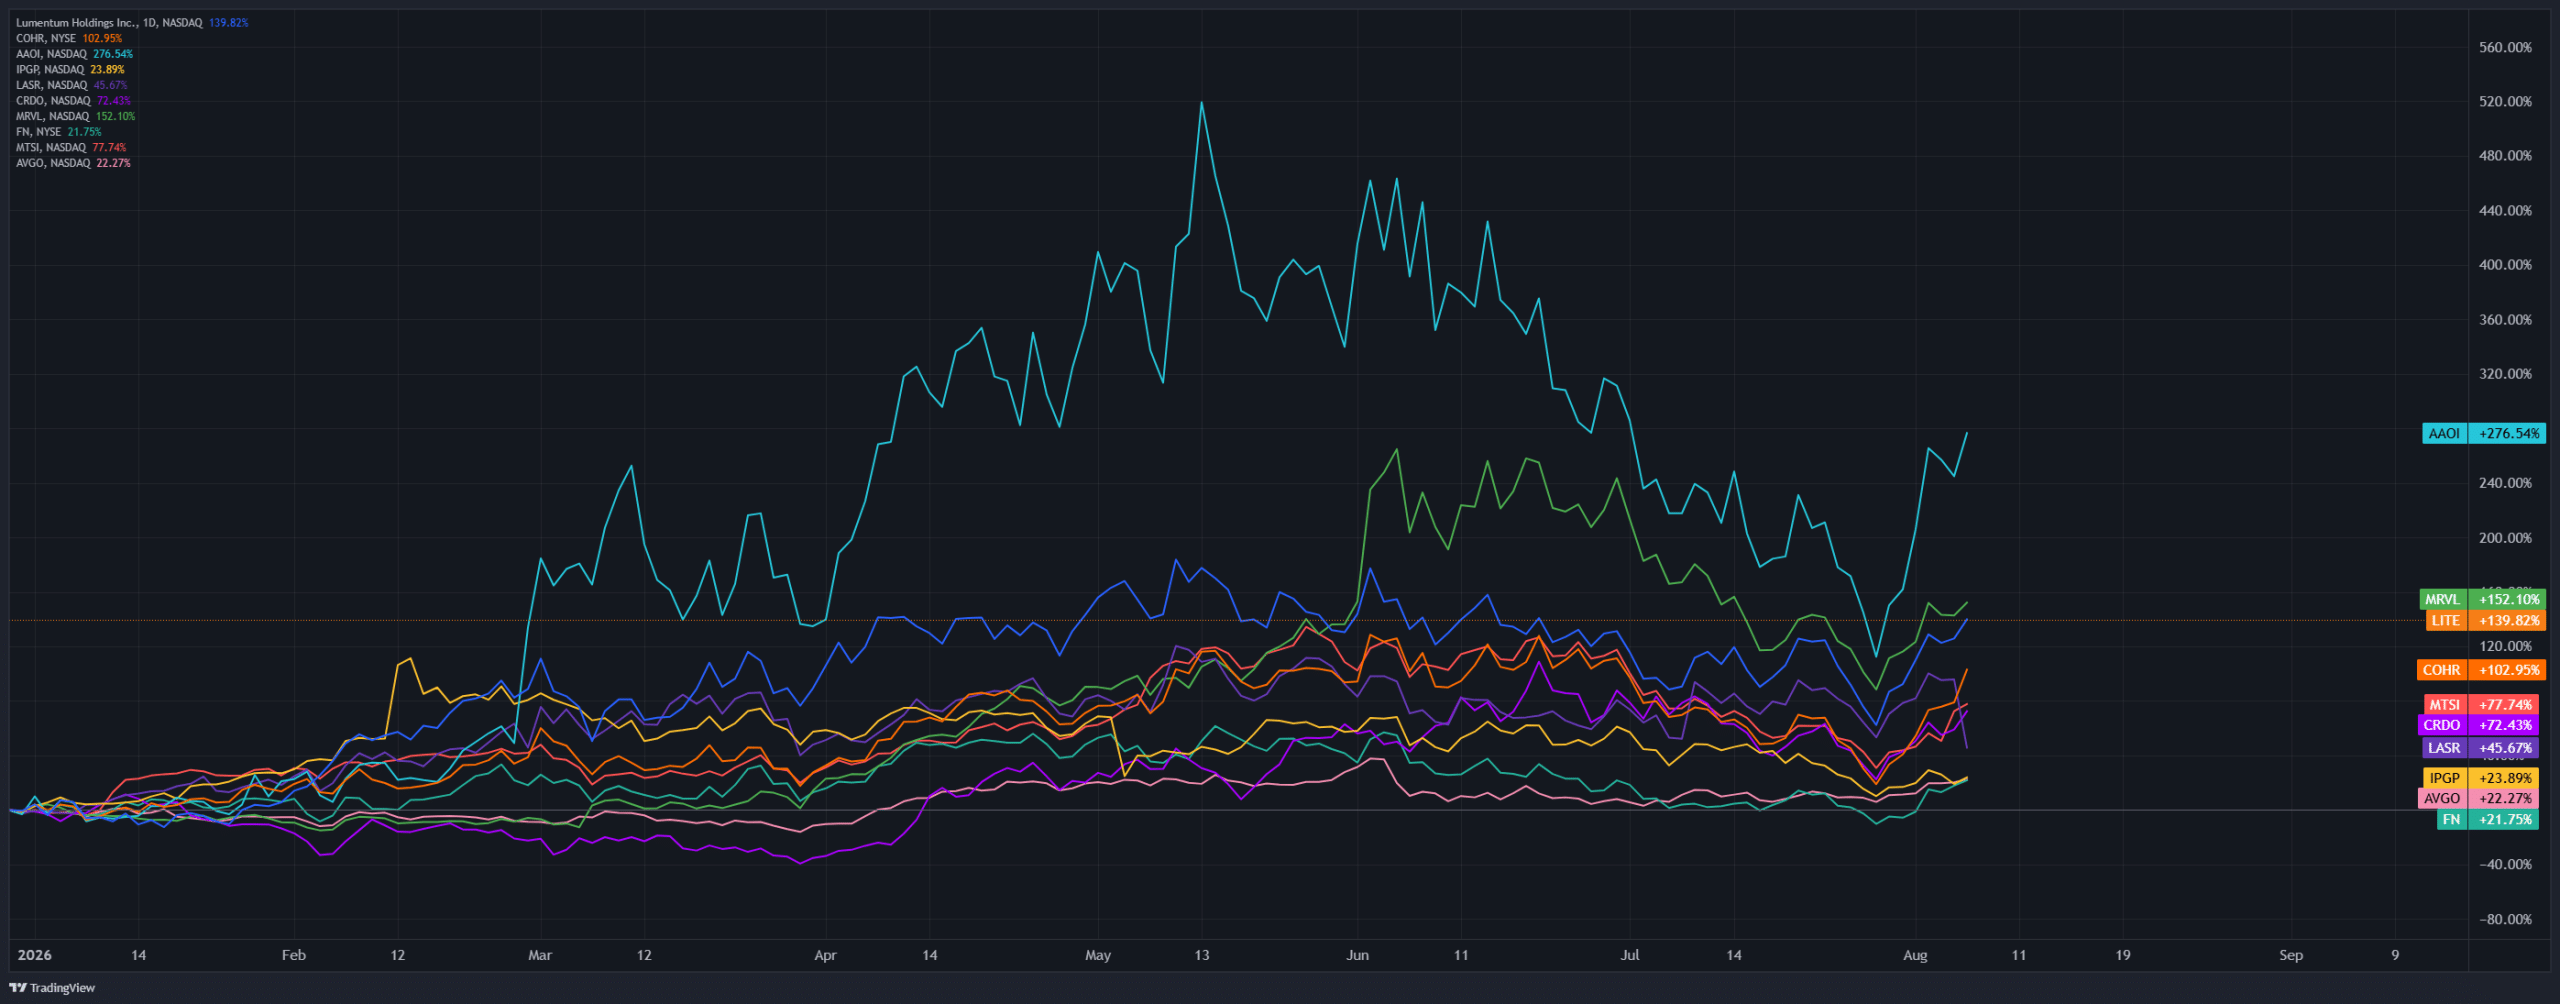
PHOTONICS
The photonics sub-sector had a pretty wild week. AAOI had earnings and COHR is due out on the 12th.
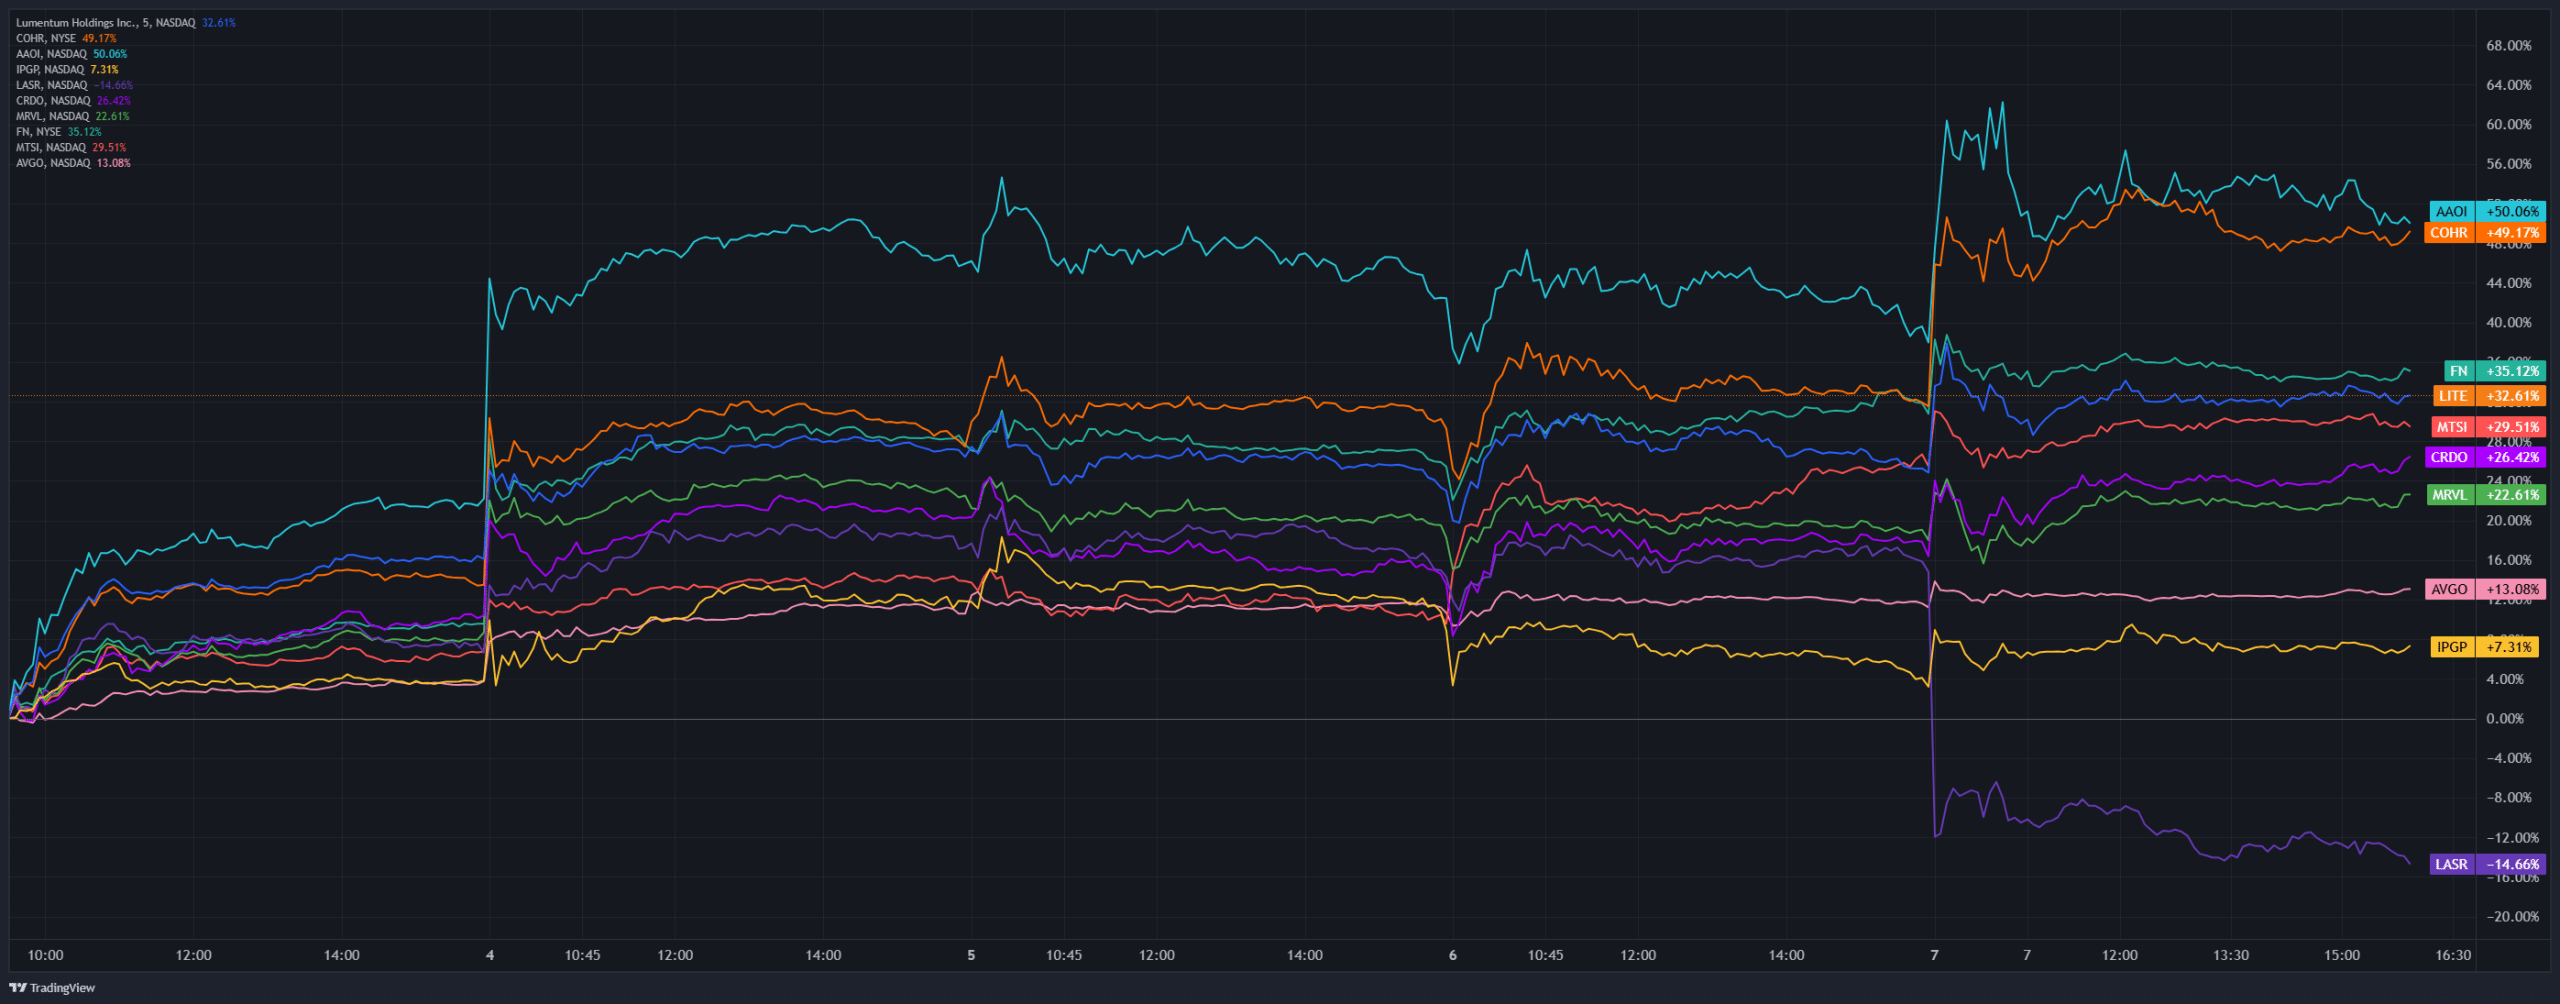
On the year, they are having some incredible moves as the AI battle continues to try to improve their tech stack offerings. Most of these names have higher implied volatilities and wider markets.
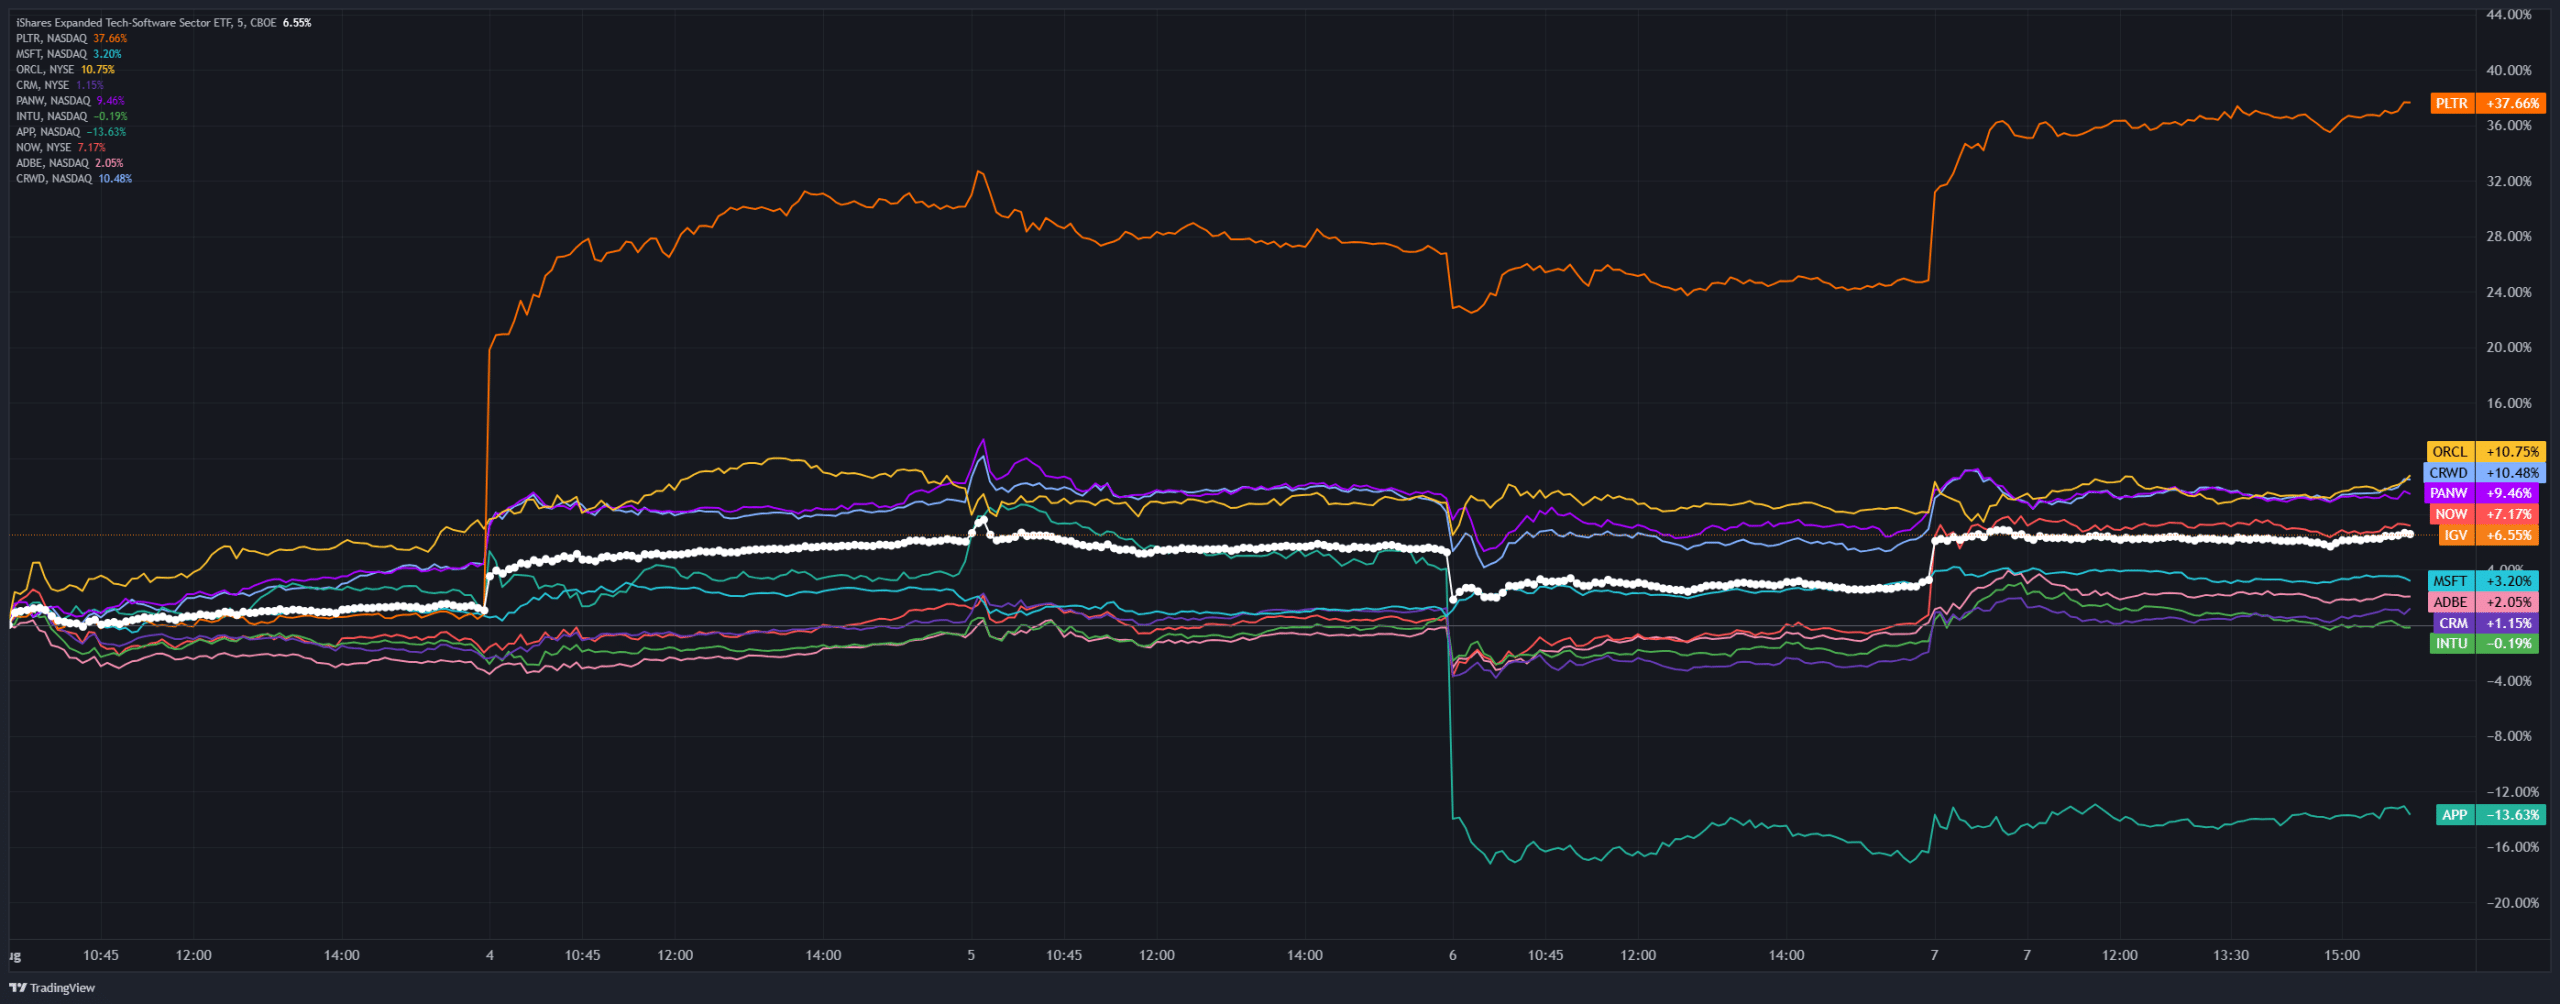
SOFTWARE (IGV)
IGV had two stocks that stood out, one for good and one bad. PLTR with a gap up early in the week on earnings while the market did not like APP’s earnings on Wednesday night. ORCL, CRWD, PANW, & NOW all had nice gains on the week.
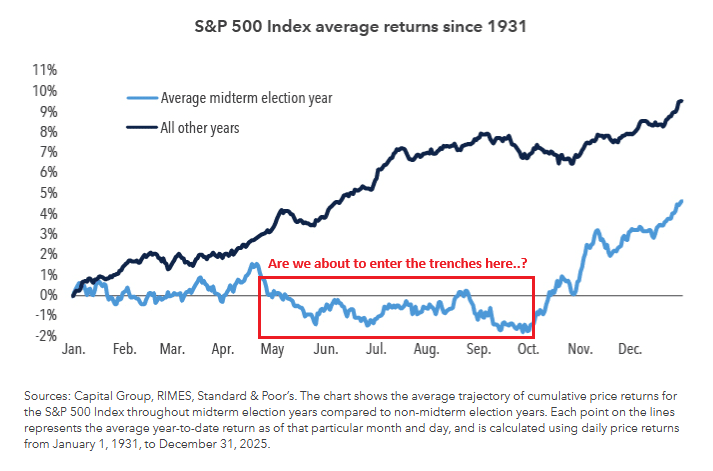
MIDTERM SEASONALITY
Still leaving this in here for obvious reasons!
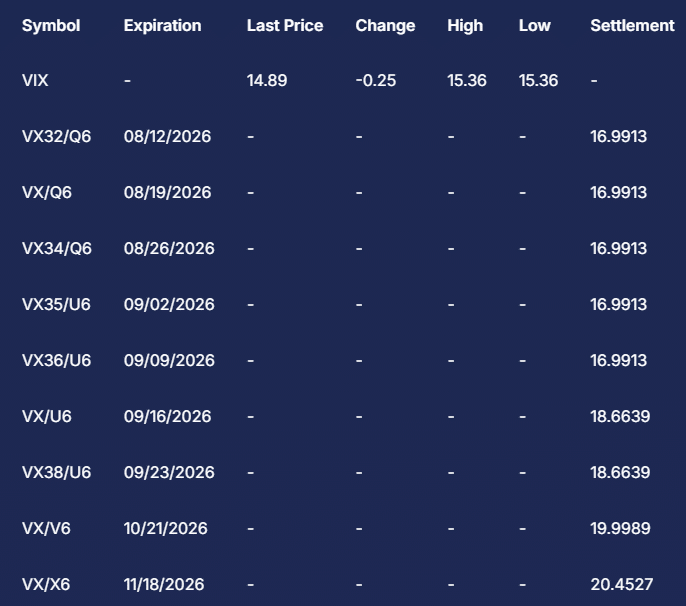
VIX
Closed at 14.9!!! This is the lowest low since January 9th! This may be an area where you can position an IV purchase as protection. Keep in mind that VIX options are based off of the baseline future. VIX options are more expensive as you go further out in time due to the uncertainty in the markets! If you do buy calls or call spreads they will moved based on that futures movement not the near term!
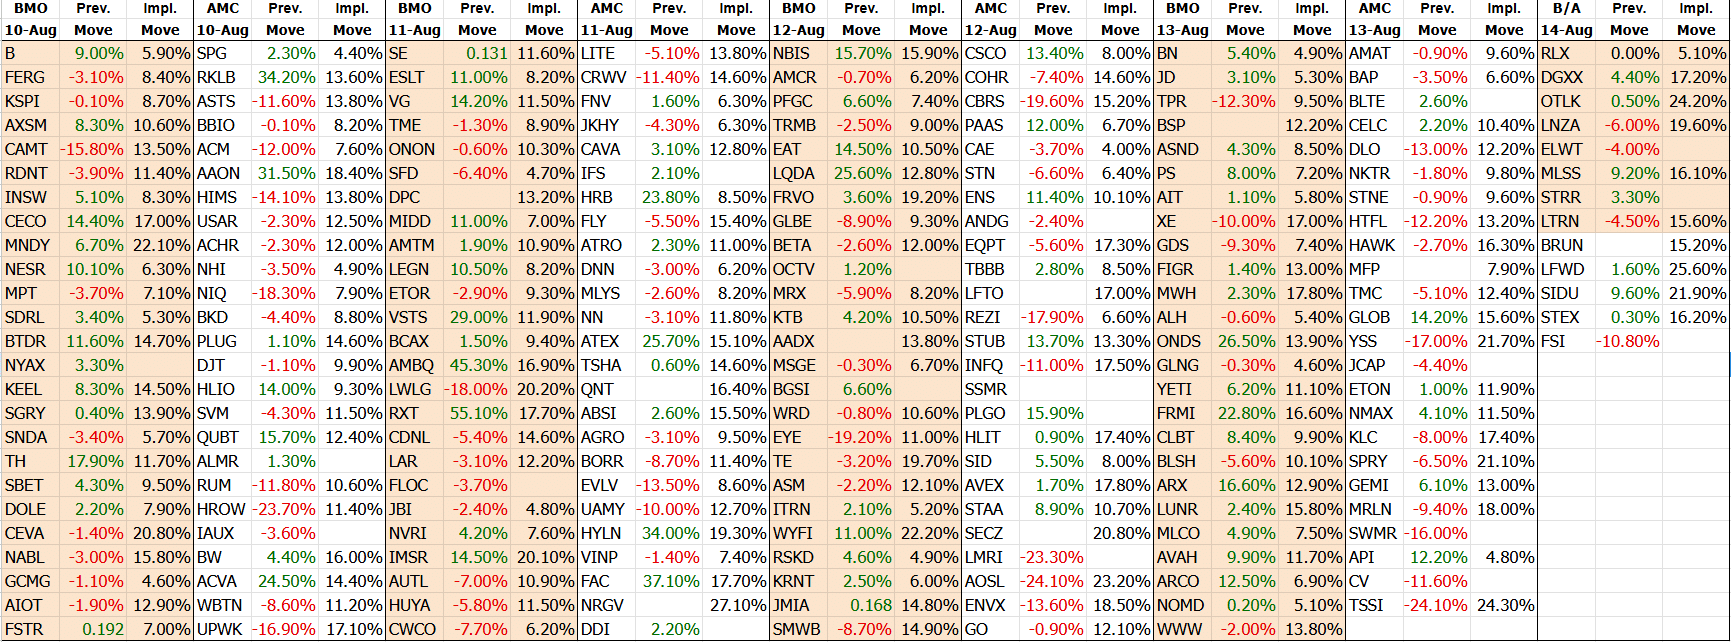
EARNINGS CALENDAR
Before Market(B- Orange), Aftermarket (A-White Background)
ECONOMIC CALENDAR
All sourced from TradetheNews.com
Monday:
11:30EDT/16:30BST US Treasury’s 3 and 6 Month Bill Auction – Source TradeTheNews.com
Tuesday:
06:00EDT/11:00BST US Jul NFIB Small Business Optimism
08:15EDT/13:15BST US Weekly ADP Employment Change
08:55EDT/13:55BST US Redbook Retail Sales
10:00EDT/15:00BST US Jul Existing Home Sales
11:00EDT/16:00BST US Treasury’s 4 and 8 Week Bill Announcement
13:00EDT/18:00BST US Treasury’s 3 Year Note Auction
16:30EDT/21:30BST API Crude Oil/Gasoline/Distillate Inventories
Wednesday:
07:00EDT/12:00BST US MBA Mortgage Applications
08:30EDT/13:30BST US Jul CPI; Core CPI; CPI Index; Core CPI Index
10:30EDT/15:30BST DoE Crude Oil/Gasoline/Distillate Inventories
12:00EDT/17:00BST USDA Agriculture Crop Production Report
12:00EDT/17:00BST USDA WASDE Report
13:00EDT/18:00BST US Treasury’s 10 Year Note Auction
14:00EDT/19:00BST US Jul Federal Budget Balance
Thursday:
08:15EDT/13:15BST US Cleveland Fed’s Beth Hammack (Voter)
08:30EDT/13:30BST US Continuing/Initial Jobless Claims
08:30EDT/13:30BST US Jul PPI Final Demand; PPI Ex-Food & Energy; PPI Ex-Food, Energy & Trade
08:40EDT/13:40BST US Richmond Fed’s Thomas Barkin (Non-Voter)
10:30EDT/15:30BST DoE Natural Gas Inventories
11:00EDT/16:00BST US Treasury’s 3 and 6 Month Bill Announcement
11:00EDT/16:00BST US Treasury’s TIPS and Bond Announcement
11:30EDT/16:30BST US Treasury’s 4 and 8 Week Bill Auction
13:00EDT/18:00BST US Treasury’s 30 Year Bond Auction
Friday:
08:30EDT/13:30BST US Jul Advance Retail Sales; Retail Sales Ex-Auto; Retail Sales Ex-Auto & Gas; Retail Sales Control Group
10:00EDT/15:00BST US Q3 Philly Fed Survey of Professional Forecasters
10:00EDT/15:00BST US Aug Preliminary U of Michigan Sentiment; U of Michigan Current Conditions; U of Michigan Expectations; U of Michigan 1 Year Inflation; U of Michigan 5-10 Year Inflation
10:00EDT/15:00BST US Jun Business Inventories
MACRO MEASURE from WAYNE RAZZI
Click image below to watch video!
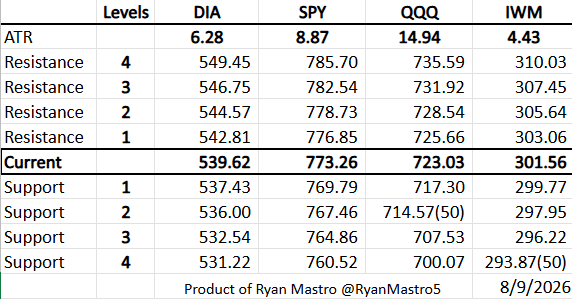
LEVELS – LARGE ETFS from @RYANMASTRO5
The week ahead:
After making record highs in the SPY, DIA and IWM we could see a market that starts to trade back into a normal volume profile. We had unusual amount of calls drive the market higher last week(gamma squeeze) after the Leo low. We need tech to broadly engage and we need speculative money to continue to flow to keep this market afloat. Earnings will come into play this week as the last big week of this cycle. We still have some big names lingering out there like NVDA on 8/26, but the quantity of names drops significantly after this week.
We do have several bond auctions that could provide some insights into how investors are feeling about inflation and current interest rates. The FX market, mainly Japan’s attempt to strengthen the the Yen could start to play a bigger factor in the carry trade unwind. A serious unwind of the carry trades would be bearish for the broad market. Over leveraged funds could be forced to liquidate in the same manner we saw South Korea deleverage with margin calls. Any increase in margin requirements at brokerage houses could paint a clear picture of concern companies that are over leveraged.
Traders could react to CPI, PPI this week on Wednesday and Thursday as the potential for a rate-hike fell sharply for September as jobs were mixed last week with cooling hawkish market pressures.
With VIX low, trading options has never been better! Good luck this week!
Good Luck this Week!
|
IMPORTANT DISCLAIMERS THIS PRESENTATION IS FOR EDUCATIONAL AND INFORMATIONAL PURPOSES ONLY AND DOES NOT CONSTITUTE INVESTMENT ADVICE, NOR THE RECOMMENDATION OF ANY SECURITY, TRADING STRATEGY OR FINANCIAL INSTRUMENT OF ANY KIND. THE INFORMATION IN THIS PRESENTATION DOES NOT CONSTITUTE TAX ADVICE, LEGAL ADVICE, OR OTHER PROFESSIONAL ADVICE OF ANY KIND. ALL INVESTMENTS INVOLVE A DEGREE OF RISK, AND THE PAST PERFORMANCE OF A SECURITY, INDUSTRY, SECTOR, MARKET, FINANCIAL PRODUCT, TRADING STRATEGY, OR INDIVIDUAL’S TRADING DOES NOT GUARANTEE FUTURE RESULTS OR RETURNS. OPTIONS AND FUTURES HAVE UNIQUE RISKS THAT INVESTORS MUST FAMILIARIZE THEMSELVES WITH BEFORE TRADING THESE INSTRUMENTS. REFERENCE TO SPECIFIC SECURITIES SHOULD NOT BE CONSTRUED AS A RECOMMENDATION TO BUY, SELL OR HOLD THAT SECURITY. SPECIFIC SECURITIES ARE MENTIONED FOR EDUCATIONAL AND INFORMATIONAL PURPOSES ONLY. THE PRESENTATION SHALL NOT CONSTITUTE AN OFFER TO BUY OR SELL ANY SECURITIES NOR SHALL IT CONSTITUTE A RECOMMENDATION OF ANY SECURITY. THIS PRESENTATION AND INFORMATION CONTAINED THEREIN IS DISTRIBUTED AS EDUCATIONAL MATERIAL AND DOES NOT CONSTITUTE “INVESTMENT ADVICE” UNDER APPLICABLE EXEMPTION FROM INVESTMENT ADVISOR REGISTRATION INCLUDING BUT NOT LIMITED TO SECTION 202(A)(11)(D) OF THE INVESTMENT ADVISERS ACT OF 1940 (ADVISERS ACT) THE “PUBLISHERS’ EXEMPTION). WHILE THE INFORMATION IN THIS PRESENTATION IS BELIEVED TO BE ACCURATE, IT HAS BEEN COMPILED NO REPRESENTATION OR WARRANTY, EXPRESS OR IMPLIED, IS MADE AS TO ITS ACCURACY OR COMPLETENESS OR FITNESS FOR ANY PURPOSE. INVESTORS ARE FULLY RESPONSIBLE FOR ANY INVESTMENT DECISIONS THEY MAKE. SUCH DECISIONS SHOULD BE BASED SOLELY ON AN EVALUATION OF THEIR FINANCIAL CIRCUMSTANCES, INVESTMENT OBJECTIVES, RISK TOLERANCE, AND LIQUIDITY NEEDS. VIEWPOINTS AND OPINIONS SHARED IN THIS PRESENTATION ARE FOR EDUCATIONAL AND INFORMATIONAL PURPOSES ONLY. THE VIEWS EXPRESSED BY US ARE OUR OWN, AND NOT NECESSARILY THAT OF MARKET REBELLION. REFERENCE TO A SPECIFIC CRYPTOCURRENCY, TOKEN, OR COIN (“DIGITAL ASSET”), IF ANY, SHOULD NOT BE CONSTRUED AS A RECOMMENDATION TO BUY, SELL, OR HOLD THAT DIGITAL ASSET. ALL INVESTMENTS INVOLVE RISK, AND THE PAST PERFORMANCE OF A DIGITAL ASSET, INDUSTRY, SECTOR, MARKET, FINANCIAL PRODUCT, TRADING STRATEGY, OR INDIVIDUAL’S TRADING DOES NOT GUARANTEE FUTURE RESULTS OR RETURNS. YOU ARE FULLY RESPONSIBLE FOR YOUR OWN INVESTMENT DECISIONS, AND THEY SHOULD BE BASED SOLELY ON AN EVALUATION OF YOUR FINANCIAL CIRCUMSTANCES, INVESTMENT OBJECTIVES, RISK TOLERANCE, AND LIQUIDITY NEEDS. IP RIGHTS NOTICE MARKET REBELLION, LLC (“MARKET REBELLION”) RETAINS ALL RIGHT, TITLE, AND INTEREST IN AND TO ALL THE INTELLECTUAL PROPERTY CONTAINED IN THE MATERIAL PROVIDED FOR AND CONTAINED HEREIN. THE CONTENT AND DESIGN OF THIS MATERIAL, INCLUDING BUT NOT LIMITED TO ALL ORIGINAL GRAPHICS, HEADINGS, ORGANIZATIONAL FLOW AND ANY OTHER MATERIALS THAT ARE COPYRIGHTABLE, OTHER THAN THOSE REFERENCED HEREIN, ARE COPYRIGHTED ©2026 BY MARKET REBELLION. ANY REPRODUCTION, MANIPULATION, SHARING OR DISTRIBUTION OF THIS MATERIAL WITHOUT THE EXPRESS WRITTEN PERMISSION AND CONSENT OF MARKET REBELLION IS PROHIBITED AND WILL BE PROSECUTED TO THE FURTHEST EXTENT OF THE LAW. THE MARKS, INCLUDING BUT NOT LIMITED TO, “MARKET REBELLION” “MARKET REBELLION EDUCATION” “THE REBEL ROUNDUP” THE REBELS EDGE” AND “MARKETREBELLION.COM,” AND ANY OTHER MARKS AND LOGOS DISPLAYED ON MARKET REBELLION’S WEBSITE, PRODUCTS, LESSONS, MATERIALS, OR COMMUNICATIONS (EXCLUDING THOSE IDENTIFIED AS THE PROPERTY OF THIRD PARTIES), ARE TRADEMARKS, SERVICE MARKS, TRADE DRESS AND THE INTELLECTUAL PROPERTY OF MARKET REBELLION AND MAY NOT BE USED WITHOUT ITS EXPRESS WRITTEN PERMISSION AND CONSENT AND ANY SUCH UNAUTHORIZED USE WILL BE PROSECUTED TO THE FURTHEST EXTENT OF THE LAW. |