Newsletters
Rebel Roundup Newsletter 8/14: Cisco Beat the Number. The Market Graded the Margin.
By Geoff Garbacz | Market Rebellion · August 13, 2026
Cisco’s Non-GAAP Gross Margin Slid to 66.3% From 68.4% as CSCO Fell 8.36% Even With EPS and Guidance Both Ahead
TODAY, WRAPPED:
The day’s dominant market belief: cooling inflation bought the Fed room to stay on hold, and investors used the record high as cover to start pricing quality, not just growth, into the AI buildout. The S&P 500 closed at a record near 7,799 (+0.65%), the NASDAQ Composite added 0.81% to 26,803.03, and the NASDAQ 100 climbed roughly 1.15% to 30,084.50. The Dow lagged, up just 0.13% to 53,839.99.
July PPI came in flat month-over-month against a 0.1% consensus, with the prior month revised up to -0.1% from -0.3%; core PPI rose 0.2% against a 0.3% consensus, with the prior month revised up more sharply, to 0.4% from 0.2%. Neither reading carried a fresh inflation surprise, but the trend read as disinflationary enough to move the odds: per CME FedWatch, the probability of a 25bp September hike fell to 34.4% from 55.0% a week ago. Weekly initial claims printed 209K against a 205K consensus, though the 4-week moving average held at a historically low 199K — a labor market still light on layoffs. The 10-year yield eased to 4.64%, WTI settled near $81, and the VIX held flat at 14.55 — one of its lowest closes of the year.
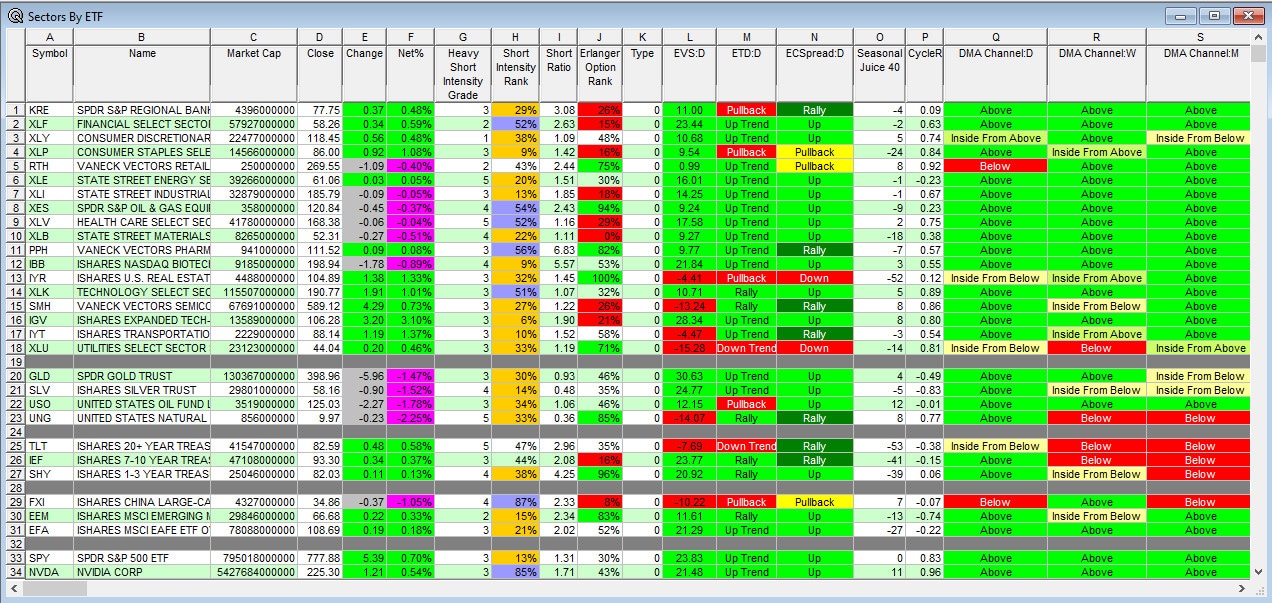
Communication Services and Technology led sector gains, Real Estate wasn’t far behind, while Basic Materials brought up the rear. The CNN Fear & Greed Index ticked up to 66 (Greed) from 62 a day earlier. That’s the story on the index level — underneath it, the earnings tape told a very different one.
THE LEAD
A market that closed at a record high spent the day punishing some of its best individual earnings prints — and the gap between those two facts is where tomorrow’s setup lives.
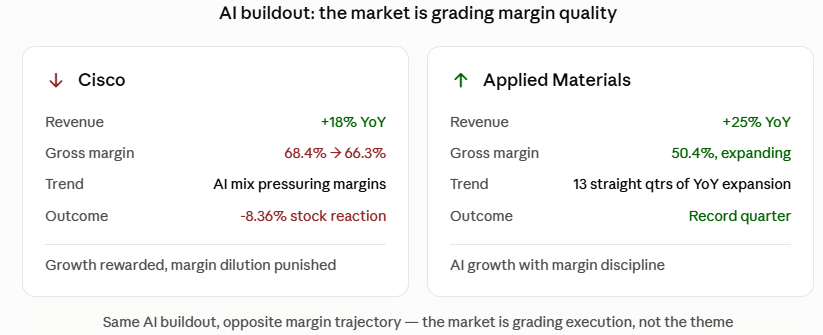
Cisco (CSCO) delivered a genuine beat-and-raise: non-GAAP EPS of $1.22 against a $1.17 consensus, revenue of $17.3 billion (+18% year over year), and AI infrastructure orders of $4 billion for the quarter and $9.3 billion for the fiscal year. Guidance for the current quarter — $18.0-18.2 billion in revenue and $1.32-1.34 in EPS — came in above what the Street was modeling. None of that saved the stock, which fell as much as 9.2% intraday before closing down 8.36%. The reason sits one line below the headline: non-GAAP gross margin fell to 66.3% from 68.4% a year ago, with product gross margin down to 64.8% from 67.5%. Management guided next quarter’s margin to 65-66%, telling investors the compression isn’t a one-quarter blip — it’s the AI hardware mix showing up in the cost structure. Coherent (COHR) fell 7.99% and Cerebras (CBRS) dropped 11.85% on their own earnings the same morning, both AI-infrastructure names getting a version of the same scrutiny.
Institutional flow offered an early clue here (details in UOA & TOA).
History offers a loose parallel. Cisco was the infrastructure-buildout stock of the late 1990s internet boom too — rewarded early for revenue growth from network spending, then increasingly judged on whether that spending converted into durable margin. The difference this time: as WSJ’s Gunjan Banerji has noted, this year earnings have broadly grown faster than prices, the opposite of a classic bubble setup — so today’s margin scrutiny reads less like a bubble bursting and more like the market doing normal quality-control on a real growth story.
Rebel’s Edge Take
Market Rebellion framed it plainly on today’s Rebel’s Edge broadcast: Cisco Crushed Earnings. So Why Is It Down? — the same question the options market was implicitly asking three days early.
Wall Street’s View
Analysts didn’t treat the selloff as a verdict on the business. Barclays raised its target to $123 from $121, KeyBanc moved to $135 from $130, and Morgan Stanley matched at $135 — all while flagging the same margin compression as a near-term overhang, not a thesis-breaker.
So what: this looks less like a Cisco problem than the first clean read on how the market plans to score the AI buildout going forward — reward the revenue, but price the margin dilution in real time. Applied Materials (AMAT) answered that question after the close: even with expanding margins and a raised guide, shares still slipped — a milder version of the same scrutiny, not a clean exoneration. Nvidia (NVDA) follows on August 26 as the bigger test. Confidence here is medium — the margin numbers are confirmed, but whether this becomes a sector-wide repricing rather than a one-stock story is still being tested.
THE MARKETS
Breadth stayed constructive into the close — advancers outpaced decliners roughly 55% to 41% — with the rate-sensitive corners of the market (Real Estate, small caps) keeping pace with mega-cap tech rather than lagging it, a sign today’s gains leaned on the rate story as much as the AI story. The session’s shape told its own story: stocks opened sharply higher on the inflation data, with the S&P briefly touching a fresh intraday record above 7,800, before giving back some of that early strength into the close. Materials and Industrials — both roughly flat to down 0.3-0.6% at midday — extended their losses to -1.28% and -0.86% by the bell, while the semiconductor complex (PHLX Semiconductor Index +2.0% at midday) held on to most of its early gains through the close.
THE BUZZ
-
AMD (AMD) plans to raise up to $4.75-5 billion in what would be its largest-ever bond sale to fund AI expansion
-
Super Micro (SMCI) extended yesterday’s post-earnings surge, closing up 5.58%
-
Netflix (NFLX) rose 4.06%, Tesla (TSLA) added 2.60%, and Meta (META) gained 1.65% as mega-cap tech broadly outperformed after a weaker showing Wednesday
-
Workday (WDAY) surged on a Reuters buyout report involving Silver Lake, lifting SaaS peers including Figma (FIG) — more in Q&A below
-
Databricks closed a $5 billion round at a $190 billion valuation, up 42% from February
-
Bill Ackman’s Pershing Square disclosed new stakes in Netflix (NFLX), Visa (V), Mastercard (MA), Alcon (ALC), Intercontinental Exchange (ICE) and S&P Global (SPGI) while exiting Hertz (HTZ)
-
Michael Burry disclosed an addition to his Nvidia (NVDA) short, comparing its $500 billion AI financing arrangement to Enron
-
Japan’s Nikkei 225 closed up 1.16% near 68,308, a third straight gain led by Advantest, Tokyo Electron and Kioxia
UOA & TOA
Cisco (CSCO) — Bullish Call Spread (Aug 10)
Three sessions before Wednesday’s report, with the stock at $124.19, a trader bought 2,000 of the Aug 14 $132 calls while selling 4,000 of the Aug 14 $137 calls — a ratio structure selling more upside than it bought.
Three sessions before Wednesday’s report, with the stock at $124.19, a trader bought 2,000 of the Aug 14 $132 calls while selling 4,000 of the Aug 14 $137 calls — a ratio structure selling more upside than it bought.
Why it matters: the skew suggests positioning wasn’t for a blowout pop even before the print — in hindsight, a clue toward the kind of capped reaction CSCO ultimately delivered.
Nvidia (NVDA) — Bullish Call Spread Roll (today)
23,250 contracts rolled up into the Sept 4 $240/$270 call spread from a 15,500-contract Sept 18 $225/$270 structure, ahead of the Aug 26 print.
23,250 contracts rolled up into the Sept 4 $240/$270 call spread from a 15,500-contract Sept 18 $225/$270 structure, ahead of the Aug 26 print.
Our read: the roll shows multi-week conviction into earnings even as Chart Room traders traded NVDA puts intraday — a split between the institutional time horizon and today’s shorter-term chop.
SpaceX (SPCX) — Bullish Call Buying (Aug 11)
Two sessions before the stock’s 35% five-day run, 6,000 of the Oct 16 $180 calls were bought in one order against open interest of just 2,908 contracts, with the stock near $135.
Two sessions before the stock’s 35% five-day run, 6,000 of the Oct 16 $180 calls were bought in one order against open interest of just 2,908 contracts, with the stock near $135.
Notable: the flow got there first — two trading days ahead of the lockup-driven surge.
GLD — Bullish Call Buying/Rolling (multiple sessions)
Gold call buying and rolling showed up on four of the last six sessions logged, even as spot gold fell 1.3% today.
Gold call buying and rolling showed up on four of the last six sessions logged, even as spot gold fell 1.3% today.
What we’re watching: persistent options accumulation into a pullback often reflects a longer time horizon than the daily tape suggests.
IGV — Bearish Put Buying (Aug 11)
20,000 of the Dec 18 $90 puts were bought in a single print with the software ETF at $104.37 — two sessions before today’s Workday-driven software rally.
20,000 of the Dec 18 $90 puts were bought in a single print with the software ETF at $104.37 — two sessions before today’s Workday-driven software rally.
Risk: a hedge that looked early two days ago now looks poorly timed, or it’s protection against a reversal of today’s M&A-driven pop.
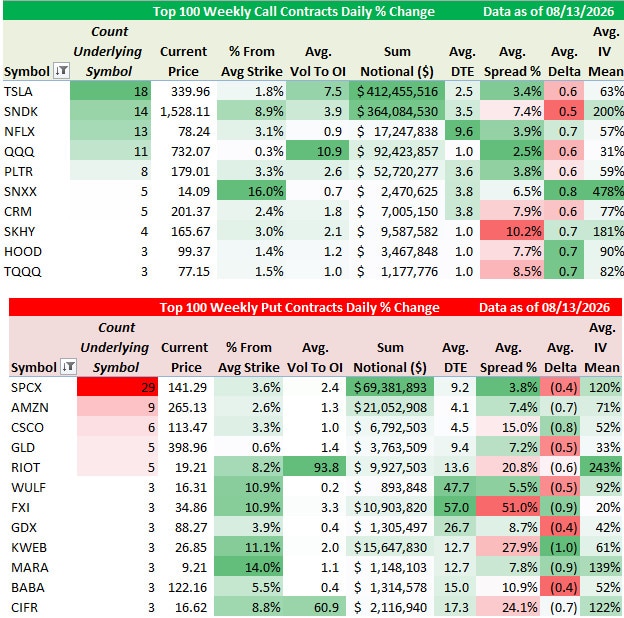
Most active options: SPCX, MU, INTC, CRWV, SMCI, NBIS, HTZ, PLTR, AMD, NOK, IREN, ORCL, MSTR
Rising volume to watch: CSCO, CBRS, AMAT, NTES, STUB, JD, TPR, YETI, LUNR, PAAS, SPCE, FOSL, RRGB
Rising volume to watch: CSCO, CBRS, AMAT, NTES, STUB, JD, TPR, YETI, LUNR, PAAS, SPCE, FOSL, RRGB
What I found interesting is that NVDA made no list on Thursday. Mexican standoff?
TOP TICKERS
Cisco (CSCO), Cerebras (CBRS), Coherent (COHR), SanDisk (SNDK), Super Micro (SMCI), Tapestry (TPR), Workday (WDAY), Applied Materials (AMAT)
AFTER THE CLOSE
Applied Materials (AMAT) answered the question fast: record Q3 revenue of $9.12 billion (+25% year over year) and record non-GAAP EPS of $3.50 (+41%), with non-GAAP gross margin expanding to 50.4% — the 13th consecutive quarter of year-over-year margin expansion — and operating margin up to 34.0% (+330bps YoY). Q4 guidance came in at $10.25 billion ± $500 million in revenue and $4.02 ± $0.20 in EPS, both above the Street’s prior estimates. Shares still slipped roughly 2.5% in after-hours trading. Where Cisco’s AI mix compressed margins, AMAT’s widened them — and the market still wanted more.
In Wednesday’s session, Geoff flagged Cerebras (CBRS)‘s after-hours slide in real time and warned that “semis could be down tomorrow off this.” Thursday’s tape bore that out.
Earnings After The Close:
-
- Beats: AMAT+0.10, HTFL +0.06 of note.
- Misses: GEMI -0.19, GLOB -0.10, KLC -0.02 of note.
- Flat: DLO QXO of note.
Movers After The Close:
-
- Winners From After The Close: CAPR +64.1%, ETON +18.4%, HTFL +15.3%, RDDT +10.5%, ACOG +10.1%, NU +8.3%,SUI +3.2%, QXO +2.4%, of note.
- Losers From Last Week: INV -43.9%, TSSI -24.1%, AMPG -22.6%, VERI -22.1%, KLC -21.5%, YSS -21.1%,CBUS -15.3%, SPRY -14.8%, GLOB -13.1%,ENHA -12.4%, KULR -12.1%, MRLN -9.5%, ALMS -8.9%, SWMR -8.8%, HAWK -8.7%, CV -7.7%, VUZI -6.8%, GEMI -6.5%, NKTR -5.7%,AMAT -5.1%, DLO -2.4% of note.
News after the close:
-
- Micron (MU) launches $250 mln AI-focused venture fund.
- Applied Materials (AMAT) prelim Q3 $3.50 vs $3.40 FactSet Consensus; revs $9.12 bln vs $8.99 bln FactSet Consensus.
- Parsons (PSN) awarded $70 mln Air Force air base defense task order.
- Firefly (FLY) wins DIU contract for Elytra deorbit mission design review.
- Tyson Foods (TSN) to close and sell more beef plants as cattle supplies remain tight.
- Winnebago (WGO) will move towable RV production to the Grand Design campus in Middlebury, Indiana, and shift B-Van motorhome production from Lake Mills, Iowa, to Forest City, Iowa.
- Lam Research (LRCX) to invest more than $3 bln over five years to expand global R&D lab network.
- White House is planning to host officials from the cryptocurrency and prediction market industries next Wednesday. (Politico)
- President Trump orders Navy to switch aircraft carriers back to steam catapults. (WSJ)
- President Trump signs proclamation imposing tariffs on drones and their parts and components . (Press Release)
- President Trump signs memo to fix critical long-term issues in Navy shipbuilding and ship repair programs and restore capacity and competition to the maritime industrial base.
- HLIT delays 10-Q.
Executive, Corporate Changes:
-
- UCB names Sean Simpson chief commercial banking officer.
- LULU discloses that Ranju Das has ceased to serve as Chief AI & Technology Officer; co has transition plans in place for his responsibilities.
- SYF names Citi’s Nimrod Barak chief AI officer.
Buybacks of Note:
-
- ABX authorizes $100 mln share repurchase program.
- WRLD authorizes new $50 mln share repurchase program.
Dividend Changes & Ex-Dividend Stocks:
- Stocks Going Ex-Dividend Friday
- Stocks Going Ex-Dividend Monday
- CBOE increases quarterly cash dividend to $0.86/share from $0.72/share.
THE REAL STORY
The Lead’s tension was earnings quality — strong AI-linked revenue growth against margin compression. One asset class over, in credit, a related but distinct question is forming: is the financing side of the AI buildout starting to strain before the equity side does?
AMD (AMD) plans to raise up to $4.75-5 billion in its largest-ever bond sale; Nvidia-backed AI cloud provider Lambda just closed a $926 million leveraged loan; and today’s 30-year Treasury auction tailed, pricing at the highest yield since 2001 — a sign that even the safest long-duration paper is getting harder to place cheaply. None of this is a red alarm on its own, but it’s the same AI-capex bill showing up in a different ledger than Cisco’s income statement.
If AI-linked bond and leveraged-loan issuance keeps clearing at reasonable spreads, today’s Cisco-style scrutiny stays a stock-picking story. If high-yield spreads on AI-adjacent credits start widening while equities hold near records, the margin story graduates from “which chip company” to “can the buildout be financed at all” — a genuinely different, and larger, question. Confidence here is low — this is Narrative-level, built from scattered credit-market commentary rather than one confirmed data point.
Playbook:
-
Watch: high-yield spreads on AI-linked issuers relative to the broader HY index (~272bps recently)
-
Confirm: a tailing AI-linked bond deal (like AMD’s pending sale) or a widening in AI-adjacent credit spreads without an accompanying equity selloff
-
Invalidate: AI-linked issuance continues to clear at reasonable spreads with no meaningful deterioration relative to the broader HY market
QUESTIONS FROM THE ROWDY REBELS
Q: Given his ties to Maryland and background as an athlete, what’s his read on Under Armour (UA), which has struggled for years? — Mell U.
A (Geoff Garbacz): Insiders are buying and short sellers are adding — the “wrong kind” of shorts pairing with insider buying makes it interesting, though Nike (NKE) and On Holding (ONON)‘s struggles mean he wants more confirmation before calling it a trade.
A (Geoff Garbacz): Insiders are buying and short sellers are adding — the “wrong kind” of shorts pairing with insider buying makes it interesting, though Nike (NKE) and On Holding (ONON)‘s struggles mean he wants more confirmation before calling it a trade.
Q: Was there any news on Figma (FIG)? It’s been straight up since 2:30. — Donna Rocco
A (Akiko): No company-specific news identified — the move looks like sympathy buying across SaaS names after Reuters reported Silver Lake is in talks to acquire Workday (WDAY). This is a beaten down stock and value buyers are circling which is why Geoff put on a LEAP strategy.
WATCHLIST
AI Capex Margin Scrutiny
Applied Materials (AMAT) delivered its 13th straight quarter of year-over-year margin expansion, yet still slipped roughly 2.5% in after-hours trading — a far milder version of Cisco’s reaction, but the same direction. The pattern isn’t purely Cisco-specific; the bar for “good enough” on AI infrastructure earnings has risen across the board. NVDA‘s Aug 26 print remains the bigger test of how far this extends.
Applied Materials (AMAT) delivered its 13th straight quarter of year-over-year margin expansion, yet still slipped roughly 2.5% in after-hours trading — a far milder version of Cisco’s reaction, but the same direction. The pattern isn’t purely Cisco-specific; the bar for “good enough” on AI infrastructure earnings has risen across the board. NVDA‘s Aug 26 print remains the bigger test of how far this extends.
Financing the Buildout
Bull: AI-linked bond and leveraged-loan issuance keeps clearing at reasonable spreads, and today’s tailing 30-year auction proves to be a Treasury-specific story.
Bear: high-yield spreads on AI-adjacent credits start widening even as equities hold near records — an early-cycle divergence between the two markets.
Bull: AI-linked bond and leveraged-loan issuance keeps clearing at reasonable spreads, and today’s tailing 30-year auction proves to be a Treasury-specific story.
Bear: high-yield spreads on AI-adjacent credits start widening even as equities hold near records — an early-cycle divergence between the two markets.
The index closed at a record today. The margin line item didn’t get the memo at Cisco — and even Applied Materials, with expanding margins and a raised guide, still felt a version of the same scrutiny tonight.
YOUTUBE