Newsletters
Rebel Roundup Newsletter For 7/22: Alphabet and Tesla Drop On Earnings. Thursday Could Be Interesting To Say The Least.
By Geoff Garbacz | Market Rebellion · July 22, 2026
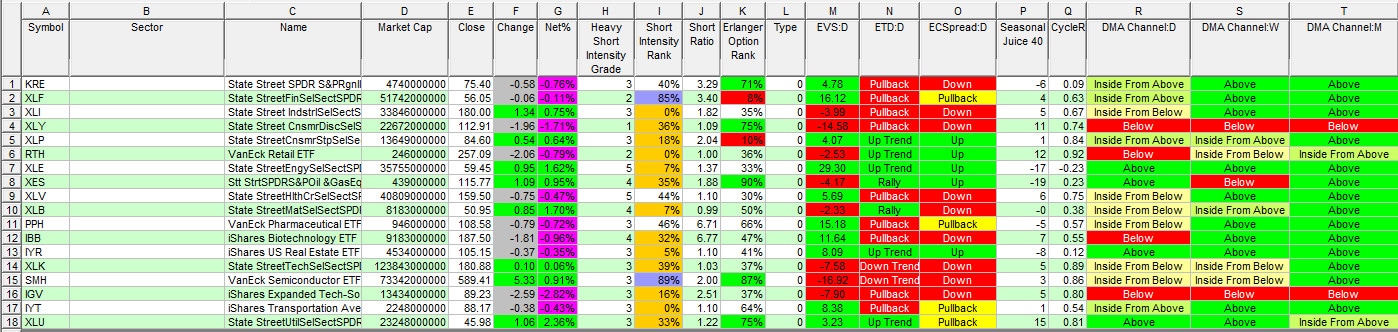
TODAY, WRAPPED:
Stocks from 12:00 p.m. at the one hour low to below the day’s support level. Then lots of earnings after the close with oil spiked higher as Iran keeps threats high giving the VIX its biggest jump of the month. Alphabet and Tesla reported negative free cash flow.
● S&P 500: 7,498.96 (-10.24, -0.14%)
● Dow: 52,218.58 (-6.06, -0.01%)
● Nasdaq Composite: 25,690.90 (-146.31, -0.57%)
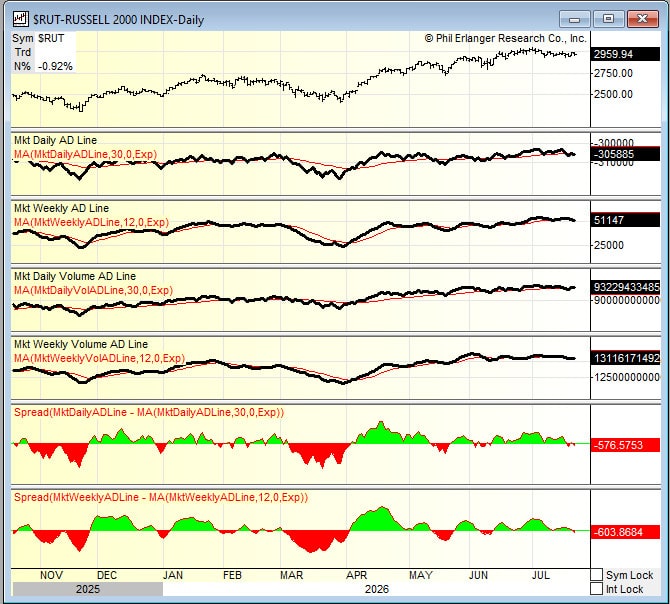
● Russell 2000: 2,957.48 (-27.46, -0.92%)
● VIX: 19.49 (+2.44, +14.31%)
● 10-Year Yield: 4.66%
● WTI: $87.35 (+2.20%); Brent near $95
● Gold: $4,134.65 (+1.34%); Silver: $59.70 (+1.60%)
● Bitcoin: $65,861 (-0.99%)
That VIX print matters more than the index-level move suggests. A -0.14% S&P day doesn’t
normally come with a 14% vol spike; the market was nervous before either earnings report hit
the tape.
Breadth confirmed the unease: only 38.9% of names advanced against 57.2% declining, and
new lows (138) outnumbered new highs (111) for the first time in a week. Sector leadership
flipped hard from Tuesday — Utilities (+2.15%) and Basic Materials (+1.92%) led,
Communication Services (-1.40% today, -6.38% for the week) trailed everything, as GOOGL
and META got sold ahead of their own numbers.
QUOTE OF THE DAY
“We don’t need the Hormuz Strait.” — President Donald Trump, July 22, 2026.
THE BIG FIVE EVENTS FOR :
1. Alphabet Doubles Capex, Beats EPS by 3x — But the Beat Isn’t What It Looks Like
Alphabet (GOOGL) posted EPS of $9.11 against a Street estimate of $2.89. Strip out a $98.0
billion unrealized markup on its equity stakes — mostly Anthropic — and the underlying print
lands closer to $2.85, roughly in line. The real story sits elsewhere: Google Cloud revenue
accelerated to 82% growth, and capex hit $44.9 billion, up 100% year-over-year for a fourth
straight quarter of accelerating spend — a run rate near half a billion dollars a day. That pushed
quarterly free cash flow to negative $5.86 billion, the first negative print Alphabet has disclosed.
The stock dropped $10 immediately after the print before recovering toward flat once the
earnings call began, exactly the split-decision reaction a beat-with-an-asterisk should produce.
Cloud’s 82% growth is the strongest evidence yet that the AI trade is generating real revenue,
not just real spending — and that distinction will matter more than the headline EPS number
once analysts finish adjusting for the Anthropic markup.
Playbook
Watch: Whether sell-side models exclude the equity-gain boost when resetting 2026 EPS
estimates.
Confirm: Cloud backlog conversion accelerates and 2027 capex guidance comes with a
specific ROI framework.
2. Tesla’s Best-Ever Quarter for Deliveries Comes With Its Worst Margin in Years
Tesla (TSLA) delivered a record 480,126 vehicles, up 25% year-over-year and roughly 74,000
above consensus, while trimming inventory to 15 days of supply from 27 the prior quarter. None
of that showed up in profitability: operating margin collapsed to 1.4% from 4.1% a year ago,
non-GAAP EPS came in at $0.33 against a Street estimate near $0.54, and capex of $5.79
billion — up 142% year-over-year — pushed free cash flow to negative $1.09 billion. Robotaxi is
scaling (unsupervised rides now live in Miami, Orlando, and Tampa) and Services gross profit hit
a record $648 million, but the core auto business is absorbing the same AI infrastructure bill
Alphabet is paying, without Alphabet’s ad-revenue cushion. The symbolism cuts deeper on the
factory floor: the Model S and X lines at Fremont — the car that took Tesla mainstream in 2012
— have been decommissioned and replaced with first-generation Optimus production lines.
Record demand paired with vanishing margin means the AI-and-robotics narrative is now
directly competing with automotive profitability for the same dollar, and Tesla just handed one of
its founding product lines over to prove which one wins.
Playbook
Watch: Management commentary on the earnings call about AI/robotics spend timing versus
near-term margin recovery.
Confirm: Services and Energy Storage profitability keeps growing fast enough to offset
automotive margin compression.
3. Hormuz’s Southern Route Gets Mined, and Trump Says the U.S. Doesn’t Need It
Iran’s Revolutionary Guards warned shipping companies that the southern route through the
Strait of Hormuz is mined, hours after Trump vowed the U.S. would destroy an Iranian bridge or
power plant for every ship Iran targets there — and by afternoon, Trump was framing the Strait
itself as dispensable. Commercial traffic through Hormuz has fallen to a three-week low, and
Brent briefly topped $95 for the first time in six weeks. Iran’s Araghchi countered that “any
aggression against Iran, including our infrastructure, will compel a powerful and decisive
response,” while Kalshi markets price only a 31% chance shipping normalizes there before
December.
A president calling a critical global chokepoint unnecessary is either confident bluster or a signal
the U.S. is preparing to route around it — and DP World’s new deepwater terminals bypassing
Hormuz entirely suggest the private sector is already betting on the latter.
Playbook
Watch: Whether Iran follows through on strikes against U.S.-linked regional infrastructure.
Confirm: Oil holds above $90 into Friday’s tariff deadline with no de-escalation signal.
4. GE Vernova Misses on EPS, Beats on Everything Else, and Still Drops 8.7%
GE Vernova (GEV) missed EPS ($2.47 versus $3.10 expected) but beat on revenue ($11.1
billion versus $10.8 billion) and raised full-year guidance to roughly $46 billion — and the stock
still fell 8.69%, the worst move in the S&P 500 today. Bloomberg’s read was blunt: it’s getting
harder for companies selling equipment into the data center buildout to clear a bar that keeps
rising faster than their results. SuperMicro (SMCI) sat on the other side of that same coin,
jumping 19.76% on a preliminary update showing gross margins nearly doubling and a record
$60 billion order backlog.
Two AI-infrastructure suppliers, two opposite reactions on the same day: the market isn’t pricing
“AI capex beneficiary” as one trade anymore, it’s pricing which of these companies can actually
afford to keep building at this pace — the same capital-spending question running through
tonight’s two headline earnings reports.
Playbook
Watch: Whether SMCI’s disclosed export-control review resurfaces as a risk before its August
11 full report.
Confirm: More data-center equipment suppliers see GEV-style reactions on in-line-or-better
results.
5. Goldman Puts a Number on the AI Debt Wave: $489 Billion and Counting
Goldman Sachs estimates roughly $489 billion in AI-related debt has been issued this year, with
Microsoft, Amazon, and Meta accounting for about 40% of it — and Alphabet’s own filing shows
it raising $49.6 billion in fresh equity and $20.3 billion in new debt in the same quarter it posted
negative free cash flow. Galaxy Digital is separately preparing a $3.5 billion junk-bond sale for a
CoreWeave-linked data center, and IG credit now yields 5.40%, a fifteen-month high — the
same signal Oracle’s widening CDS spread has been sending for weeks.
AI infrastructure is increasingly being financed through capital markets rather than operating
cash, even at companies with balance sheets as strong as Alphabet’s — which means the
constraint on this trade is shifting from demand to who can still borrow cheaply enough to keep
funding it.
Playbook
Watch: Credit spreads on hyperscaler and data-center-adjacent debt into next week’s earnings.
Confirm: More companies follow Alphabet’s pattern of raising equity and debt in the same
quarter capex accelerates.
Market ANALYTICS:
TRACKING TODAY’S ACTION
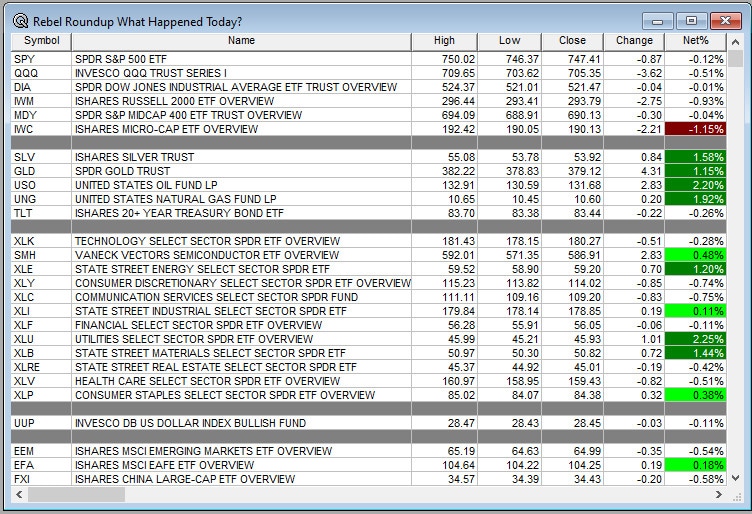
TOD DOG
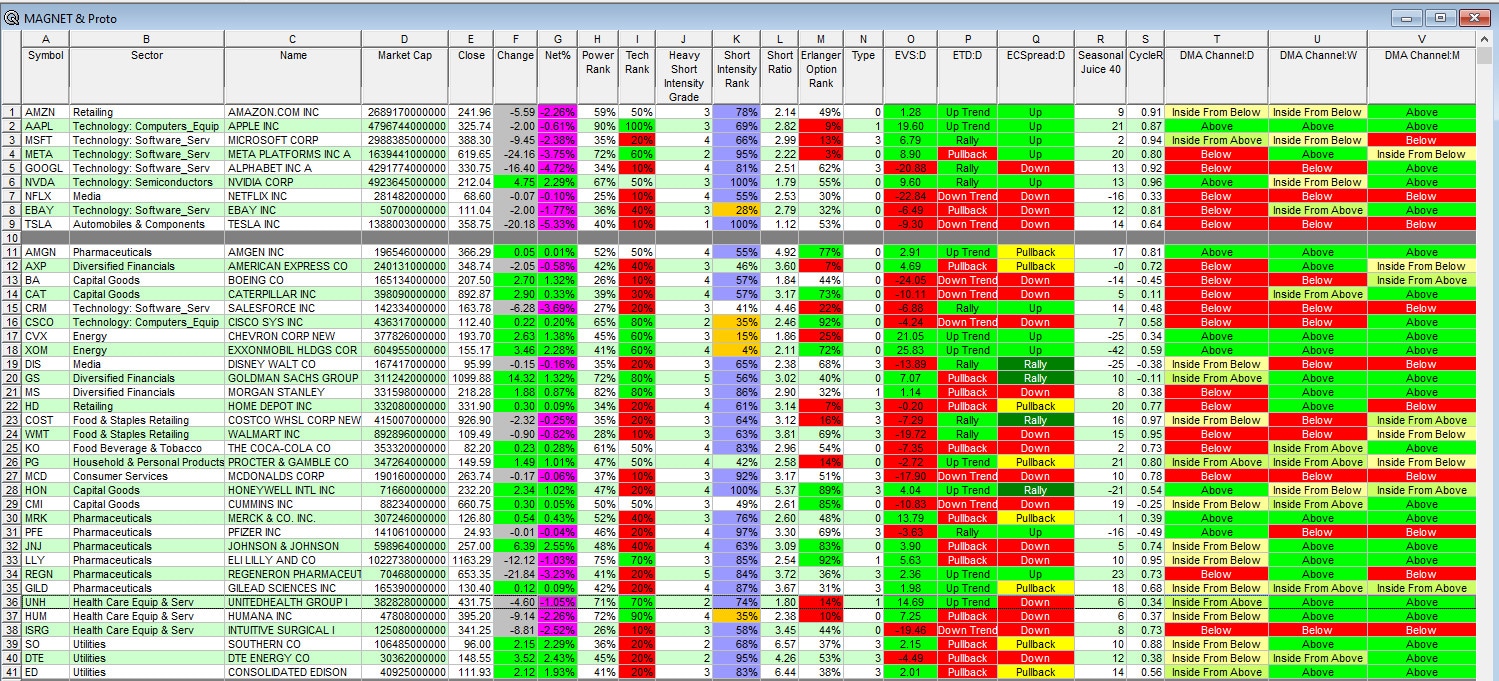
BREADTH
UOA AND TOA:
COIN (Coinbase Global) — Bullish Call Buying. 3,800 July 24 200 calls bought mostly in one
order for 0.26-0.35, above open interest of 2,880 contracts, stock trading $172.46-174.80.
Something to consider: a moderately out-of-the-money call bet timed against today’s Clarity Act
headlines and continued institutional Bitcoin buying suggests the buyer expects a binary
catalyst before Friday’s expiration. If the Senate vote timeline holds, this pays well; if the bill
stalls again, the premium decays fast.
DRAM — Bullish Call Spread. 25,000 July 31 63/73 call spread bought for 2.12-2.14, sold for
0.37-0.18, above open interest on both legs, stock trading $57.31-57.78.
Something to consider: this lines up with UBS’s forecast that SK Hynix revenue could top $500
billion by 2028 on HBM demand outpacing supply. The capped structure reads as high
conviction on the memory supercycle continuing through month-end without betting on an
unbounded blowoff — well-positioned if tonight’s earnings confirm capacity remains the binding
constraint.
PBR (Petrobras) — Bullish 4-Way. 10,000 December 18 22/30 call spread bought against a
15/8 put spread sold, underlying trading $18.86-19.07.
Something to consider: buying upside while selling downside protection and buying deep tail
insurance reads as a hedger managing existing exposure, following a similar three-way trade
from yesterday’s log. This benefits from oil staying elevated on the Hormuz standoff without an
outright supply shock.
CORZ (Core Scientific) — Bullish Call Buying. 10,000 August 21 29 calls bought for
0.97-1.04, above open interest of 902 contracts, the most recent print of the day at 3:57 PM.
Something to consider: Core Scientific sits at the intersection of crypto infrastructure and AI
compute, and this trade landed after both GOOGL and TSLA had confirmed capex is
accelerating industry-wide. If that spending wave keeps favoring compute-hosting names
regardless of workload, this extends; if the financing concerns from Event 5 start compressing
valuations sector-wide, small-cap infrastructure plays are typically first to feel it.
VIX — Bullish Call Buying (from July 21, confirmed by today’s action). A combined roughly
72,000 August 19 29 calls bought across two prints on July 21 for 0.60-0.67, against a spot VIX
then in the 17s.
Something to consider: spot VIX closed today at 19.49, still below the 29 strike, but today’s
14.31% jump means the position’s vega expanded sharply without the strike coming into range.
If Iran follows through on infrastructure strikes or the earnings reaction spills into a broader
selloff, this keeps gaining value; if the market digests tonight’s numbers calmly, the premium
bleeds fast this far out of the money.
THE DAILY DASHBOARD: LEADERS AND LOSERS
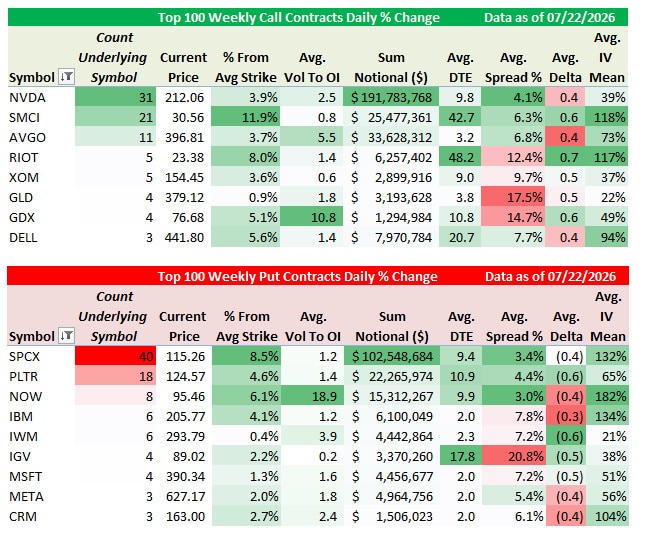
We now track where option players made the most money today on both the Call and Put side. 0DTE are not part of the calculation.
AFTER THE CLOSE
Notable Earnings Out After The Close:
- Beats: GOOG +6.23, KALU +2.87, URI +1.22, RNR+1.20, RS +0.80, CCS +0.66, LUV +0.43, FAF +0.31, WEX +0.28, MEDP +0.27, SEIC +0.22, SLG +0.22, RJF +0.21 of note.
- Misses: STC -0.24, TSLA -0.20, LVS -0.17, CYH -0.09, EPRT -0,04, ROL -0.02, IBM -0.02, GL -0.02 of note.
- Flat: EGP GTY of note.
Winners From Wednesday: NVEC +31.5%, RELL +17.4%, URI +10.5%, OII +8.2%, CSX +4.6%, NOW +4.4%,
Losers From Tuesday: ROL -14.9%, MOH -9.8%, CYH -7.8%, SSTK -6.9%, LVS -5% TSLA -4.2% and GOOG -4%, QS -4.9%
- Texas Instruments (TXN) beats by $0.15.
- Alphabet (GOOGL) prelim Q2 $9.11 vs $2.88 FactSet Consensus; revs $119.8 bln vs $117.07 bln FactSet Consensus.
- Capital One (COF) prelim Q2 $5.81 vs $4.67 FactSet Consensus; revs $15.9 bln vs $15.77 bln FactSet Consensus.
- Encore Capital (ECPG) to redeem all $230 mln of 4.00% convertible notes due 2029.
- Tesla (TSLA) misses on prelim Q2 $0.33 vs $0.53 FactSet Consensus but beats on revs $28.24 bln vs $26.42 bln FactSet Consensus.
- Las Vegas Sands (LVS) misses by $0.17, misses on revs; increases repurchase.
- IBM a tad light as prelim Q2 $2.93 vs $2.95 FactSet Consensus; revs $17.16 bln vs $17.46 bln FactSet Consensus.
- ServiceNow (NOW) beats by $0.04, beats on revs; raises FY26 subscription revenue guidance.
- X-Energy (XE) joins DOE-backed Project Prometheus with NVIDIA and AWS on AI-driven nuclear deployment.
- Progress Software (PRGS) to buy substantially all of Domo’s AI and data platform assets for $400 mln cash.
- United Rental (URI) beats by $1.22, beats on revs; raises FY26 revs above consensus.
- Southwest Air (LUV) beats by $0.43, misses on revs; guides Q3 EPS below consensus; guides FY26 EPS above consensus.
- Chevron (CVX) asking court to enforce a $224 million award against Ecuador. (Bloomberg)
- House passes bill that bans lawmakers from purchasing stocks; sending it to the Senate.
- House passes National Defense Authorization Act by a vote of 216-212; sending to the Senate.
- Trump’s Boeing deal with China hits a hurdle amid new demands. (Politico)
- Labcorp Holdings (LH) awarded $364.7 mln Defense Health Agency contract.
- 10Q Delays – None of note.
Executive, Corporate Changes:
- GSHD CEO Mark Miller to retire; Mark Jones Jr. to become CEO on Jan. 1.
- JXN names CFO Don Cummings CEO effective Oct. 1 as Laura Prieskorn plans retirement.
- TTC names Edric Funk CEO effective Nov. 1; Richard Olson to become Executive Chairman.
- KROS discloses the resignation of CFO Keith Regnante.
Buybacks of Note:
- LVS ups buyback.
Dividend Info:
- STX NXPI ABEV GFS BFC ITRN goes Ex-Div Thursday.
- goes Ex-Div Friday.
- SCHL increases quarterly dividend 25% to $0.25/share from $0.20/share.
- HOMB announces an increased quarterly cash dividend to $0.23/share from $0.21/share.
QUESTIONS FROM THE ROWDY REBELS
Q: Do you have a put/call ratio for GOOGL? It looks like the market is leaning bullish on
GOOGL. — Mike M.
A: Erlanger Option Rank is neutral, so it doesn’t favor either side structurally. That said, our
seasonality data — the same signal that supported puts on NFLX last week — is positive for
Google over the next few months, so if you’re using options here, the call side is the
better-supported trade. — Geoff Garbacz.
Q: Thoughts on GOOGL heading into tonight’s earnings? — Mell U.
A: The at-the-money straddle was pricing an implied move of about $18.50, putting the range at
$364.50 to $327.50 — a level that conveniently sits right on rising support and near the trigger
for a messy cup-and-handle pattern. There’s been a steady buildup of paper in capex
beneficiaries over the past couple weeks, with even more DRAM activity today, so the read is
“increased spend, unclear how the market treats the spenders” more than a clean directional
signal. Most of the GOOGL options flow has been longer-duration, suggesting conviction in the
multi-week uptrend rather than a bet on tonight specifically. — Chris Sykora.
Q: Porter Stansberry’s Daily Journal flagged that short interest across all NYSE-listed
stocks hit a record 9.0% of shares outstanding in late June — above the 5.0% peak
during the 2008 Financial Crisis and 6.0% during the 2020 pandemic. Does your work
show anything similar? Is this pre-slump positioning? — Allen F.
A: Yes, short interest is at all-time highs. That said, the conclusion being drawn from it is the
wrong one — we’ll dig into why on the next webinar on Tuesday for Rebel Pro Subscribers. If you want to listen inm then contact your sales person and they will get you set up. — Geoff Garbacz
WATCHLIST
AI Capex & Cash Generation
Bull: Google Cloud’s 82% growth and Tesla’s record deliveries with a 55%+ FSD attach rate
suggest the spending is converting into real demand — Alphabet’s own Cloud history shows
years of heavy investment eventually becoming the profit engine.
Bear: Negative free cash flow at both a search monopoly and a record-delivery automaker in the
same quarter means the AI buildout has outgrown what operating cash can fund, and
Goldman’s $489 billion debt estimate shows the gap is being plugged with leverage
industry-wide — if capital markets get pickier before the spend inflects into profit, financing
becomes the constraint, not demand.
Iran / Hormuz Escalation
Bull: DP World’s new deepwater terminals bypassing Hormuz, plus Trump’s own framing that
the U.S. “doesn’t need” the Strait, suggest the structural risk is being engineered around even
as rhetoric escalates.
Bear: A mined southern shipping route, a three-week low in commercial traffic, and Kalshi
pricing only a 31% chance of normalization before December all point toward extended
disruption — and Iran’s threat to treat any “contributor” to U.S. strikes as a legitimate target
raises the odds of the conflict widening.
Rate Path Into Next Week’s FOMC
Bull: Prediction markets still put no-change odds at 72-85%, and a Reuters poll has the median
economist forecast holding rates steady through 2026.
Bear: The 30-year yield is on pace for its best weekly print since 2007, and today’s 20-year
auction came in soft — if the bond market keeps pricing sticky inflation regardless of the Fed,
elevated long-end yields pressure equity valuations independent of the actual meeting.
Rebel’s Edge For 7/22 (from You Tube link – RebelsEdgeOfficial):