Newsletters
Rebel Roundup Newsletter For 8/12: Wall Street Pays For Proof, Not Promises
CoreWeave Jumped 19.2% and Super Micro 18.8% While Meta Fell 3.4% as July CPI Landed In Line
TODAY, WRAPPED:
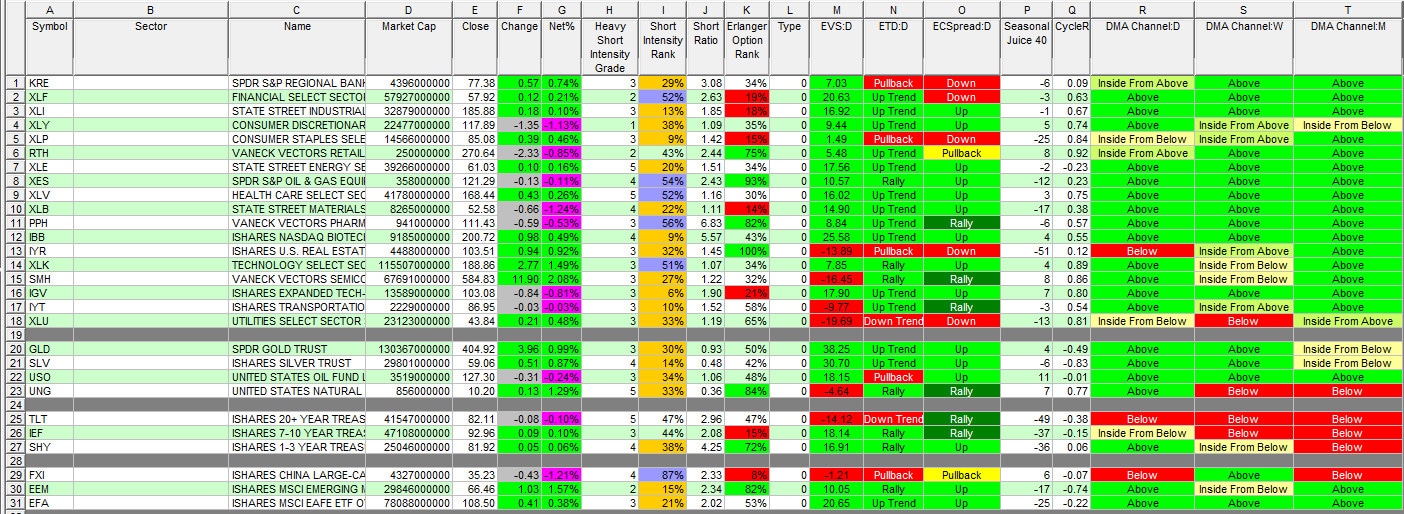
The day’s dominant market belief: execution beat narrative. The S&P 500 (SPX) closed at 7,748.50, up 0.26%, while the NASDAQ Composite added 0.54% to 26,588.50 and the NASDAQ 100 outran it with a 0.74% gain to 29,742.60. The Dow Jones Industrial Average slipped 0.04% to 53,770.30.
July CPI landed exactly on consensus — headline +0.1% m/m and +3.4% y/y, core +0.2% m/m and +2.5% y/y — removing one immediate macro obstacle standing between the market and its record highs. But the rally that followed wasn’t a rising tide. Technology and Industrials led sectors, up 1.38% each; Communication Services fell 0.88% and Consumer Cyclical dropped 1.28%.
The VIX sank to 14.46, a fresh multi-month low, even as the Fear & Greed Index eased from 64 to 61 — greed, but slightly less of it than yesterday.
THE LEAD
CPI cleared the bar today. Stocks did something more interesting with the room that gave them: instead of lifting broadly, the market drew a hard line between companies that delivered proof this earnings season and companies still asking to be believed.
CoreWeave (CRWV) jumped 19.2% after posting $2.58 billion in revenue against a $2.56 billion estimate, adjusted EBITDA margin of 59% against 55.4% expected, and a $104 billion backlog that doesn’t even count more than $25 billion in fresh Q3 commitments. Super Micro Computer (SMCI) rose 18.8% on a next-year revenue forecast of $65–72 billion versus a $53.1 billion consensus. Nebius Group (NBIS) soared 34.1% on revenue up 454% year over year. Lumentum (LITE) added 13.5% and CAVA Group (CAVA) 14.2%, both beating estimates cleanly. SpaceX (SPCX) extended its run to +9.7%, moving within range of Meta’s market cap on an intraday basis after adding roughly $550 billion in value since August 6th — a five-day rally that started with an options bet, not a headline, and is detailed below in UOA & TOA.
The flip side: Meta (META) fell 3.4%, Microsoft (MSFT) dropped 2.3%, Amazon (AMZN) lost 1.8%, Tesla (TSLA) slid 1.6%, and Apple (AAPL) eased 0.9%. Home Depot (HD) was the S&P’s worst performer, down 3.1%, after CEO Ted Decker announced a medical leave of absence — a company-specific catalyst, not a read on the sector. But the megacap pattern held regardless: the names spending the most on AI capacity without fresh receipts to show for it sat out the party that the names actually delivering infrastructure and revenue got to attend.
Options flow pointed to the SpaceX move early: SpaceX (SPCX) carried a large above-open-interest call buy from Tuesday that was already working by this morning.
Chart Room’s Call
Chris Sykora closed the desk’s SPDR Gold Trust (GLD) September 405 calls today, bought for $7.00 and sold for $13.15, flagging that the daily candle was reading short-term neutral to bearish as gold approached $4,500 intraday before giving back some of the move. It’s a clean example of taking profit into strength rather than fighting a stretched setup.
Wall Street’s Split
Ed Yardeni raised his S&P 500 year-end target to 8,400, citing what he called fabulous earnings momentum and putting recession odds at just 20%. Santander’s Stephen Stanley took the other side, still expecting the Fed to hike in both September and December despite today’s in-line print. Bond traders, per multiple wire reports, are treating the September decision as close to a coin toss.
So What
The setup argues for Positioning Adjustment dressed up as an Earnings Repricing day — flows moved toward proof and away from promises, but the macro backdrop underneath it didn’t actually resolve. With Fed odds still genuinely split and PPI due tomorrow morning, today’s confidence in “risk-on” should be treated as moderate, not high: the next inflation print or a soft CSCO report tonight could just as easily reopen the argument.
THE MARKETS
Technology and Industrials led sector performance; Communication Services and Consumer Cyclical lagged badly, dragged down by Meta (META), Amazon (AMZN), and Tesla (TSLA). Small caps outperformed large caps for the session, with the Russell 2000 beating the Dow by 65 basis points.
THE BUZZ
-
July CPI: headline 333.92 vs. 333.99 expected; core in line at +0.2% m/m
-
EIA crude inventories built by 17.4 million barrels, the biggest weekly jump since January 2023, against a forecast draw of 1.4 million
-
10-Year Note auction tailed, pricing at the highest yield since 2007
-
Trump officials disputed their own agency’s Strait of Hormuz traffic claims; separately, tanker-tracking data contradicted US assertions that Mideast oil flows have normalized
-
Wendy’s (WEN) jumped roughly 13% on a Reuters report that Trian Partners is preparing a take-private bid
-
White House Press Secretary Karoline Leavitt is departing her role at the end of the month, per President Trump
-
Cisco (CSCO) reports fiscal Q4 results after tonight’s close; consensus is $1.17 EPS on $16.82 billion revenue, with hyperscaler AI order guidance (raised to $9 billion) the number to watch
-
OpenAI COO Brad Lightcap announced his departure, the latest in a string of senior exits since January
-
Norway’s $2.3 trillion sovereign wealth fund posted its best quarter since 2020, even as CEO Nicolai Tangen warned the gains “won’t last”
AFTER THE CLOSE:
-
- Beats: ENS +0;83, REZI +0.36, JACK +0.15, COHR +0.12, AOSL +0.11, GO +0.07, CSCO +0.05, HLIT +0.05, CAE +0.03, ENVX +0.02 of note.
Misses: CBRS -2.81, ANDG -0.18, PAAS -0.14, STUB -0.11, BTGO -0.11, STAA -0.06, AVEX -0.06 of note.
Flat: None of note.
- Beats: ENS +0;83, REZI +0.36, JACK +0.15, COHR +0.12, AOSL +0.11, GO +0.07, CSCO +0.05, HLIT +0.05, CAE +0.03, ENVX +0.02 of note.
-
- Winners From After The Close: CURI +22.1%, OMER +20.8%, HLIT +18.8%, TBBB +13.8%, NOA +11.8%, ENS +11.7%, FOSL +10.1%, GO +9.1%, PESI +7%, EQPT +5.5%, JACK +3.8%, ALLO +3.4% of note.
- Losers From Last Week: STUB -14.8%, CBRS -14.7%, AOSL -13%, SPCE -9.4%, KE -8.6%, REZI -6.8%, PAAS -6%, LFTO -5.4%, SPIR -5%, AVEX -4.2%, CSCO -3.9%, COHR -3% -of note.
-
- Chefs’ Warehouse (CHEF) issued notice to redeem all outstanding 2028 convertible senior notes on Oct. 15, 2026.
- Robinhood (HOOD) reported July funded customers of 28.5 mln, up about 80,000 from June, while total platform assets fell 4% month/month to $355 bln.
- Cisco (CSCO) prelim Q4 $1.22 vs $1.17 FactSet Consensus; revs $17.25 bln vs $16.84 bln FactSet Consensus.
- Cerebras (CBRS) misses by $2.81, misses on revs; Issues Q3 and FY26 guidance.
- H.B. Fuller (FUL) confirms unsolicited $1.1 bln-$1.2 bln cash proposal for Building Adhesive Solutions unit.
- HLIT delays 10-Q.
-
- CTRI names Kelly Youngblood CFO, Danielle Hunter chief legal and administrative officer.
- FRMI names Lee McIntire as Chief Executive Officer.
-
- MHO authorizes new $250 mln share repurchase program.
- BTGO authorizes $50 mln buyback program.
- CRS authorizes new $1.0 bln share repurchase program.
UOA & TOA
SpaceX (SPCX) — Bullish Call Buying (8/11)
6,000 October 16 $180 calls bought in one order for $5.80–5.85, above open interest of 2,908 contracts, with the stock at $135.03–135.17.
Why it matters: The above-OI call buying preceded the stock’s sharp move higher — it closed above $148 today, and the desk rolled the same position twice intraday, moving 14AUG$140C to $146C for a 57% gain, then $146C to $150C for another 31%.
SPDR Gold Trust (GLD) — Bullish Call Roll, Multiple Sessions (8/5–8/12)
Repeated large call spreads and rolls accumulated through the week, capped by 55,292-contract rolls on both 8/6 and 8/12.
Desk action: The position was closed today for a profit as gold approached $4,500 and the daily candle turned neutral-to-bearish.
Our read: The sequence traced a full round trip from accumulation to distribution inside a single week.
Oracle (ORCL) — Bearish Put Buying (8/11)
12,070 September 25 $105 puts bought in one print for $1.33, against open interest of just 21 contracts — essentially a brand-new position.
Risk: Oracle stock still rose 5.4% today, so this hedge hasn’t been vindicated yet — but it lines up with broader credit-market skepticism toward AI-capex-heavy balance sheets, detailed further below.
Micron (MU) — Desk Activity (not a dated UOA print)
Clark Zahn rolled a 12AUG $920 call to 14AUG $940 for a 55% gain, then closed it for a small loss shortly after.
What we’re watching: MU rose nearly 5% today on renewed memory-shortage tailwinds; the quick round trip suggests the desk is trading the volatility rather than holding for a longer memory-cycle thesis.
Most active options: NVDA, TSLA, SPCX, MU, PLTR, META, AAPL, INTC, AMZN, GOOGL, MSFT, ORCL
Rising volume to watch: SPCX, MU, PLTR, INTC, ORCL, MSTR, NFLX, RKLB, SMCI
TOP TICKERS
CoreWeave (CRWV), Super Micro Computer (SMCI), Nebius Group (NBIS), SpaceX (SPCX), Lumentum (LITE), CAVA Group (CAVA), Oracle (ORCL), Wendy’s (WEN), Micron (MU), Home Depot (HD)
THE REAL STORY
Stocks partied on the CPI print. Bonds and credit barely showed up.
The 10-Year Note auction tailed today, pricing at the highest yield since 2007 — a soft outcome that doesn’t square with a market convinced the inflation fight is basically won. Bond traders are treating the September Fed decision as close to a literal coin toss, and JPMorgan’s own asset-management strategist argued the Fed should hold rates unchanged specifically because a wage-price spiral hasn’t taken root — a defensive case, not a confident one. Oracle’s (ORCL) credit default swaps have stayed elevated even as the stock rallied 5.4% today, and a wave of desk-level commentary this week has framed rising doubts over AI-capex payback as a genuine credit-market concern, not just an equity-market debate.
Even gold complicated the picture: it pushed toward $4,500 intraday for the first time since June, then gave back some of the move as the desk closed its long — a reminder that the safe-haven signal was not entirely consistent with the calm implied by equities.
None of this contradicts today’s Earnings Repricing — CoreWeave, Super Micro, and Nebius genuinely delivered numbers that justified their moves. But it does mean the “everything’s fine now” read on the CPI print is running well ahead of what rates and credit markets are actually pricing. Earnings growth this strong is, on its own, becoming a reason for caution: a market pricing in flawless execution has less room to absorb any single disappointment.
Playbook
-
Watch: Tomorrow’s PPI print and how the 10-Year trades in its wake
-
Confirm: A move back below 4.60% on the 10-Year would support today’s equity optimism as durable rather than borrowed
-
Failure: A second consecutive tailed Treasury auction or a soft Cisco (CSCO) guide tonight would suggest credit markets were right to stay skeptical
QUESTIONS FROM THE ROWDY REBELS
Q: With CPI out of the way, what is the market waiting for now? — John V.
A (Robert Deconcini): The PPI report tomorrow morning.
Q: What’s the best way to play GLD to establish a new position? — Dennis M.
A (Chris Sykora): You want to be longer-term from here…
Q: Do we have a position in Bristol-Myers Squibb? — Jon R.
A (Chris Sykora): No BMY position in the portfolio.
Q: Are we hosting an On The Horn call today? I’m only getting the previous session’s replay. — Richard N.
A (John Ferro): No On The Horn call today, but there is a Zoom Webinar at 5:30 ET.
WATCHLIST
Proof vs. Promises Rotation — Bull: If Cisco (CSCO) delivers a clean beat-and-raise tonight and PPI cooperates tomorrow, the market has room to keep funding AI infrastructure names with real backlogs while company-specific weakness like Home Depot’s stays contained. Bear: If tomorrow’s inflation data disappoints, today’s sector split could reverse entirely, since the rally leaned on a single friendly data point rather than a broad repricing of risk.
Rates/Credit Skepticism — Bull: A cooler PPI print would validate the “gradual disinflation without hikes” case and pull the 10-Year lower, giving equities a real tailwind instead of a borrowed one. Bear: Another soft Treasury auction could catch equity bulls leaning the wrong way, especially where the stock and the credit market are already telling different stories.
The market paid for delivered goods today, not chip-shortage-flavored promises — whether that discipline survives contact with tomorrow’s PPI print is the actual test.
YOUTUBE
https://youtu.be/WK5agHIRpd4?si=V25gk-TalirE0Lgl