Newsletters
Rebel Roundup Newsletter For 8/18: Chip Stocks Crack, Best Offense is a Good Defense and S&P 500 Down For Third Day In a Row.
By Geoff Garbacz | Market Rebellion · August 18, 2026
Semis Give Back Yesterday’s Gains as NASDAQ Composite Falls 1.33%
TODAY, WRAPPED:
The day’s dominant market belief: yesterday’s chip strength was borrowed, not earned. The S&P 500 fell 0.69% to 7,691.76, the NASDAQ Composite dropped 1.33% to 26,289.7, the NASDAQ 100 lost 1.68% to 29,490.96, and the Dow shed a comparatively modest 0.22%. It was the third straight losing session for the S&P 500.
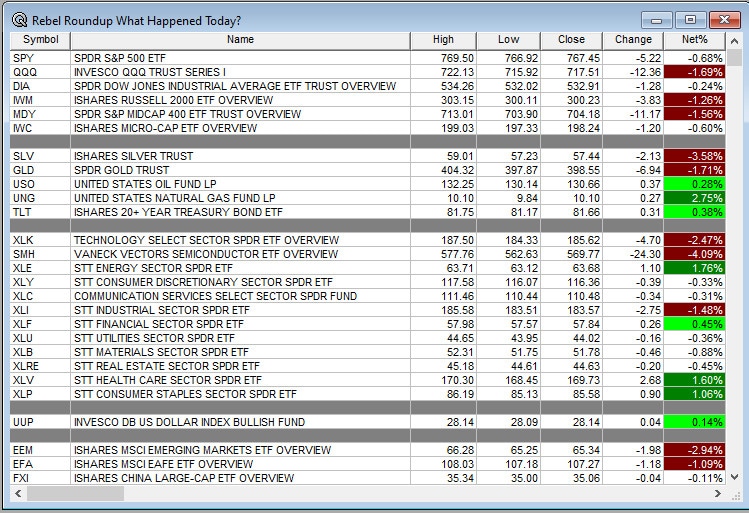
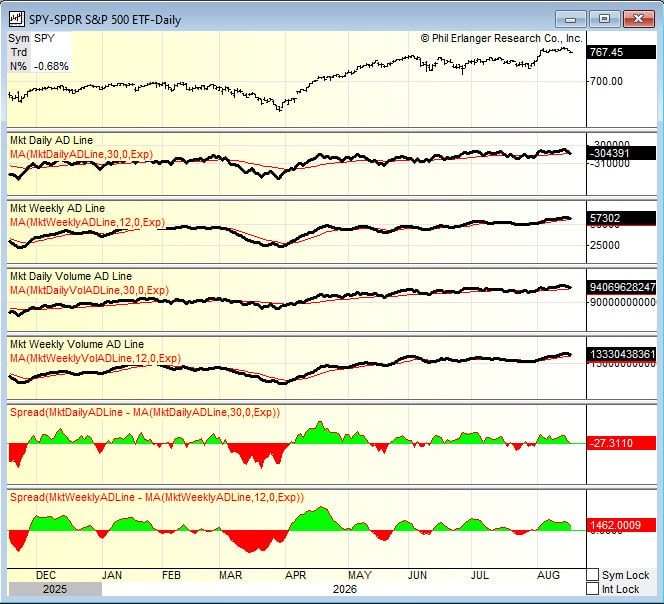
Semiconductors led the damage — Micron (MU) -6.98%, Marvell (MRVL) -7.81%, Intel (INTC) -6.58% — while healthcare, energy, and staples were the only sectors that finished green. Breadth was ugly: decliners outpaced advancers nearly 3-to-2, and new 52-week lows outnumbered new highs. That’s the story.
THE LEAD
Futures had already flagged the damage before the bell — S&P E-minis down 33 points, NASDAQ 100 futures off nearly 400. The session didn’t recover from that start; if anything, tech and semis extended the premarket damage into the close.
Yesterday’s chip rally didn’t survive contact with today’s bond market. Monday’s session had shown the PHLX Semiconductor Index up 1.6% even as the broader tape sagged — a signal that AI hardware could shrug off rising yields. It couldn’t. By today’s close, Micron (MU), Marvell (MRVL), Broadcom (AVGO), and Advanced Micro Devices (AMD) had all given back that resilience and then some, dragging the NASDAQ Composite to its worst close in three weeks (see numbers above).
The trigger was the same one that’s been building all week: a global bond selloff that pushed 30-year Treasury yields to a fresh 2007 high near 5.32% in early trading, while WTI crude firmed to $85.12, extending Monday’s advance as the U.S.-Iran ceasefire lapsed without renewal. Higher discount rates hit long-duration AI trades hardest, and Middle East risk kept a bid under crude. That’s the textbook explanation — and it’s only half the story.
By the close, the 10-year yield had actually eased to 4.71%, down slightly on the day, and long bonds firmed (TLT +0.38%). Tech didn’t recover with them. That divergence matters: it suggests today’s chip selling had built its own momentum by the afternoon, separate from the rates story that started it — a subtlety worth remembering the next time a headline blames “rising yields” for a stock move that outlasts the yields themselves.
Elsewhere, the fundamentals were mixed. Home Depot (HD) beat cleanly before the open — adjusted EPS $4.92 vs. $4.73 expected, revenue $47.86B vs. $47.27B expected, full-year guidance reaffirmed — though shares barely moved as “frozen housing market” caution capped the reaction. Klarna (KLAR) was the ugliest tape of the day: shares crashed 22.8% after the company cut Q3 revenue guidance to $940–980M against a $1.11B estimate and announced a CFO search.
Smart Money had this positioned early: unusual options flow flagged a bearish put spread on the VanEck Semiconductor ETF (SMH) and a bearish put roll on the Direxion Daily 20+ Year Treasury Bull 3X Shares (TMF) — more on both in UOA & TOA below.
History offers an imperfect parallel. Per MarketWatch, the S&P 500 is now on its strongest six-year stretch since the run that began in 1994, well above its 11.3% historical CAGR — though this time AI infrastructure spend is showing up in actual revenue rather than pure multiple expansion. Confidence here is moderate: the analogy explains the setup, not the timing.
Geoff’s Take: This morning’s NVDA put reco worked — sold at Geoff’s signal around 9:38 a.m. after a tense run into expiration, with Rebels reporting gains from the mid-30s to over 90% (full exchange below). He flagged a fresh put on Carvana (CVNA) late in the session, unrelated to the tech selloff: the trade is tied to renewed DOJ scrutiny of Mark Walter’s private-credit empire. He covered it on today’s Rebel Roundup Pro Weekly Webinar which is worth the money.
BofA’s take cuts the other way on one name: the bank argues Nvidia (NVDA) could be trading at a 34–50% discount to fair value even accounting for AI risk, reiterating Buy with a $350 target against a stock near $220 — Narrative-level, but a useful counterweight to today’s chip pessimism.
So what: the regime today wasn’t a clean “yields up, tech down” story — it started that way and finished as something closer to a positioning unwind that yields alone can’t explain. Watch whether semis stabilize before Thursday’s Philly Fed read and Friday’s PMIs, or whether the crowded long-semiconductors trade keeps unwinding on its own inertia — more on that below.
THE MARKETS
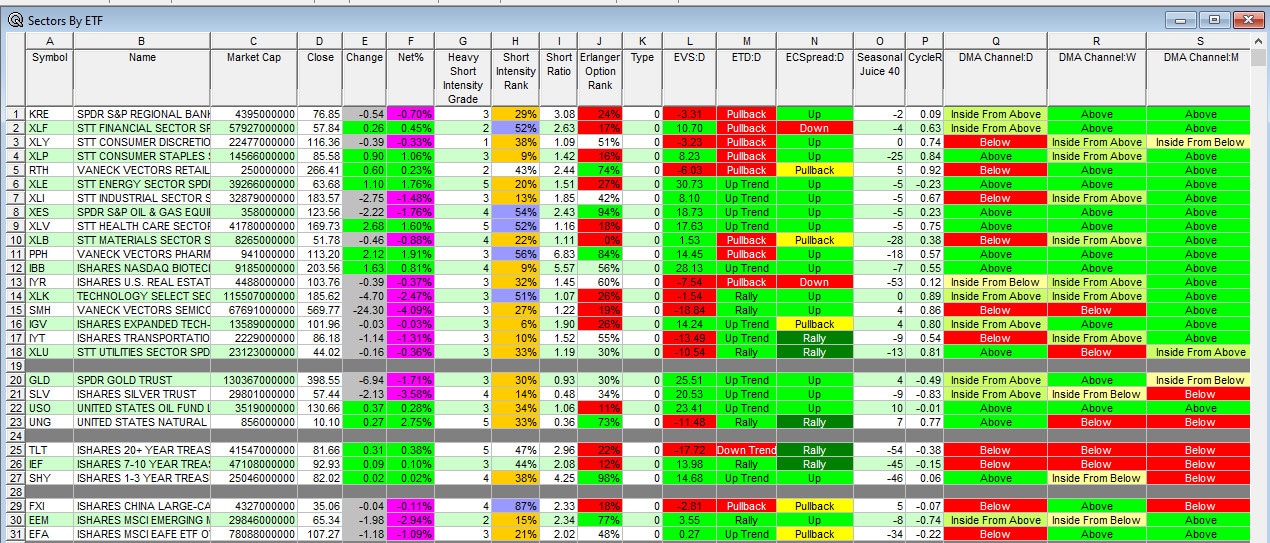
Sector leadership flipped defensive: Energy Select Sector SPDR (XLE) +1.76%, Health Care Select Sector SPDR (XLV) +1.60%, and Consumer Staples Select Sector SPDR (XLP) +1.06% were the only meaningful gainers, while Technology Select Sector SPDR (XLK) dropped 2.47% and Industrial Select Sector SPDR (XLI) fell 1.48%. On the week, Energy is now up 3.18%, the best-performing sector by a wide margin.
AFTER THE CLOSE:
Earnings After The Close:
-
- Beats: KEYS +0.29, JKHY +0.10, TOL +0.04 of note.
- Misses: LZB -0.06, MRCY -0.01 of note.
- Flat: None of note.
Movers after the close yesterday:
-
- Winners: KEYS +2.7%, CCC +2.2%, CW +2.1% of note.
- Losers: WYFI -20.5%, LZB -16.3%, EPM -11.2%, MRCY -10.5%, AUNA -9%, BLZE -7.8%, FRNM -4.1% of note.
News after the close::
-
- Spider-Man: Brand New Day swings to highest grossing domestic film of all time for Cinemark (CNK).
- Infleqtion (INFQ) to test quantum sensing in Colorado to advance U.S critical minerals security.
- American Airlines (AAL) to bring back TV screens on flights. (BBC News)
- INFQ FIRY delays 10-Q.
Executive, Corporate Changes:
-
- SWIM names Todd Antonelli chief commercial officer.
Buybacks of Note:
-
- CW expands 2026 share repurchase program by $100 mln.
Dividend Changes & Ex-Dividend Stocks:
-
- Stocks Going Ex-Dividend Tuesday: .
- Stocks Going Ex-Dividend Wednesday of note.
- TRST increases quarterly dividend to $0.40/share from $0.38/share.
THE BUZZ
-
Meta Platforms (META) dropped 4.42% as opening arguments began in a multistate trial alleging the company designed Facebook and Instagram to hook younger users
-
Apple (AAPL) rose 1.52%, bucking the Mag 7 slide, after finalizing its revamped EU App Store terms (effective October 1) to resolve an antitrust dispute
-
Baidu (BIDU) fell 12.96% on its fifth quarter of free cash outflow in the last six, as AI capex outpaced revenue
-
Amazon (AMZN) is expanding its Louisiana data center investment from $12B to $18B with a third campus, plus up to $400M for local water infrastructure
-
Nvidia (NVDA) confirmed it will back SoftBank’s 4.25GW Ohio data center for $105B — down from the originally floated $250B commitment
-
Anthropic is reportedly asking lead banks for roughly $1.25B each toward a pre-IPO credit facility set to top $10B, with its annualized revenue run rate reportedly reaching $65B in July, as odds shift in its favor to beat SpaceX as 2026’s largest IPO
-
KKR made a roughly $9B takeover bid for gas and electricity distributor UGI (UGI)
-
OpenAI launched a restricted “ChatGPT for Teens” with added safety guardrails
UOA & TOA
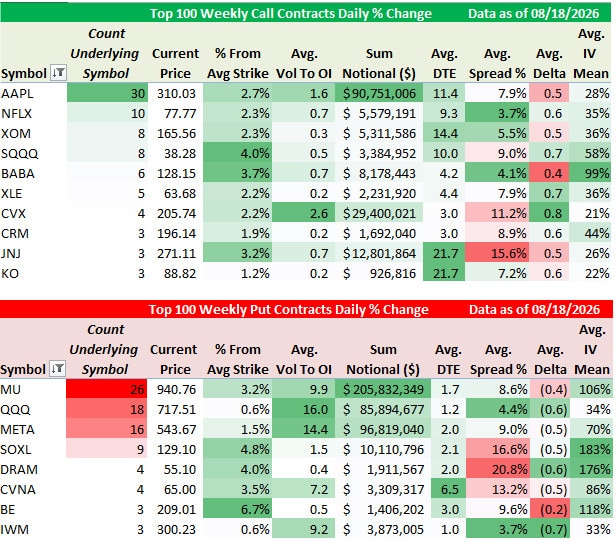
Chevron (CVX) — Bullish Call Roll (8/18)
10,000 August 21 215 calls bought for 0.09 above open interest of 1,176 contracts; 10,000 August 21 205 calls sold for 1.64 below open interest of 29,377 contracts. Stock 205.64.
10,000 August 21 215 calls bought for 0.09 above open interest of 1,176 contracts; 10,000 August 21 205 calls sold for 1.64 below open interest of 29,377 contracts. Stock 205.64.
Why it matters: This is a strike-up roll into fresh calls just above the money — a bet CVX has more room after today’s 1.50% gain, not a profit-take. Energy’s outperformance today (XOM +2.54%, CVX +1.50%) validates the positioning.
VanEck Semiconductor ETF (SMH) — Bearish Put Spread (8/18)
22,109 September 4 545 puts bought for 10.75 above open interest of 70 contracts; 22,109 September 4 515 puts sold for 4.25 above open interest of 68 contracts. Stock 568.75.
22,109 September 4 545 puts bought for 10.75 above open interest of 70 contracts; 22,109 September 4 515 puts sold for 4.25 above open interest of 68 contracts. Stock 568.75.
Our read: This flow printed roughly four hours before the semiconductor rout accelerated into the close. Whoever put this on saw today’s chip weakness coming.
Direxion Daily 20+ Year Treasury Bull 3X Shares (TMF) — Bearish Put Roll (8/18)
8,500 September 18 31 puts bought for 1.81–1.90 above open interest of 213 contracts; 4,250 August 21 33 puts sold for 3.40–3.23 below open interest of 6,459 contracts. Stock 29.65–29.72.
8,500 September 18 31 puts bought for 1.81–1.90 above open interest of 213 contracts; 4,250 August 21 33 puts sold for 3.40–3.23 below open interest of 6,459 contracts. Stock 29.65–29.72.
Risk: TMF is a levered long-bond bull fund, so a bearish put position here is a bet that long bonds keep falling — i.e., that long yields keep climbing. That bet looked good pre-market and considerably less so once the 10-year eased into the close. Worth watching whether this position gets unwound.
CSX Corp (CSX) — Bullish Call Spread and Bearish Combo, same session (8/18)
Bullish: 10,000 September 18 52.50 calls bought for 0.50 above open interest of 5,020 contracts, with 55 calls sold against them. Bearish: 10,038 August 28 49 puts bought for 0.55 above open interest of 28 contracts, with 52 calls sold against them.
Bullish: 10,000 September 18 52.50 calls bought for 0.50 above open interest of 5,020 contracts, with 55 calls sold against them. Bearish: 10,038 August 28 49 puts bought for 0.55 above open interest of 28 contracts, with 52 calls sold against them.
What we’re watching: Conflicting directional bets on the same name in the same session — a rare split that suggests the desk putting on rail exposure genuinely doesn’t have conviction on direction here.
Most active options: NVDA, TSLA, MU, SPCX, AAPL, AMZN, MSFT, META, INTC, AMD, SNDK, IREN, GOOGL, PLTR, AVGO
Rising volume to watch: MU, SPCX, INTC, AMD, SNDK, IREN, PLTR, AVGO, SOFI, NKE, MSTR, NBIS, ORCL
TOP TICKERS
Micron (MU), Marvell (MRVL), Klarna (KLAR), Baidu (BIDU), Meta Platforms (META), Sandisk (SNDK), Nvidia (NVDA), Home Depot (HD), Carvana (CVNA), Intel (INTC)
THE REAL STORY
THE LEAD’s tension was rates versus tech. The tension underneath that is positioning versus conviction — and it’s not resolving cleanly.
BofA’s August fund manager survey, out today, shows a net 56% of managers overweight equities — the highest since November 2021 — with cash allocations down to just 3.5%. That’s about as bullish as institutional positioning gets. And yet the same respondents name an AI bubble as the single biggest tail risk (32%), with a disorderly bond-yield surge close behind (27%). “Long global semiconductors” remains the survey’s most crowded trade, but the share naming it has cooled to 53% of respondents from 82% the prior month — which lines up almost exactly with today’s chip rout. Deutsche Bank separately notes short interest across U.S. stocks has climbed to its highest since the financial crisis. Crowded long, crowded short, at the same time: that’s not conviction, that’s a market hedging its own bullishness.
The credit side of that hedge showed up in individual names today. Evercore founder Roger Altman flagged widening investment-grade spreads — a small move, but from someone whose business is reading distress early. Nvidia’s (NVDA) Ohio data center commitment, confirmed today, came in well below the figure floated earlier this year (see THE BUZZ). And Mark Walter’s Delaware Life is reported Carvana (CVNA) cutting affiliated private-credit investments by up to $6.5B amid DOJ scrutiny — the same overhang weighing on amid concerns he may need to sell down his stake. Geoff put on a fresh CVNA put position late today. None of this amounts to a cut in AI capex. But it’s evidence that the financing plumbing behind the AI trade is getting more scrutiny, not less, even as equity positioning stays maximally bullish.
Watch: Whether IG credit spreads keep widening into Jackson Hole (Aug 27–29) — that’s a cleaner tell than equity price action.
Confirm: A second data point on AI-adjacent private credit tightening (beyond Walter/CVNA) would turn this from anecdote to pattern.
Failure: If NVDA’s Aug. 26 earnings beat cleanly and semis stabilize by then, this positioning-tension story loses its teeth fast — crowded-but-bullish surveys don’t matter if the underlying earnings keep delivering.
Confirm: A second data point on AI-adjacent private credit tightening (beyond Walter/CVNA) would turn this from anecdote to pattern.
Failure: If NVDA’s Aug. 26 earnings beat cleanly and semis stabilize by then, this positioning-tension story loses its teeth fast — crowded-but-bullish surveys don’t matter if the underlying earnings keep delivering.
QUESTIONS FROM THE ROWDY REBELS
Q: Should we be taking profits on the NVDA puts at the open, or waiting for your call? — Stuart D.
A (Geoff Garbacz): I’m working through that right now on NVDA. [Followed shortly after by:] Sell the NVDA put. The reco has been published. This was a tough trade running into a Mid Week (8/19) expiration, but it worked out. We talked about it on today’s webinar and said it was not our best timing trade but happy with the 24% gain.
WATCHLIST
Semiconductors / AI Positioning
Bull: Today’s rout follows a Monday session where chips outperformed — if that resilience reasserts itself and the 10-year stays capped near 4.70%, this reads as a shakeout of the crowded-long trade rather than a trend change, and NVDA’s Aug. 26 print becomes the tell.
Bear: The crowded-long-semis unwind (82% to 53% per BofA) has room to keep running even without new bad news, and a fresh leg up in yields — 30-year briefly touched 5.32% today — would reopen the valuation pressure on AI infrastructure names.
Bull: Today’s rout follows a Monday session where chips outperformed — if that resilience reasserts itself and the 10-year stays capped near 4.70%, this reads as a shakeout of the crowded-long trade rather than a trend change, and NVDA’s Aug. 26 print becomes the tell.
Bear: The crowded-long-semis unwind (82% to 53% per BofA) has room to keep running even without new bad news, and a fresh leg up in yields — 30-year briefly touched 5.32% today — would reopen the valuation pressure on AI infrastructure names.
Defensive Rotation (Energy / Healthcare / Staples)
Bull: Energy’s +3.18% week and healthcare’s break to fresh highs across names like Eli Lilly (LLY) and Merck (MRK) suggest real money is rotating, not just hedging — a trend with legs if oil stays elevated on Hormuz risk.
Bear: Defensive outperformance this concentrated in three sectors often marks capitulation in growth rather than a durable leadership change — watch whether it survives a single strong tech session.
Bull: Energy’s +3.18% week and healthcare’s break to fresh highs across names like Eli Lilly (LLY) and Merck (MRK) suggest real money is rotating, not just hedging — a trend with legs if oil stays elevated on Hormuz risk.
Bear: Defensive outperformance this concentrated in three sectors often marks capitulation in growth rather than a durable leadership change — watch whether it survives a single strong tech session.
Three days of losses and a chip rout that outlasted its own trigger — the rotation into energy and healthcare looks less like a rebalance and more like a market still deciding what it actually believes. Amazingly, the A/D lines did not turn down on Tuesday’s action.
Rebel’s Edge on Your Tube