
Newsletters
Rebel Roundup Newsletter For August 17th: Stocks Take a Breather But Finish The Week Higher For A Third Week In A Row on the S&P 500
By Geoff Garbacz | Market Rebellion · August 16, 2026
Top Takeaway: Retail Sales Sank 0.6% in July and Consumer Sentiment Hit 51.0 Both Lower Than Expectations So the Rally Finally Paused
TODAY, WRAPPED:
The day’s dominant market belief cracked, if only slightly: the S&P 500 closed at 7,785.76 (-13.23, -0.17%), the NASDAQ Composite fell to 26,729.16 (-73.87, -0.28%), and the Dow slid to 53,732.4 (-107.58, -0.20%) — all pulling back from Thursday’s record close above 7,800. The Russell 2000, notably, did not get the memo: it rose 0.51% to 3,068.42, a fourth straight advance.
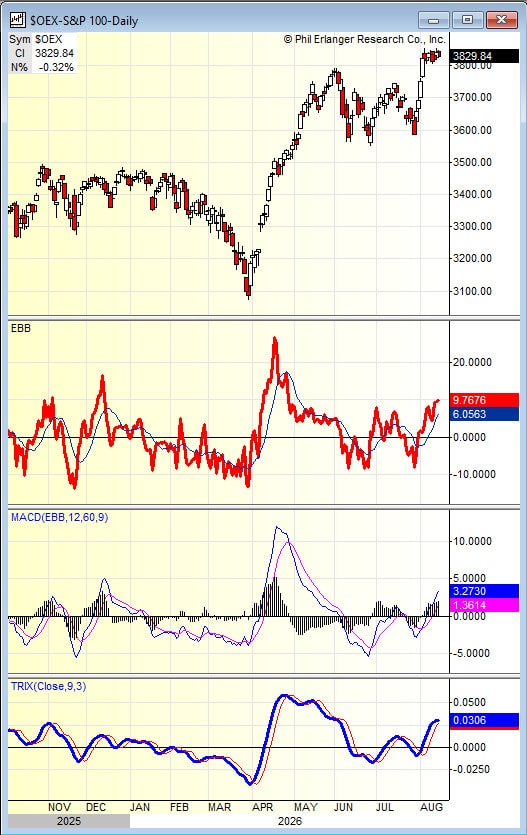
July retail sales fell 0.6% month-over-month, the steepest drop in over a year, badly missing the 0.1% consensus. The control group — the input that feeds GDP — fell 0.4% against an expected 0.3% gain. Minutes later, the University of Michigan’s preliminary August sentiment reading came in at 51.0, down from 55.2 and missing expectations of 54.5 — one of the lowest readings on record. Breadth held up reasonably well (advancers still edged decliners, 50.1% to 44.8%), and the Fear & Greed Index eased only modestly, from 66 to 65 — still firmly in Greed territory. Meanwhile the Erlanger Big Barf Daily rose to a new high. That’s the story: this wasn’t a rout, but it was not pretty.
THE LEAD
Opening
The market spent Thursday celebrating disinflation. It spent Friday finding out what disinflation might be costing the consumer. As detailed above, the twin misses on retail sales and consumer sentiment did just enough to halt a rally that had carried the S&P 500 (SPX) through 7,800 for the first time a day earlier — but not nearly enough to break it. That distinction matters more than the headline red print.
Why?
The week’s entire arc has been about the Federal Reserve’s rate path. Wednesday’s CPI and Thursday’s PPI both came in soft enough to push the probability of a September hike down toward the mid-30s from north of 50% a week ago, and that dovish repricing is what carried indexes to records. Friday’s data extended the same logic — weaker consumer spending is one more argument against tightening — but it also introduced a second, less comfortable read: a broader worry that the American shopper, not just the Fed, might be pulling back. Treasuries did rally briefly on the retail miss and the dollar slid to a two-month low, but by the close, the move had partly reversed — a wrinkle explored fully below. Sector rotation told the real story of the day: Energy Select Sector SPDR (XLE) led with a 1.39% gain (energy is now up 5.56% for the week, the best sector by a wide margin), while Technology Select Sector SPDR (XLK) and Healthcare Select Sector SPDR (XLV) brought up the rear, down 0.40% and 0.60% respectively. Chips split hard:
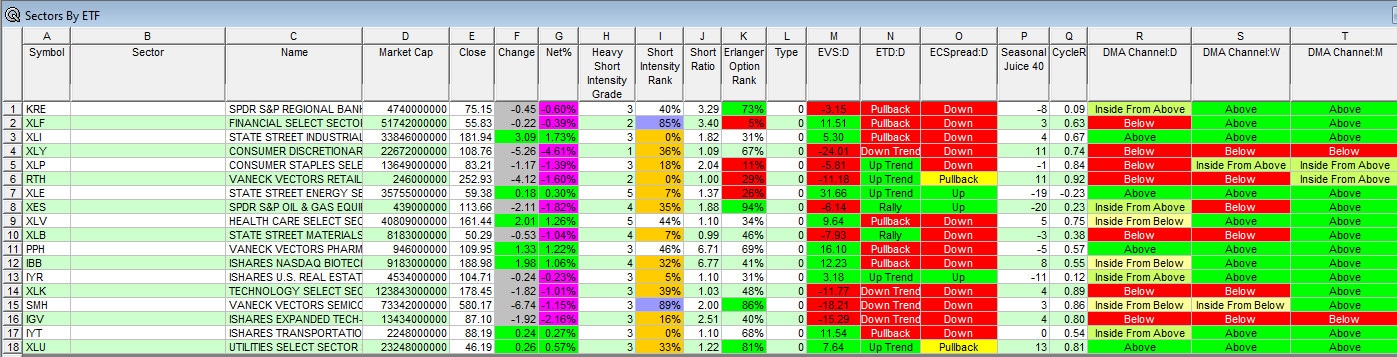
Broadcom (AVGO) fell 5.93% and Applied Materials (AMAT) dropped 5.12% even after beating estimates Thursday night, while Sandisk (SNDK) extended its investor-day breakout with a 7.39% gain and Advanced Micro Devices (AMD) rose 6.50%.
Smart Money Early Signal
Options flow had been building a bond/inflation hedge for days before this print landed — gold call buying showed up repeatedly across the past week in size, well above open interest each time. Full detail in UOA & TOA below.
History
The closest recent analogue is August 2024’s Sahm Rule scare, when a soft jobs print hit a market sitting near highs with historically low volatility and triggered an outsized, VIX-spiking reaction. Today’s move rhymes with that setup — soft data, summer positioning, a market that had gotten used to good news — but the magnitude is nothing alike. VIX actually fell today, to 14.23, and the S&P gave back just 0.17%. If 2024 was a jolt, this was a shrug, which itself says something about how much cushion this rally is currently carrying.
Geoff’s Take
In today’s session, Geoff Garbacz reiterated conviction on the Market Rebellion NVDA put position through the afternoon: “Good entry point here still on NVDA,” he told the room around 1:10 PM, and again near the close: “I am still good with the NVDA trade.” Guess what happened early into the weekend? Nvidia lowered its investment for a data center in Ohio from $250 million to less than $120. We will find out on Monday if this is the “Rut Ro, Shaggy Moment.”
So What / Looking Ahead
The data argue two directions at once: soft enough to keep the Fed on hold, weak enough to question whether the consumer can keep carrying a market pricing near-perfect execution. With confidence still only medium on which force wins out, next week’s retail earnings — Target (TGT), Walmart (WMT) — become the actual test, not today’s print.
THE MARKETS
Energy (XLE, +1.39%) and Utilities (XLU, +0.61%) led sector performance while Healthcare (XLV, -0.60%) and Technology (XLK, -0.40%) lagged; on the week, Energy’s 5.56% gain dwarfs every other sector, with Consumer Cyclical the week’s weakest at -1.65%.
AFTER THE CLOSE
Earnings After The Close:
-
- Beats: None of note.
- Misses: None of note.
- Flat: None of note.
Movers After The Close:
-
- Winners From Last Week: OMER (17.26 +30.26%), ASMB (32.40 +21.44%), EVH (4.73 +19.62%), ATRO (93.83 +20.68%), HZO (52.11 +46.05%), RRGB (10.25 +25%), PSTG (116.99 +29.91%), STX (962.83 +18.46%), CAMP (5.01 +18.16%), PARR (80.36 +21.22%), HP (44.26 +19.3%), MPC (354.48 +18.87%) of note.
- Losers From Last Week: TCMD (24.07 -18.41%), REZI (20.36 -21.93%), ACM (62.59 -17.47%), HUBG (40.2 -15.9%), TPR (129.49 -20.25%), EYE (19.16 -15.06%), GRPN (21.3 -14.9%), CEVA (32.85 -15.05%), COHR (325.4 -14.17%), of note.
News after the close:
-
- Lots of 13-F Filings out after the close from Hedge Fun.
- Nvidia (NVDA) take a position in SPCX 122 million shares.
- Nvidia (NVDA) cuts investment in OpenAI to $11o from proposed $250 million.
- Diana Shipping (DSX) withdraws bid for Genco after board demanded higher terms.
- HLIT delays 10-Q.
Executive, Corporate Changes:
Buybacks of Note:
-
- . XZO authorizes $25 mln stock repurchase program.
Dividend Changes & Ex-Dividend Stocks:
- Stocks Going Ex-Dividend Monday .
- Stocks Going Ex-Dividend Tuesday – None of note.
- BMI increases quarterly cash dividend to $0.44/share from $0.40/share.
THE BUZZ
-
Goldman Sachs (GS) is expanding its financing arm to fund the AI infrastructure buildout — the latest sign Wall Street is treating data-center capex as a durable credit business, not a one-off boom.
-
Workday (WDAY)‘s reported buyout talks with Silver Lake are being read by analysts as a potential confidence restorer for battered enterprise software valuations broadly.
-
Reddit (RDDT) surged 12.63% ahead of Monday’s formal S&P 500 index inclusion.
-
Global and U.S. equity funds extended their inflow streak this week as reduced rate-hike odds and earnings optimism drew fresh money in, even before today’s soft data hit.
UOA & TOA
Gold SPDR (GLD) — Bullish Call Buying/Rolling (multiple sessions, 8/10–8/12)
Across four separate sessions this week, large call spreads and rolls built up in GLD well above resident open interest — including a 110,581-contract spread on 8/10 alone.
Across four separate sessions this week, large call spreads and rolls built up in GLD well above resident open interest — including a 110,581-contract spread on 8/10 alone.
Why it matters: This positioning predates today’s dollar weakness and yield confusion by several days. Institutional flow was leaning into a fiscal/inflation hedge before the retail data gave the rest of the market a reason to.
NVIDIA (NVDA) — Bullish Call Spread Roll (8/13)
23,250 contracts of the September 4 240/270 call spread were bought, rolled up from a smaller September 18 225/270 position. The September 4 expiration carries the position through NVDA’s August 26 earnings report.
23,250 contracts of the September 4 240/270 call spread were bought, rolled up from a smaller September 18 225/270 position. The September 4 expiration carries the position through NVDA’s August 26 earnings report.
Our read: This bullish call structure sits on a different time horizon and thesis than Geoff Garbacz‘s shorter-term put position discussed above — the two shouldn’t be read as pointing the same direction. Conflicting-looking NVDA flow across strikes and expirations can be common ahead of a name’s earnings date, not necessarily a sign of conflicting views on the desk. Just the possibility of a dip before a breakout and now with the Nvidia weekend news even more so.
Energy Select Sector SPDR (XLE) — Bullish Call Roll (8/14)
10,000 August 28 62-strike calls bought, rolled from a smaller August 21 59.50 position, tracking directly with the sector’s leadership this week.
10,000 August 28 62-strike calls bought, rolled from a smaller August 21 59.50 position, tracking directly with the sector’s leadership this week.
What we’re watching: Whether energy’s outperformance is a geopolitical premium play on Iran or a genuine rotation out of crowded AI names — Friday’s flow leaned toward the former given the tight expiration.
Workday (WDAY) — Bearish Put Spread (8/14)
4,000 August 28 175 puts bought against 2,000 August 28 165 puts sold, placed the same morning buyout chatter was lifting the stock.
4,000 August 28 175 puts bought against 2,000 August 28 165 puts sold, placed the same morning buyout chatter was lifting the stock.
Risk: Read as a hedge against the Silver Lake deal falling through or pricing below where shares are currently trading, not a directional bear bet.
McDonald’s (MCD) — Bearish Put Buying (8/14)
Put buying in the September 18 270 strike appeared the same morning retail sales data missed badly.
Put buying in the September 18 270 strike appeared the same morning retail sales data missed badly.
Why it matters: A direct options-market echo of today’s consumer-spending concern, landing in a name whose traffic is a real-time read on discretionary spending.
Most active options: NVDA, TSLA, SPCX, MU, SMCI, INTC, AAPL, IREN, AMZN, NFLX, HTZ, MSTR, NBIS, PLTR, SNDK
TOP TICKERS
Sandisk (SNDK) · Reddit (RDDT) · Advanced Micro Devices (AMD) · Broadcom (AVGO) · Applied Materials (AMAT) · Micron (MU) · General Electric (GE) · Chevron (CVX) · Exxon Mobil (XOM) · Eli Lilly (LLY)
THE REAL STORY
The Lead’s dovish read — soft data, Fed on hold — gets complicated by the bond market itself. If Friday’s retail sales miss were purely dovish news, the 10-year yield should have fallen. Instead, after an initial dip, yields reversed and finished the day higher, in the 4.65%–4.70% range, extending a week that also saw a 30-year auction yield at 5.216% — the highest yield at a 30-year sale since 2001 — and the 2s10s spread widened to 53 basis points, its widest in roughly five months.
That’s not the yield curve pricing “weak growth, Fed cuts.” It’s the long end pricing a persistent fiscal and inflation risk premium that doesn’t care what the retail sales print said. The Dallas Fed’s own alternate trimmed-mean inflation gauge — a more symmetric measure than the Fed’s standard version — put trimmed mean PCE inflation at 2.6% over the year through June, meaningfully above the 2.2% the standard gauge shows, suggesting some of the “good” inflation news investors have been trading on may be statistical noise sitting on top of a stickier trend.
Playbook:
-
Watch: Whether 10-year yields hold above 4.75% into next week even as growth data softens further — that combination would confirm the term-premium story over the soft-landing one.
-
Confirm: A weak Michigan report combined with steady-to-higher long yields two data points in a row would validate the fiscal-risk reading.
-
Failure: A sharp yield decline on the next data point would suggest today’s reversal was noise, not signal, and the disinflation thesis remains intact.
QUESTIONS FROM THE ROWDY REBELS
Q: I wasn’t able to get into the NVDA put when you first issued it — should I place the trade now, or wait for the next idea? — Steven S.
A (Geoff Garbacz): Good entry point here still on NVDA on near term puts.
Q: I added to the NVDA put earlier so my average cost is now even — sounds like I should hold? — Donna R.
A (Geoff Garbacz): I am still good with the NVDA trade.
WATCHLIST
Soft Landing vs. Consumer Crack
Bull: Two soft prints don’t make a trend — retail sales are volatile month to month, and a Fed on hold with cooling inflation is still the friendliest setup equities have seen all year.
Bear: Next week’s Target and Walmart earnings will show whether this was a one-month wobble or the start of a pattern — the market has about five trading days to find out before it has to guess.
Bull: Two soft prints don’t make a trend — retail sales are volatile month to month, and a Fed on hold with cooling inflation is still the friendliest setup equities have seen all year.
Bear: Next week’s Target and Walmart earnings will show whether this was a one-month wobble or the start of a pattern — the market has about five trading days to find out before it has to guess.
The Bond Market’s Dissent
Bull: A 5-month-wide 2s10s spread simply reflects a healthy, normalizing curve after years of inversion — nothing more sinister than that.
Bear: A 30-year auction pricing at the highest yield since 2001, on the same day weak growth data should have pulled yields lower, is the bond market telling equities something the stock market isn’t ready to hear yet.
Bull: A 5-month-wide 2s10s spread simply reflects a healthy, normalizing curve after years of inversion — nothing more sinister than that.
Bear: A 30-year auction pricing at the highest yield since 2001, on the same day weak growth data should have pulled yields lower, is the bond market telling equities something the stock market isn’t ready to hear yet.
Friday’s pullback barely dented three weeks of gains — the record run took a breath, not a hit.
Video of the Weekend
Einstein of Wall Street explains the 5 reasons why. We will discuss on this week’s Morning Call and then further on Setup Elite.