Newsletters
Rebel Roundup Newsletter For July 21st: Credit Markets Are Starting to Question AI Execution
By Geoff Garbacz | Market Rebellion · July 21, 2026
TODAY, WRAPPED:
The day’s dominant market belief: AI infrastructure demand is real and buyable again — even as the bond market prices
in higher inflation and tighter financial conditions.
STOCKS SNAPPED A THREE-DAY LOSING STREAK AS CHIPS LED A SHARP REBOUND,
BUT BONDS, OIL, AND OPTIONS FLOW ALL PRICED IN MORE STRESS THAN THE INDEX
LEVEL SUGGESTS.
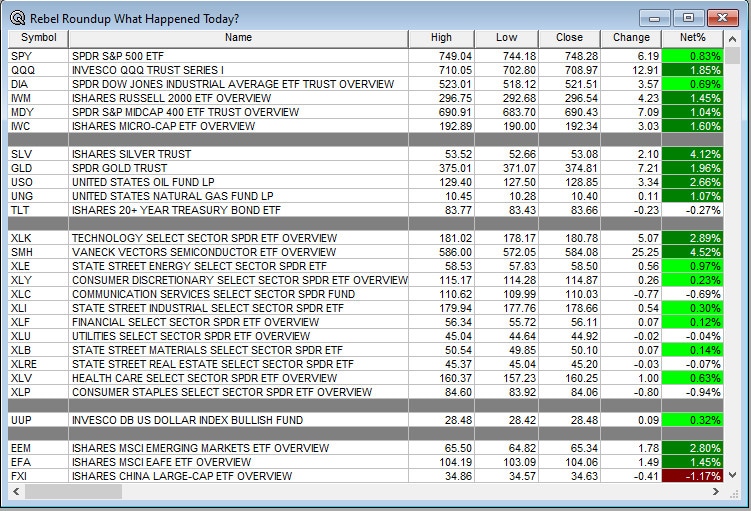
● S&P 500: +65.92 (+0.89%) to 7,509.20
● Dow: +385.38 (+0.74%) to 52,224.6
● Nasdaq Composite: +329.13 (+1.29%) to 25,837.2; NDX +550.94 (+1.93%)
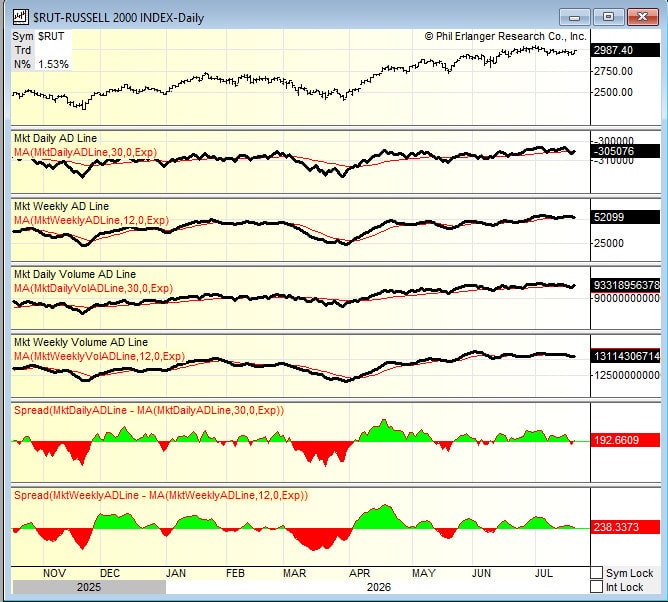
● Russell 2000: +39.51 (+1.33%) to 2,981.55
● VIX: 17.03, -8.69%
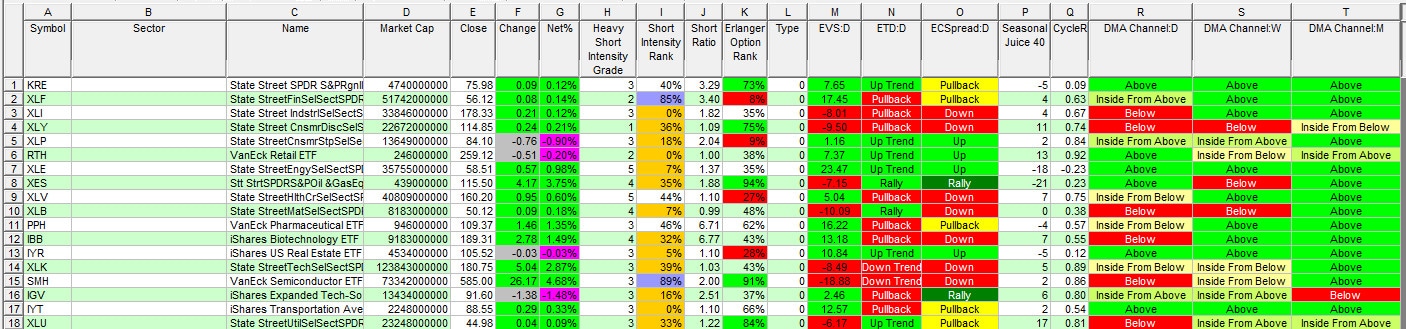
● Fear & Greed Index: 41/100 (Fear), up from 37 at prior close
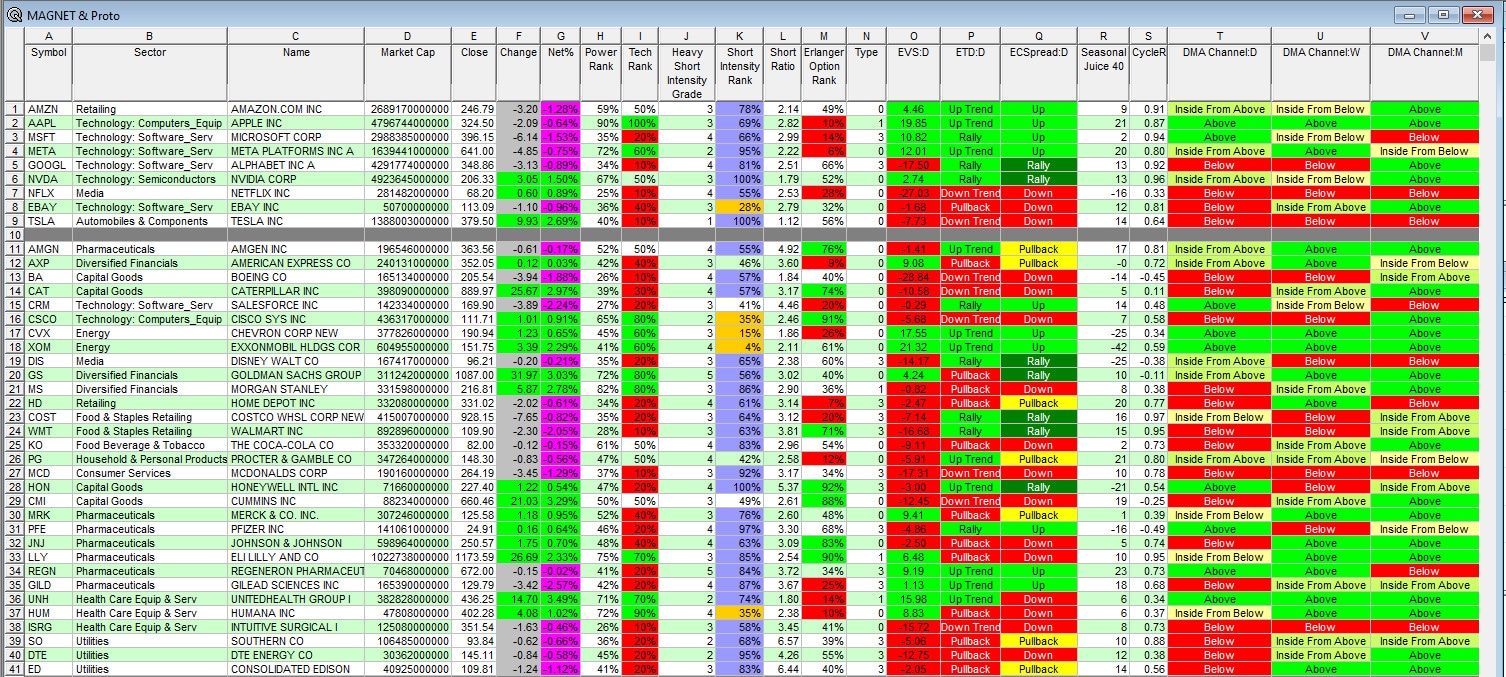
● Breadth: 58.3% advancing vs. 37.5% declining; only 50.5% of names above their 50-day
average and 50.7% above their 200-day
● 10-Year Yield: 4.628%, a roughly two-month high; 30-Year spiked as high as 5.15%
intraday
● WTI: $85.45 (+2.5%); Brent: $91.17 (+2.2%)
● Gold: $4,084 (+1.87%); Silver: $58.68 (+3.91%)
● Bitcoin: $66,363 (+1.76%), briefly tagging $66,666
● SMH: +4.52%
The above combination — equities near all-time highs, VIX under 18, and yet gold, silver, and Bitcoin
all rallying alongside a two-month high in yields — is not a normal correlation pattern. It’s the
clearest signal all day that different corners of the market are pricing different realities.
ADP’s weekly employment gauge printed 16.5K, down from 19.75K prior, a soft continuation of
the labor cooling theme that’s been building for weeks, though it did nothing to slow the
session’s advance.
QUOTE OF THE DAY
“We have no interest in meeting.” — President Donald Trump, on talks with Iran, July 21, 2026.
THE BIG FIVE EVENTS FOR TUESDAY:
1. Chip Stocks Erase Their Losing Streak in a Single Session
Stocks snapped a three-day losing streak as Micron ripped over 12% intraday and reclaimed its
$1 trillion market cap, dragging AMD (+8.1%), Intel (+8.6% ahead of Thursday’s earnings), and
Broadcom (+2.1%) higher with it. Options flow confirmed the move before the bell: fresh call
buying hit AAOI and GlobalFoundries, and SMH gained 4.5% on the day. Technology led all
sectors (+2.90%), though Basic Materials (+2.24%) and Energy (+1.31%) also outpaced the
index — this was a broad risk-on session with chips at its center, not a one-sector move.
Semiconductors now account for over 20% of global trading volume, an all-time high,
underscoring how concentrated the enthusiasm is even within a broad advance.
That makes Wednesday’s Alphabet capex guidance and Thursday’s Intel print the real test of
whether today’s bounce reflects genuine conviction or simply short covering into an oversold
chip complex.
Playbook
Watch: MU and INTC price action into Thursday’s report.
Confirm: SMH holds today’s gains with breadth improving beyond Tech.
Failure: Semis fade back toward Monday’s lows on any AI capex disappointment from
Alphabet.
2. The Bond Market Isn’t Buying the Rally
While the S&P 500 closed within 1.5% of its all-time high, the 10-year yield pushed to a
two-month high and the 30-year spiked as high as 5.15% intraday, as Brent’s move above $90
revived inflation concerns. AGG’s yield now sits 1.3 percentage points above money-market
rates, and Fed rate-hike odds for 2026 have climbed into the 55-64% range across prediction
markets today, up sharply from a week ago. Gold, silver, and Bitcoin rallied alongside those
yields — a combination that doesn’t normally occur together. Equities shrugged all of it off
entirely.
That gap between what bonds are pricing and what stocks are pricing is the single most
important tension in this tape, and it will resolve one direction or the other before the Fed’s next
meeting.
Playbook
Watch: 10Y and 30Y yield levels into Friday’s tariff deadline.
Confirm: Yields keep climbing while equities hold near highs.
Failure: Equities roll over in sympathy with yields.
3. Trump Piles a New Global Tariff Wave on Top of the Canada Hit
The 50% tariff on roughly $20 billion of Canadian goods — covering autos, alcohol, and dairy,
but exempting potash, critical minerals, and most energy — takes effect August 19; Carney says
he and Trump agreed to accelerate trade talks before then. Separately, the FT reports Trump is
preparing fresh 10% tariffs on dozens of countries as the temporary global 10% rate expires
Friday, over the objections of advisors worried about economic shocks heading into the
midterms. The administration is also exploring more durable “forced labor” tariffs as a legal
workaround. None of it moved markets much today, buried under the chip rally and Iran
headlines.
That market indifference won’t survive a chaotic Friday rollout, so the next 72 hours of tariff
mechanics matter more than today’s muted reaction suggests.
Playbook
Watch: Friday’s 10% global tariff expiration and what replaces it.
Confirm: A clean, telegraphed replacement structure emerges.
Failure: A larger or messier tariff wave rattles risk assets into the weekend.
4. Hegseth Puts a $37.5 Billion Price Tag on the Iran War, Asks for $87.6 Billion More
Testifying before the Senate as protesters were repeatedly removed from the room, Defense
Secretary Hegseth said the Iran conflict has cost $37.5 billion so far and warned troop training
and pay are at risk without the requested supplemental funding. Trump separately said the US
will strike the Pickaxe Mountain nuclear site “pretty soon, and very heavily,” while ruling out talks
until Iran is “ready to meet in a meaningful way.” Seventeen US troops have died since the war
began, and both sides are now hitting civilian infrastructure — Kuwait’s desalination plants for a
fourth consecutive night, per its government. Oil moved on the broader war narrative today, but
the conflict’s cost is no longer abstract; it has a specific number, and Congress now has to
decide whether to write the check.
That $87.6 billion request lands squarely in the midterm-year budget fight, and how Congress
handles it over the coming weeks will say more about Washington’s appetite for a longer war
than any single battlefield headline.
Playbook
Watch: Senate Appropriations Committee action on the supplemental request.
Confirm: Bipartisan pushback stalls or trims the funding.
Invalidate: The $87.6B passes quickly, confirming tolerance for an open-ended conflict.
5. Credit Markets Are Starting to Question AI Execution
Oracle shares actually rose 4.67% Tuesday, but that’s the wrong tape to watch — the cost of
insuring Oracle’s debt against default hit a fresh multi-year high Monday and its bonds sold off,
as doubts grow over whether its AI infrastructure bet pays off. Danaher beat earnings estimates
and still posted its worst drop since 1991. IBM is still working through the aftershocks of its July
14 selloff, and remains a name traders are watching closely for further unexplained weakness.
None of these are Iran or tariff stories — they’re signs that credit and single-name equity
markets are pricing AI execution risk separately from the index-level enthusiasm driving today’s
rally.
Credit markets are no longer the only place showing caution. The options market is beginning to
echo it.
Playbook
Watch: Oracle 5-year CDS levels into Wednesday and Thursday’s AI earnings.
Confirm: More AI-adjacent names see unexplained drawdowns despite in-line results.
Failure: This week’s earnings slate reassures credit markets and spreads normalize.
Market ANALYTICS:
TRACKING TODAY’S ACTION
top dog
BREADTH
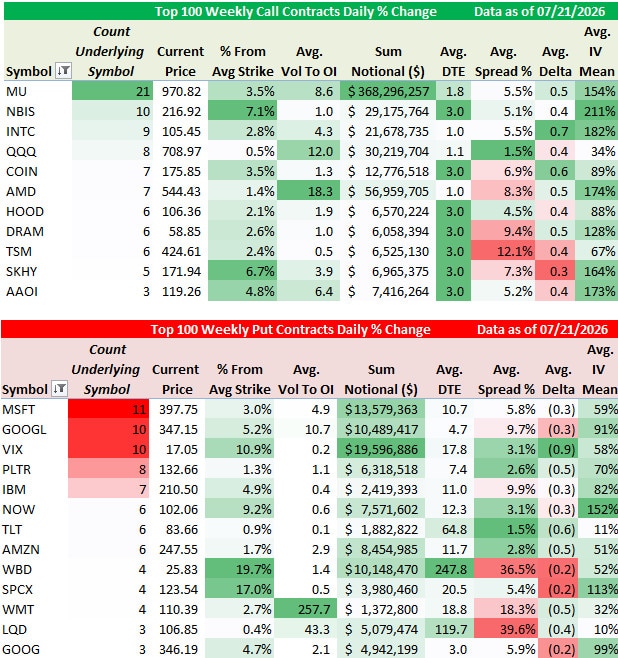
UOA AND TOA:
VIX — Bullish Call Buying. Two separate prints today bought a combined ~72,000 August 29
calls, while spot VIX closed at 17.03.
Something to consider: buying 29-strike calls against a spot VIX in the 17s is a bet on roughly a
70%+ vol spike before August expiration. That premium flows to dealers or vol sellers, who pick
up gamma exposure that could force further vol-buying if VIX actually approaches that strike. If
Iran, tariffs, or a Fed repricing produce a real shock before mid-August, this pays multiples; if the
tape grinds higher, the premium simply decays.
SPX — Bearish Put Spread. 53,500 Sep 6100 puts bought, financed by selling 53,500 of the
6000-strike puts, against an underlying trading 7,466-7,494 — a hedge roughly 19% below
Tuesday’s close.
Something to consider: the capped structure is what a hedger does, not a speculator. Buying
protection 19% out of the money while the index sits near highs signals the buyer sees tail risk
as underpriced relative to what spot VIX and equities currently reflect.
AAOI — Bullish Call Buying. 6,000 July 24 125 calls bought mostly in one order, above open
interest of 851 contracts, stock trading $109-112.
Something to consider: a short-dated, aggressive bet on Applied Optoelectronics extending its
run before Thursday’s expiration, lining up with today’s rotation into AI’s optics layer. If optics
keeps leading semis, capital is still willing to chase AI infrastructure even with credit markets
flashing caution elsewhere.
GFS — Bullish Call Buying. 6,000 August 21 70 calls bought mostly in one print, above open
interest of 853 contracts, stock at $59.38.
Something to consider: an 18%-out-of-the-money August call is a leveraged bet the
memory/foundry rally extends well past today. Given SK Hynix’s disclosure that the US now
generates 65% of its quarterly revenue, up from near-zero in 2019, this reads as a bet that US
AI infrastructure demand for foundry capacity keeps compounding.
IBIT — Bullish Call Buying. Two separate buys today at the August 31 39 and 44 strikes, both
above open interest, as Bitcoin traded through $66,000.
Something to consider: scaling into two strikes on the same expiration suggests building upside
exposure rather than a single conviction bet. This lines up with BlackRock’s own clients buying
$116 million of spot Bitcoin today, and with crypto’s move higher alongside gold, silver, and
yields — the same unusual cross-asset correlation flagged above.
THE DAILY DASHBOARD: LEADERS AND LOSERS
We now track where option players made the most money today on both the Call and Put side. 0DTE are not part of the calculation.
AFTER THE CLOSE
Notable Earnings Out After The Close:
- Beats: COF +1.14, CB +0.48, AIR +0.15, RRC +0.14, ALK+0.07, IBKT +0.05, EWBC +0.02, OZK +0.01 of note.
- Misses: WFRD -0.35, PEGA -0.08, FFBC -0.05, WBS -0.04, NBHC -0,03, EQT -0.02 of note.
- Flat: WAL HWC of note.
Winners From Tuesday: FNWD +20.2%, SMCI +18%, RKLB +6.5%, OKLO +5.8%, CPHI +5.7%, DELL +5.7%, HPE +4.9%, WFRD +3.2%, MRVL +2.1%,
Losers From Tuesday: CALX -13.5%, PEGA -13.4%, NBHC -5.7%, AIR -4.9%, OZK -2%.
After The Close:
- SuperMicro (SMCI) guides JunQ revs to the low end of guidance, but raises gross margin guidance; backlog rose to record levels.
- Palo Alto Networks (PANW) to buy Embrace, adds digital experience monitoring to observability platform.
- Armstrong World (AWI) raises quarterly dividend to $0.339/share from $0.308/share.
- Oklo Inc. (OKLO) and X-Energy (XE) join Trump administration program to bring new nuclear reactors online faster for AI. (Bloomberg)
- EQT signed a 5-year offtake agreement with a large Asian integrated energy company in Q2.
- Rocket Lab (RKLB) awarded a $266 mln Air Force contract for suborbital launch.
- 10Q Delays – None of note.
Executive, Corporate Changes:
- Tapestry (TPR) Unit Kate Spade New York announces the appointment of Jonathan Saunders as Executive Creative Director, effective August 26, 2026.
Buybacks of Note:
- AWI adds $800 mln to buyback.
Dividend Info:
- APH CNQ STM ESLT QSR CINF WRB SGHC HTLD goes Ex-Div Wednesday.
- goes Ex-Div Thursday.
- NTRS raises quarterly common dividend to $0.88/share
QUESTIONS FROM THE ROWDY REBELS
Q: Do you have a good source for when companies get added to the major indexes? — Mike M.
A: Geoff G. said he subscribes to Briefing.com, which does a good job predicting upcoming
index additions and removals. With several companies shifting between the S&P MidCap and
SmallCap indexes this week, tracking index changes can provide an informational edge before
passive fund flows adjust.
Q: AXTI options seem really pricey, reason? — Clark Z.
A: Chris S. said implied vol is mostly just creeping back toward its recent highs rather than
genuinely stretched, and that relative to ATR, buyers are paying a premium versus what the
underlying is delivering — likely the run into AXTI’s July 30 earnings. Similar option activity
appeared across the optics group today, with AAOI seeing 6,000 July 24 125 calls bought above
open interest.
Q: So on Think Or Swim there is the VWAP upper and lower bands, do you use those as support or
resistance? — Craig C.
A: Mike M. said yes, but mostly relies on the center line, buying calls above VWAP and flipping
to puts on a breakdown. In a market where leadership remains relatively narrow beneath the
surface, VWAP-based intraday discipline becomes more important than simply following the
headline index. Geoff find VWAP useless and relies on intraday Erlanger Volume Swing as a superior
indicator to VWAP.
WATCHLIST
AI Infrastructure / Chip Rally
Bull: Micron’s 12%+ surge and reclaimed $1T market cap, SK Hynix’s revenue mix flipping
toward 65% US, and TSMC’s planned price hikes together suggest AI infrastructure demand
appears increasingly structural rather than a passing cycle. Record semiconductor trading
volume reinforces that read. Hyperscalers signing multi-year HBM contracts regardless of price
removes the historical oversupply cycle that has burned this trade before.
Bear: The same concentration that makes semis look unstoppable also makes them the
market’s single point of failure — a disappointing Alphabet capex guide or Intel print could
unwind today’s bounce just as fast, especially with Oracle’s CDS spread already signaling doubt
about whether AI infrastructure spending pays off at all.
Bond Market / Fed Path
Bull: If oil’s spike proves geopolitical and temporary — a ceasefire or Hormuz reopening would
deflate Brent quickly — the yield spike is a transient inflation scare, not a structural shift, and
equities are correctly treating it as noise.
Bear: Fed hike odds jumping into the 55-64% range in a single week, alongside 30-year yields
near their two-month high and mortgage rates creeping toward their YTD high, suggests bonds
are pricing a stagflationary mix that equities haven’t caught up to yet.
Iran War Trajectory
Bull: Iranian officials meeting mediators in Pakistan, a floated 10-day ceasefire framework, and
today’s Lebanon flight announcement all suggest diplomatic tracks remain alive even as strikes
continue.
Bear: Trump’s explicit refusal to negotiate, the promised Pickaxe Mountain strike, a $37.5 billion
war bill already logged, and both sides now hitting civilian infrastructure point toward further
escalation, with Hormuz traffic already down to a handful of ships per day.
Rebel’s Edge For 7/21 (from You Tube link – RebelsEdgeOfficial):