
Newsletters
Rebel Roundup Newsletter For7/28: In Midst of Worst Month Since 2001 For Semiconductors, Rotation Has Saved the Indexes
TODAY, WRAPPED
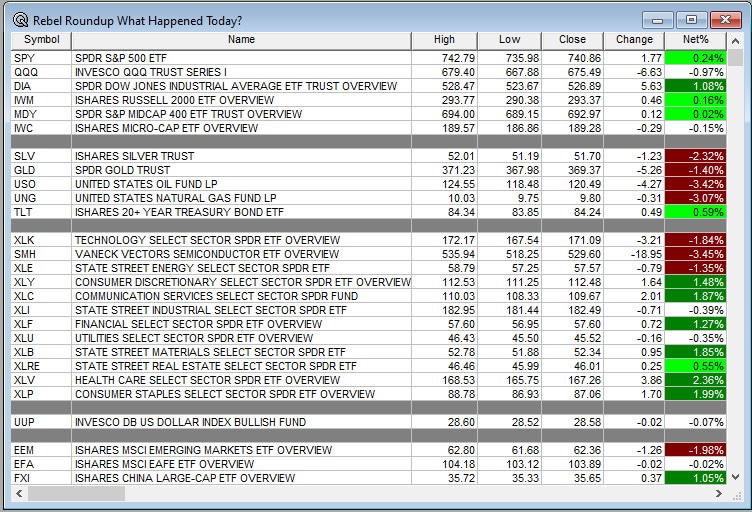
The day’s dominant market belief is that semiconductor weakness is a contained, healthy rotation away from an uncontrolled round of selling — not the start of an AI crash. The S&P 500 closed at 7,428.78 (+0.21%), The Dow surged 537 points (+1.03%) to 52,747.30, while the NASDAQ fell 0.22% to 24,876.90 while the VIX eased to 18.33.
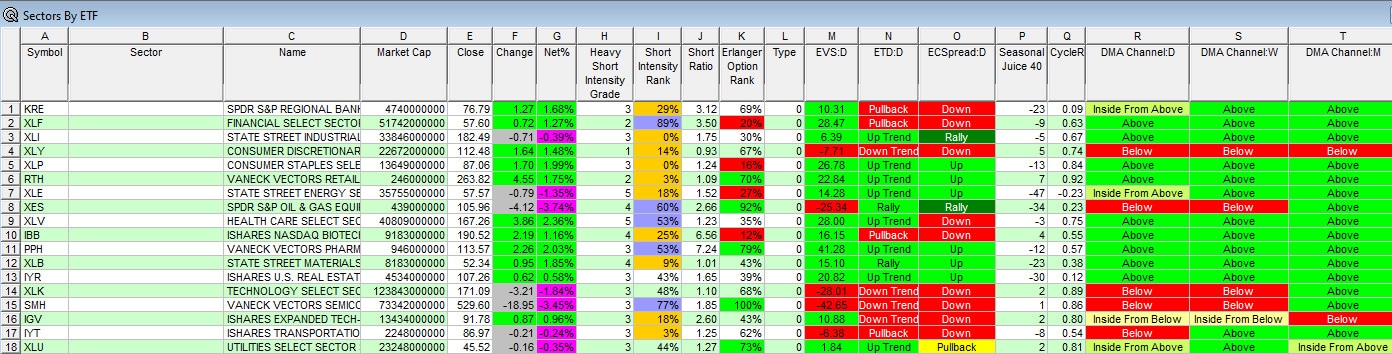
The Philadelphia Semiconductor Index is on pace for its worst month since September 2001. Micron (MU) fell 8.85%, AMD dropped 8.15%, SanDisk (SNDK) collapsed 14.25%, SK Hynix’s (SKHY) U.S. shares fell 9.03% — trading below their IPO price for the first time. The trigger came from Seoul: Korea’s Kospi crashed 10.8% Tuesday, one of its worst single-day losses on record, dragging Japan’s Nikkei down roughly 3.95% and exposing just how globally leveraged the AI-chip trade had become. Yet the S&P 500 sits less than 3% below its all-time high, and breadth actually improved: 53% of stocks advanced against 43% declining, new highs beating new lows 328 to 234. The damage stayed concentrated. That’s the story.
Song Stuck In Kevin Warsh’s Head – “Should I stay or should I go now. If I go there will be trouble and if I stay it will cost me double”
THE LEAD
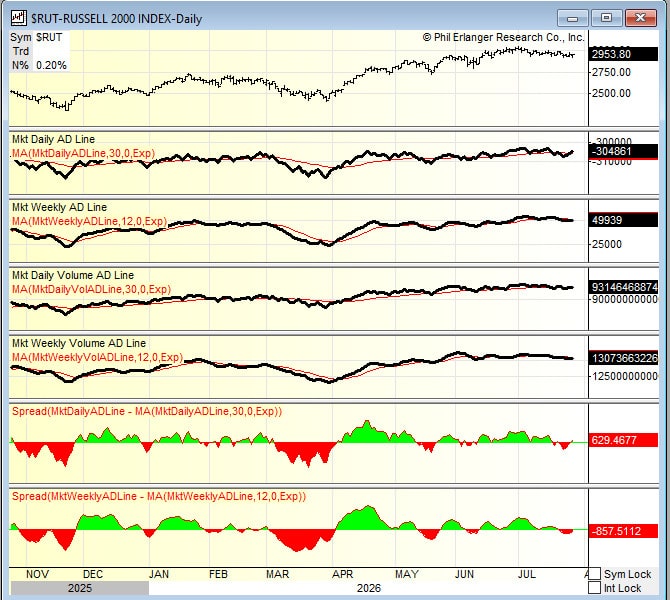
Rotation, not rout — that’s the belief the tape is pricing, and so far the evidence backs it up (see the numbers above: semis cratered, breadth held, the Fear & Greed Index actually improved to 38 from 43 a week ago and 24 “Extreme Fear” a month ago). Investors aren’t panicking. They’re reallocating. The Erlanger Big Barf (EBB) is still negative at -2.33 so it is saying we are not out of the woods. Compare contrast Fear & Greed to EBB is a useful exercise.
Falling oil did the heavy lifting. WTI settled down 3.4% at $79.76 as the U.S.-Iran ceasefire held and mediators signaled progress on a broader deal. That eased inflation pressure one day before the Fed’s potentially most divided decision since March 2020, and money moved accordingly — into Consumer Defensive (+2.19% today, +3.71% this week), Healthcare, and Financials, while Technology fell 1.49% and is down 5.16% on the week. Coca-Cola (KO) and Boeing (BA), both up on earnings, did more for the tape than any chip name did to hurt it.
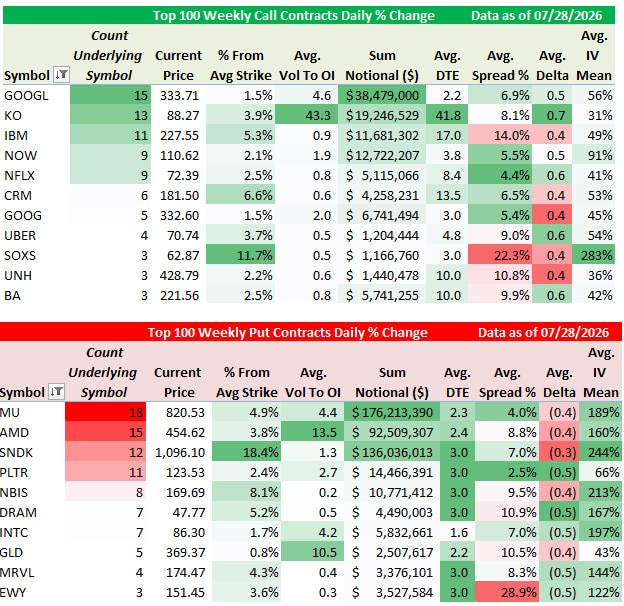
Institutional flow warned early: SMH put positioning turned decisively bearish three sessions before the Kospi crash, while retail was still chasing the trade higher (full detail in UOA & TOA below). That’s the kind of positioning that doesn’t show up in headlines until after the move happens. Oh by the way …
The precedent worth remembering: in late 2018, semiconductors fell more than 20% over two months on rate-hike fears while the broader market initially held its ground — until the Fed’s hawkishness dragged everything down together in December and then the Fed capitulated starting a rally in 2019 that ran until April. This time the catalyst runs the other way. Falling oil is easing rate pressure, not adding to it, and Wednesday’s FOMC is pricing roughly 70-77% odds of a hold. If that holds, semis’ pain stays contained. If Warsh surprises hawkish, then 2018’s playbook becomes a risk and you will want to have lots of cash and play the put side and the inevitable bounces..
Geoff’s Take: Garbacz bought NVDA calls near midday, calling it flat out: “semis trying to turn here.” Not a conviction long-term view — a Squeeze Play, on the belief that Tuesday’s carnage was closer to exhaustion than the start of something worse.
BTIG’s View: Institutional clients got a shorter version of the same idea — “Don’t go chasing waterfalls.” This isn’t the spot to press semiconductor shorts.
So what happens next matters more than what happened today. Wednesday’s Fed decision and Thursday’s Microsoft, Meta, and Amazon earnings decide whether this stays a rotation or becomes a rout — because a hawkish surprise from Warsh, or a capex pullback from the hyperscalers, is the one combination that turns today’s contained damage into tomorrow’s broad one.
Warsh knows that damage has been done to the market in July and the market did his work for him. He learned this from years of his talks with Stanley Drukenmiller.
THE MARKETS
Technology was the only sector down on both a 1-day and 1-week basis (-1.49%/-5.16%); Consumer Defensive led both (+2.19%/+3.71%). The SOX is on pace for its worst month since September 2001 — final tally to confirm at month-end — even as the S&P 500 sits under 3% from its record high.
THE BUZZ
-
FOMC decision Wednesday 2pm ET; ~70-77% odds of a hold, ~25-30% odds of a hike — the most divided pre-meeting positioning since March 2020, sharpened by Fed Chair Kevin Warsh’s hawkish public tone since taking the chair
-
Microsoft (MSFT) and Meta (META) report Wednesday after the close; Amazon (AMZN) and Apple (AAPL) report Thursday
-
July Consumer Confidence missed at 90.8 vs. 92.3 expected
-
Boeing (BA), Coca-Cola (KO), UPS (UPS), PayPal (PYPL) beat this morning; Ford (F), Visa (V), Bloom Energy (BE), KLA (KLAC) beat after the close
-
Corning (GLW) fell 16% on guidance; Oracle (ORCL) hit a fresh 52-week low.
UOA & TOA
VanEck Semiconductor ETF (SMH) — Bearish Put Buying & Roll (7/27, ahead of the Kospi crash)
Large put buyers rolled into higher strikes and added fresh downside exposure three sessions before Tuesday’s crash — priced well above open interest, a signature of institutional positioning, not retail noise.
Why it matters: the risk transferred from whoever sold those puts onto buyers who were, in effect, pre-positioning for exactly the move that followed. If SOX stabilizes into earnings, this unwinds at a profit; if hyperscaler capex disappoints, expect this flow lower again.
iShares Semiconductor ETF (SOXX) — Bullish Call Spread Roll (7/28)
A position first opened July 7 was rolled higher and added to — into Tuesday’s worst semiconductor session in years, not exited from it.
Our read: someone with size is treating this week’s carnage as a level to add to a long-dated bullish view, not a reason to leave.
Consumer Staples Select Sector SPDR Fund (XLP) — Bearish Put Spread & Buying (7/28)
Two separate put trades hit the tape as the staples ETF made a 52-week high.
What we’re watching: not everyone is chasing the defensive rotation at these levels. If Wednesday’s Fed decision removes the anxiety driving flows into staples, this is the trade that profits from money rotating back out.
iShares MSCI USA Momentum Factor ETF (MTUM) — Bullish Call Buying (7/28)
Fresh call buying even as the momentum factor turned negative for the year.
Risk: a contrarian bet that today’s snapback in growth names has legs, right as consensus turned skeptical of momentum. Reaffirmed AI capex Wednesday validates it; anything less makes it a knife-catch.
Most active options: Nvidia (NVDA), Tesla (TSLA), Apple (AAPL), Micron (MU), Intel (INTC), Microsoft (MSFT), AMD (AMD), Amazon (AMZN), Alphabet (GOOGL), SpaceX (SPCX), Meta (META), Palantir (PLTR), Oracle (ORCL), Netflix (NFLX)
Rising volume to watch: Micron (MU), Intel (INTC), SpaceX (SPCX), Palantir (PLTR), Warner Bros. Discovery (WBD), Oracle (ORCL), Netflix (NFLX), SoFi (SOFI), MicroStrategy (MSTR), Iris Energy (IREN), Nokia (NOK)
TOP TICKERS
Nvidia (NVDA), AMD (AMD), Micron (MU), SanDisk (SNDK), SK Hynix (SKHY), Apple (AAPL), Coca-Cola (KO), Boeing (BA), Corning (GLW), Tesla (TSLA)
AFTER THE CLOSE
Ford (F) beat on both lines and raised full-year adjusted EBIT guidance to $10-11B. Visa (V) beat across the board. Bloom Energy’s (BE) revenue came in roughly 29% above estimates. KLA (KLAC) beat and guided above consensus. Skyworks (SWKS) beat and announced a $2B buyback but eliminated their dividend, ouch!!. Wednesday brings the FOMC decision at 2pm ET, followed after the close by Microsoft (MSFT) and Meta (META) — the week’s real test.
Geoff Garbacz, live on today’s Chart Room webinar for Rebel Roundup Pro readers, called BE’s move “doing pretty good” — he’d like to see it clear $200, though he was skeptical the print alone moves sentiment on hyperscalers, software, or semis broadly this week.
Winners From After The Close: VRRM +24.5%, RCKY +17.6%, ENPH +2.8%, NEO +2.6%, SLDE +2.6%, TER +13.5%, BE +10.8%, MANH +10.6%, NOV +7%, STX +5.3%, F +5.1%, CAKE +3.7% of note.
Losers From After The Close: OI -13.7%, CSGP -12.4%, CAR -11.3%, SWKS -10.5%, ORN -8.1%, KLAC -7.5%, RBBN -6.2%, NXPI -4.8%, RNST -4.3%, LSTR -4.2% , PPG -4.1%, QRVO -3%, WM -3%, EXLS -2.6%, ROG -2% of note.
Big Beats and Misses
Earnings Beats:
- EXLS +21.45, THG +1.47, STX +0.61, LOGI +0.60, QRVO +0.53, GEF +0.50 of note. (+0.50 >)
Earnings Misses:
- ASH -0.98, NBR -0.74, AXS -0.41, CZR -0.35, OI -0.15 of note. (-0.15<)
- Trump Administration planning to end subsidy program for Medicare drug plans. (NYT)
- Ford (F) raises FY26 outlook for Adjusted EBIT to $10-11 bln from $8.5-10.5 bln; raises FY26 adjusted free cash flow guidance to $6-7 bln from $5-6 bln.
- OpenAI agent compromised an account at another tech company. (Reuters)
- Trump Administration bans Chinese humanoid robots.
- Meredith Whitney warns of a “US Reckoning” in Q4. (Bloomberg)
- 10Q Delays – None of note.
Executive, Corporate Changes:
- KMT names Joseph Alvarado incoming chairman; William Lambert to retire in October.
- WRB names Christopher Moede president of Berkley Risk.
Buybacks of Note:
- SWKS announces new $2 bln repurchase program, suspends dividend program
Dividend Info:
- UMBF raises quarterly common dividend 16.3% to $0.50/share.
- SWKS
THE REAL STORY
Equities Are Pricing a Rotation. Credit Is Pricing a Reckoning.
The gap between how stocks and bonds are treating this week’s AI wobble is the most important thing that happened Tuesday, and it barely made the equity headlines. Fitch Ratings flagged an AI correction as an “emerging major credit risk.” The cost of insuring against hyperscaler default hit record levels per the FT. Nvidia’s (NVDA) own CDS jumped to a record after its $750 billion-plus financing commitments were detailed in Bloomberg on Monday morning. Fixed-income investors are pricing something closer to structural stress than a healthy rotation.
Jargon note: equity investors are asking how much AI will earn? Credit investors are asking whether the companies financing that growth can comfortably service the debt piling up behind it?
This is the same concentration story from the top of the letter, just showing up in a different market. BofA data shows 43% of hyperscaler debt now runs longer than 10 years, nearly double the share in typical corporate financing — and Alphabet’s (GOOGL) first negative free-cash-flow quarter since at least 2016 is the clearest single data point for why that maturity mismatch matters now.
The scenario to watch: if Microsoft (MSFT) and Meta (META) pair strong capex guidance with a credible free-cash-flow path Wednesday night, credit’s warning gets reinterpreted as a growth story arriving late to be priced — not a bubble bursting and Google (GOOGL) will find itself being slammed into the sand by unkind waves. If they reaffirm spending without addressing how it gets financed, expect spreads to keep widening even as the stocks rally on the headline beat — a divergence that has historically been the more reliable signal of the two.
Playbook
Watch: Hyperscaler CDS spreads relative to the equity reaction to Wednesday/Thursday earnings.
Confirm: Spreads narrow alongside strong reactions — both markets agree the spending is sustainable.
Failure: Equities rally on beats while CDS spreads keep widening.
QUESTIONS FROM THE ROWDY REBELS
Q: Is Nvidia (NVDA) on your radar with the drop under $200? — Allen F.
A (Geoff Garbacz): Buy the 8/7 $200 call — semis look to be trying to turn here. Squeeze Play idea, not a conviction hold; size accordingly.
Q: What is your view on Palantir (PLTR)? — Gene H.
A (Geoff Garbacz): It’s been kind of a dog, but shorts are coming into it. The question is whether it can clear $125, then $130, $135, $140, and ultimately get above $153.74. It’s a good company that got overpriced and got pounded too much when software broadly sold off. Real opportunity to pick up shares at a decent level right now.
Q: Trade flash showing sold 3k Sept 220 puts, sold 3k 260 calls, sold 3k 250 calls, bought 6k 270 calls in Amazon (AMZN) — thoughts? — Mark R.
A (Chris Sykora): Call butterfly with a protective put purchase — net bearish despite the call-heavy structure. Newly opened, not a roll — a fresh directional bet into earnings.
Q: Meta (META) closing below 600 with earnings coming — any trade here? IV is super high. — Dennis M.
A (Geoff Garbacz): Heavily shorted, and shorts in this name usually lose, with seasonality in its favor too. Kind of a roll of the dice, though — technicals are still weak.
Q: Boston Scientific (BSX) has earnings tomorrow — wait or add now? — Mike M.
A (Chris Sykora): They’re adding ahead of the print — not much crush built into December, downside looks limited barring a total crash. Someone’s gunning for a serious rebound in the 67.50 calls, and that same buyer nailed the floor with a 40-strike put sale.
WATCHLIST
Theme: AI Financing & Credit Risk
Bull: Strong capex guidance paired with credible free-cash-flow paths reframes the Fitch warning as premature — credit catching up to a growth story, not a bubble bursting.
Bear: Spreads keep widening even as equity headlines stay positive — credit smells trouble before equities are willing to price it in.
Theme: The Fed’s Most Uncertain Decision Since 2020
Bull: A clean hold with minimal dissent removes the week’s biggest overhang and validates the falling-oil disinflation story.
Bear: A surprise hike, or a dissent count signaling September is live, hits an already-fragile semiconductor complex at the worst possible moment.
CLOSING LINE
The rotation thesis survives another day. Watch whether Warsh holds the line and whether Microsoft (MSFT) and Meta (META) back their spending with cash flow to match; get both right, and this week goes down as a healthy reset. Get either wrong, and today’s isolated damage spreads more broadly.
https://youtu.be/Q1m0ibjCPWE?si=xMrWn2LFOO7a-v98
Did you miss out latest LEAP pick? It was out today in Rebel Roundup Pro and it could be a big winner by January of 2028. What’s the difference between a Rebel Roundup Pro and Newsletter Reader? Upgrade and find out.