
Newsletters
Rebel Roundup Newsletter For Weekend of July 17-19: Can Semiconductor Stocks Rally? Can The Market Rally As Fighting Gets More Pronounced. Futures FLat
FRIDAY, WRAPPED: The day’s dominant market belief: the
AI-infrastructure trade got too big, too fast, too concentrated
— and FRIday the market started pricing that risk instead of
ignoring it. Will that continue on Monday?
AI CONCENTRATION RISK STOPPED BEING A THEORY TODAY. CHIPS FELL INTO AI CONCENTRATION RISK STOPPED BEING A THEORY TODAY. CHIPS FELL INTO ABEAR MARKET, IRAN ENTERED A SEVENTH NIGHT OF STRIKES, AND THE STOCK THAT FELL LEAST BECAME THE WORLD’S MOST VALUABLE COMPANY.
● S&P 500: 7,457.69, -76.08 (-1.01%). First down -1% day in July for this index.
● Nasdaq Composite: 25,520.2, -361.70 (-1.40%). Been down multiple days more than -1% in July.
● Nasdaq 100: 28,592.66, -433.11 (-1.49%)
● Dow: 52,146.4, -406.55 (-0.77%)
● Russell 2000: 2,962.22, -12.35 (-0.42%)
● VIX: 18.74, +2.01 (+12.01%)
● Fear & Greed Index: 37 (Fear), down from 41 yesterday and 46 a week ago — a sharp
reversal from 74 (Greed) a year ago
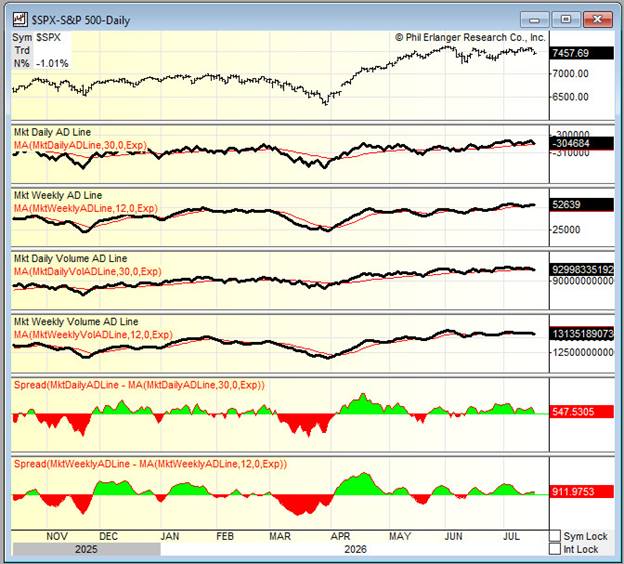
● Breadth: 1,931 advancers vs. 3,469 decliners (61.8% declining), a reversal from
yesterday’s better-than-2-to-1 positive breadth
● New Highs 234 vs. New Lows 245 — lows outnumbered highs for the first time in weeks
● Above SMA50: 51.1% / Above SMA200: 50.9% — still majority-bullish under the hood
● WTI: $82.60 (+3.27%); Brent’s biggest weekly gain since April
● Gold: $4,010.68 (+0.83%); Silver: $56.06 (+0.99%). Were higher and bucked down trend.
● Bitcoin: $63,949 (+0.25%)
● 10-Year Yield: 4.54% (-0.57%)
That breadth flip is the headline. Yesterday the S&P fell 0.5% with advancers beating decliners
2-to-1 — proof the damage was contained to chips. Today the ratio inverted. This was the day
the selloff stopped being a semiconductor story and became a market story.
Housing Starts (1.427M vs. 1.31M expected) and Michigan Sentiment (54.4 vs. 49.5 prior) both
beat comfortably. Neither mattered — the market has a bigger problem to solve, AI.
THE BIG FIVE EVENTS FROM FRIDAY:
1) The Philadelphia Semiconductor Index Falls Into a Bear Market, Kinda As Still Up a Ton For Year.
Narrative: SOX is down over 20% from its June high after its worst week in over a year. SMH
closed -2.18% today alone. Semiconductors have grown to roughly 20% of the S&P 500’s
weight, more than double the dot-com peak of ~8%. The trigger: China’s Moonshot AI unveiled
Kimi K3, a model reportedly ranked ahead of Anthropic’s Opus 4.8 on some benchmarks — the
first Chinese open-weight model to do so. The fear is the “capex domino effect”: if U.S. labs lean
more on cheap or comparable Chinese alternatives, the assumption of infinite chip demand
cracks. Today’s damage was uneven: NVDA -2.29%, AMAT -5.68%, SNDK -7.85% — but STX
+5.56%, CSCO +2.08%, ORCL +1.77%. Even inside “the chip trade,” money rotated rather than
fled.
Wednesday’s MU earnings reaction next week will be the real test of whether this is a valuation
reset or the start of a genuine demand repricing.
Playbook Watch: Whether SOX finds support near its 200-day, or memory names extend toward 30%+
drawdowns.
Confirm: Continued divergence within semis rather than uniform capitulation.
Invalidate: A broad reversal where even STX and WDC roll over with NVDA and AMAT.
2) Iran War Escalates to a Seventh Consecutive Night of Strikes
Narrative: CENTCOM confirmed a seventh straight night of strikes, expanding to bridges,
energy infrastructure, and Chabahar port. Iran retaliated into Qatar and Kuwait, damaging a
desalination plant supplying 90% of Kuwait’s drinking water. U.S. casualties: 14 dead, 427
wounded since the war began, at an estimated $113.3B cost. Hormuz crossings fell to a
three-week low of eight vessels. Axios reported the U.S. is sending “dozens more” refueling
planes to Israel ahead of a possible “massive offensive” on Iranian power and nuclear sites,
while an adviser to Iran’s Supreme Leader warned of “full-scale offensive operations” if strikes
continue. Crude responded on cue — WTI +4.23%, gasoline futures at a two-month high. Yet
Energy was the only green S&P sector today (+1.46%) and the week’s clear leader (+4.28%) —
the market isn’t panicking about oil, it’s positioning for it.
That’s the story to track into next week, because oil options still haven’t fully repriced for a
genuine infrastructure-strike scenario — they’re trading a Hormuz-disruption book, not a
“massive offensive” book.
Playbook Watch: Brent’s approach to $90 and confirmation of expanded Iranian-infrastructure strikes.
Confirm: XLE keeps outperforming while refiner margins (VLO, PSX, MPC — all at 52-week
highs) stay elevated.
Invalidate: A ceasefire signal that sends Brent sharply lower and unwinds the tanker/refiner
trade fast.
3) When “Beating” the Number Still Wasn’t Enough
Narrative: Netflix closed -7.39% (a 52-week low) despite revenue essentially in line and EPS a
penny ahead — the damage came from Q3 guidance below estimates and a cut to engagement
disclosure. It’s now four straight quarters of post-earnings declines. Intuitive Surgical fell
-14.19% despite beating on both lines and holding full-year guidance — Middle East softness
and the slowest da Vinci growth in four years did the damage. Neither stock was punished for
the number; both were punished for what the number implied about trajectory. Geoff Garbacz’s
read this morning: “Reed Hastings left, and that was the first hint.” Stripping subscriber and
engagement transparency is exactly the “new management” risk now being priced.
Expect continued scrutiny of disclosure cuts across consumer and healthcare-tech names into
next earnings season — this is now a governance story as much as a growth story.
Playbook Watch: NFLX holding the low-to-high $60s; ISRG’s response at its 52-week low.
Confirm: Further guidance cuts or disclosure reductions elsewhere in
consumer/healthcare-tech.
Invalidate: A sharp bounce on valuation alone, without any guidance upgrade.
4) Apple Reclaims “World’s Most Valuable Company” — By Falling the Least
Narrative: Apple closed $333.95 (+0.14%), edging Nvidia’s market cap by roughly $34B —
back on top for the first time since May 2025, achieved by falling less than everyone else rather
than by rallying. HSBC upgraded Apple to Buy ($366 target) on an AI-monetization thesis rather
than an infrastructure one. Meanwhile the AI-compute web keeps tightening: Meta is reportedly
in talks to lease up to $10B of compute to Anthropic over two years (META pared losses to
-2.79% on the news) — about a third the size of Anthropic’s existing $45B SpaceX deal, while
SpaceX (SPCX) separately negotiates selling AI capacity to the Pentagon. Hyperscalers are
increasingly leasing compute to each other, turning overbuild risk into a revenue line.
That’s the trade to watch into next week: whether the Meta-Anthropic deal formalizes will be the
clearest signal yet of whether “compute leasing” becomes a real, durable hyperscaler revenue
line or just a headline that faded.
Playbook Watch: Whether the Meta-Anthropic deal formalizes, and further hyperscaler compute-leasing
announcements.
Confirm: AAPL holds the top spot into next week; AI-monetization upgrades continue.
Invalidate: NVDA reclaims the crown on a chip-sentiment snapback, or the leasing narrative
unravels publicly.
5) Record Margin Debt Meets a Broadening Selloff
Narrative: U.S. margin debt hit a record $1.5T in June, up $494.1B (+49%) over 12 months. A
broader leverage measure is now above the 2000 dot-com peak. Bruce Kaufman flagged a
negative divergence between high-yield debt and the S&P 500 developing last Friday, prompting
Market Rebellion’s managed accounts to zero out semiconductor exposure and rotate into
chemicals, oil, and healthcare. Today validated the call: Energy +1.46% (the only green sector),
Communication Services and Technology led losses. XLP vs. XLK posted its best two-day
relative gain since 2002. The Nasdaq 100 and Russell 2000 are technically confirming bearish
trends; the S&P 500 is not — yet.
High-yield spreads over the next week will be the real test of whether this is healthy
deleveraging in the market’s most crowded corner, or the first crack in something bigger.
Playbook Watch: High-yield spreads relative to the S&P over the next 3-5 sessions.
Confirm: Continued XLP/XLE/XLV outperformance vs. XLK/XLC.
Invalidate: A snap-back in high-beta tech that closes the high-yield divergences.
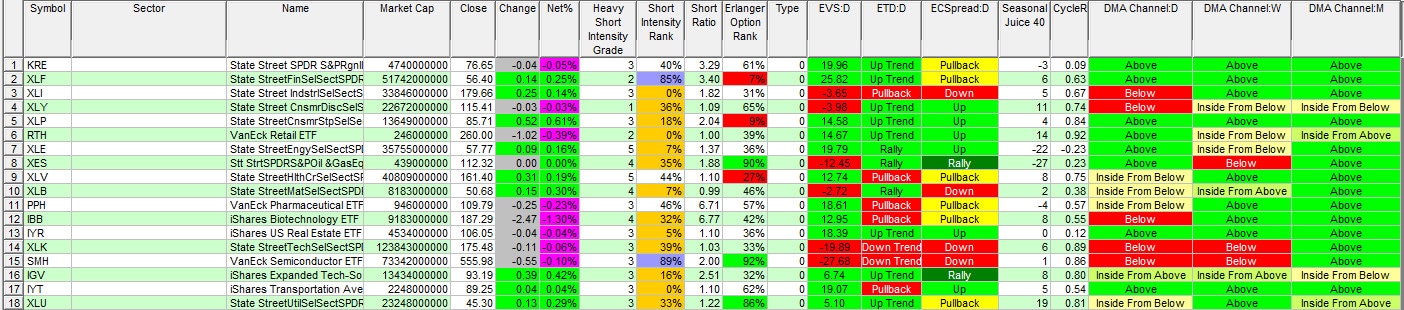
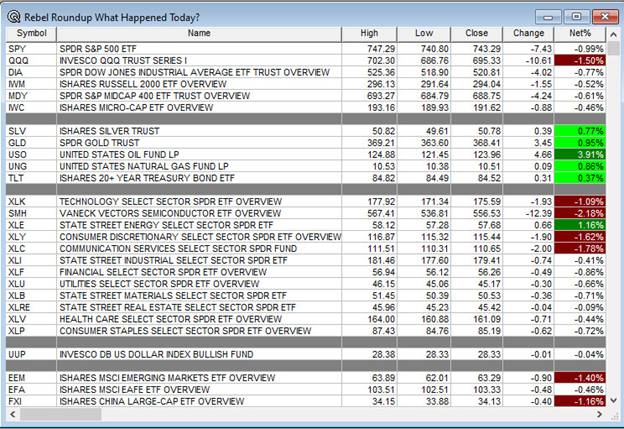
HEATMAP, SECTORS, BREADTH:
TRACKING TODAY’S ACTION
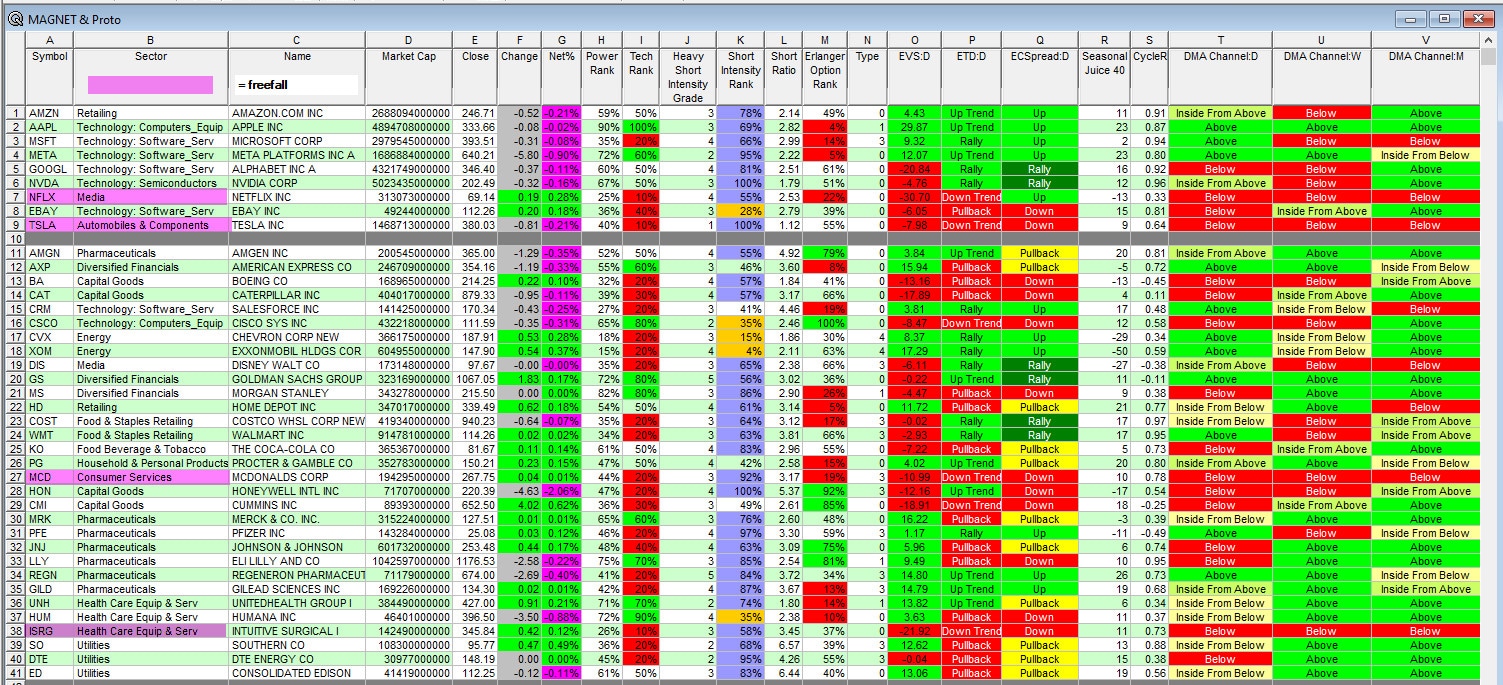
TOP DOGS
BREADTH
UOA AND TOA:
NFLX — Bullish Call Buying, 9:41 AM
5,000 July 31 $70 calls bought for $0.74-0.88, stock $65.56-66.72 — right into the panic low.
Something to consider: A buyer stepping directly into the crash, not chasing a bounce, risking
a small defined premium for leveraged upside above $70. The dealer on the other side picked
up short-dated gamma in a name already proving capable of double-digit swings. Confirm:
NFLX holds its low with declining down-day volume. Invalidate: a break of today’s low on
expanding volume.
META — Bullish Call Spread, 12:51 PM
7,000 July 31 $725 calls bought ($10.42-10.53), 7,000 $775 calls sold ($4.57-4.46), rolling an
existing position, stock $644.96. Something to consider: This traded while the Meta-Anthropic
compute headlines were actively lifting the stock off its lows. The defined-risk structure reflects
conviction tempered by expensive short-dated volatility — a bet that META gets re-rated as a
compute lessor, capped in exchange for lower cost. If the Anthropic deal formalizes, this spread
moves in the money fast.
ORCL — Bullish Call Buying, 10:54 AM
3,750 August 14 $160 calls bought for $1.27, stock $125.50.
Something to consider: This landed the same morning Michael Burry confirmed he’d closed
his ORCL short — a notable coincidence, unconfirmed as connected. ORCL closed +1.77%, a
standout in a sector being sold indiscriminately. Does one green day really invalidate Burry’s
thesis, or is this just oversold capitulation alongside SOX’s bear-market close?
CVX — Bullish Call Buying, 1:51 PM
10,000 July 24 $200 calls bought for $0.20-0.22, stock $186.67-186.71.
Something to consider: Far out-of-the-money, short-dated calls bought for pennies read as
lottery positioning — but the timing, alongside BP/ConocoPhillips’ new Iraq investment and
crude’s +4.23% day, makes it look more directional than a hedge. Small risk, outsized convexity
if Brent’s push toward $90 continues.
FRO — Bearish Put Spread, 3:09 PM10,000
August 21 $40 puts bought ($4.52), $32 puts sold ($0.62), stock $36.40.
Something to consider: Frontline (FRO) is a major crude tanker operator; this bearish spread
landed the same day as reports of tankers avoiding the U.S. blockade and a confirmed tanker
attack near Oman. A useful counterpoint to the CVX call: the market is distinguishing producers
benefiting from higher prices from shippers whose cargo volumes are being disrupted by the
same conflict.
THE DAI
THE DAILY DASHBOARD: LEADERS AND LOSERS
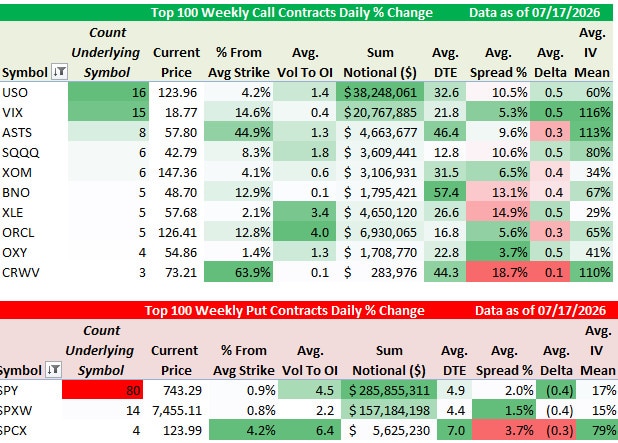
We now track where option players made the most money today on both the Call and Put side. 0DTE are not part of the calculation.
AFTER THE CLOSE
Notable Earnings Out After The Close:
- Beats: None of note.
- Misses: None of note.
- Flat: None of note.
Winners From Last Week:, CDNA (39.73 +39.35%), IOVA (5.00 +18.2%), OEC (6.85 +20.39%), MAN (52.34 +35.21%), RHI (41.80 +29.01%), EAF (6.93 +17.66%), BCO (120.12 +15.23%), CTAS (204.45 +13.81%), RH (187.88 +13.63%), PYPL (56.56 +22.11%), SAIL (15.68 +14.37%), PBF (62.75 +18%), PARR (76.25 +15.92%), NOG (21.19 +14.42%), DK (63.25 +13.94%), GPRE (19.23 +13.85%), CVI (35.13 +13.43%), COTY (2.61 +16.52%).
Losers From Last Week: RGNX (9.89 -29.1%), NTLA (11.38 -19.98%), SLDB (8.72 -16.31%), FLY (19.27 -20.01%), PNR (62.45 -18.03%), IBM (212.67 -26.04%), MXL (71.84 -21.31%), AMBA (61.84 -20%), MRVL (188.68 -19.99%), GLW (154.61 -19.01%), SIMO (264.33 -19.01%), CIEN (374.41 -18.73%), NOK (10.12 -18.65%), BB (8.99 -18.05%), ICHR (82.87 -17.38%), CEVA (37.97 -16.62%), CLS (301.34 -16.26%), ARI (6.98 -33.08%), STI (6.33 -23.09%).
After The Close:
- Trump hosts FIFA Party at Trump Tower ahead of World Cup Final on Sunday.
- 10Q Delays – None of note.
Executive, Corporate Changes:
- SPIR names Eric Mellinger chief commercial officer, effective Aug. 3.
- Paramount Skydance (PSKY) extends note exchange and tender offers to July 31.
- HIMS announces that Chief Accounting Officer, Irene Becklund, will depart the company, effective October 9, 2026.
- XRM makes executive appointments, including a new COO Aaron Roseth and Robert Zeiller has been appointed as Chief Development Officer and Head of Seniors Housing of Chiron Real Estate and Inter-American Management.
- LNN announces that CFO Sam Hinrichsen has notified the Board of his intent to resign, effective August 31, 2026.
- SPRY announces that CMO Sarina Tanimoto, M.D. has ceased employment announces that CMO Sarina Tanimoto, M.D. has ceased employment
Buybacks of Note:
- VALU renews $2 mln stock repurchase program.
Dividend Info:
- ITUB FDX VST DTE FTV BRKR MAIN OTF DX LTC ARCO GIII UTZ go Ex-Div Monday.
- Ex-Div Tuesday.
- SJM raises quarterly dividend to $1.12/share from $1.10/share.
QUESTIONS FROM THE ROWDY REBELS
Q: “So many stocks are getting killed day after day. The only thing saving my account
right now is puts. Why haven’t we seen more put trades in this service?” (Donna R.)
A: Even with breadth flipping negative today, more than half of all stocks remain above both
moving averages, and the S&P’s primary trend stays bullish above 7,515. Single-stock puts
work great in a name-specific unwind like chips — but layering that posture across an entire
book fights the broader trend. Better use: tactical, name-specific hedges (like the FRO put
spread above) against what’s genuinely breaking down, while staying long what isn’t.
Q: “I’m holding NFLX LEAPS calls at a 50% loss after the post-earnings drop. Hold or cut
losses?” (Jackie H.)
A: The answer isn’t “hold” or “cut” — it’s “manage.” NFLX got crushed on guidance and
disclosure, not fundamentals — a governance problem, not a business-quality one. With that
much time value left, selling short-dated calls against the position to reduce cost basis is more
defined than an all-or-nothing call. Watch how it holds the 5-minute and 1-hour ranges before
deciding.
Q: “How do you pick which strikes to use when constructing a spread — open interest,
or historical price levels?” (Vinnie C.)
A: Both, in order. Liquidity determines whether a strike is tradeable at a fair price at all; historical
levels then inform where the breakeven and max-profit zones should sit. Today’s GLD 368/376
spread is a clean example — real open interest on both legs, built around a double-bottom on
the chart. More on this in the Weekly Webinar on Tuesday.
Q: “I’ve got a short-term SPY call to hedge a longer-dated SPY put. Does your confidence
on that kind of hedge change day to day?” (Stephen N.)
A: It should — conviction on any tactical hedge decays if it hasn’t worked in a couple of
sessions, even when the underlying thesis is intact. Today’s VIX jump to 18.74 (+12%) and the
breadth flip is exactly the environment where short-term hedges earn their keep. The goal isn’t
to be right on the hedge; it’s to reduce variance while the longer view plays out.
Q: “What’s been driving unusual options flow the last few weeks — anything with real
follow-through?” (Chris S.)
A: A lot of volume, very little stickiness — most high-conviction-looking flow has been
longer-dated (September/Q4), with little short-term follow-through on either side. The exception
is Energy: SHEL, XOM, PBF, and CVX have shown sustained positioning for two-plus weeks,
matching Energy’s status as today’s only green sector and the week’s clear leader. When flow
and tape agree for two straight weeks, that’s the more reliable signal.
WATCHLIST
Theme: The Chip Bear Market
Bull: SOX’s 20%+ drawdown has already re-rated the sector’s most expensive names down to
levels where the underlying AI-infrastructure demand story becomes attractive again.
Roundhill’s Memory ETF just pulled in $10B in fresh capital amid the pullback. If Kimi K3 proves
more narrative than substance, the complex could snap back sharply.
Bear: Semiconductors at ~20% of S&P 500 weight means even a modest, rational re-rating of
capex assumptions has an outsized index-level effect. If Kimi K3 is genuinely competitive and
more enterprises shift toward Chinese models, the capex-domino effect is a multi-quarter
repricing this bear market has barely begun to reflect.
Theme: Strait of Hormuz Risk Premium
Bull: Refiners (VLO, PSX, MPC — all at 52-week highs) and integrateds (CVX, XOM) are the
cleanest way to play continued disruption without direct war exposure — refining margins are
shattering records as supply disruptions outpace crude’s own move.
Bear: If the reported “massive offensive” doesn’t materialize and de-escalation wins out, oil’s
20%-in-15-days move unwinds fast — and the names most levered to the risk premium have
the furthest to fall on a surprise.