Newsletters
Rebel Roundup Newsletter Weekend Edition for 7/24-7/26: FOMC Presser, Earnings Continue and Several Economic Releases of Note.
Each weekend we spend a good amount of time preparing for the upcoming week.
This makes commentary better during the week because our team has a better idea of what is happening in the market to analze for you the reader.
So tonight as we complete our exercise from the weekend it makes sense to share what we are expecting going into the week. First, we review what happened after the close that could impact Monday morning. Look for another LEAP idea tomorrow from us as well.
AFTER THE CLOSE
Notable Earnings Out After The Close:
- Beats: None of note.
- Misses: None of note.
- Flat: None of note.
Winners From The Week: THC (234.67 +20.4%), ARWR (85.60 +15.21%), NVCR (18 +13.03%), MEDP (605.07 +12.52%), CLF (11.94 +28.66%), SXT (126.14 +15.67%), EGO (32.00 +14.49%), NG (5.92 +14.29%), LMT (583.81 +14.75%), SBLK (28.26 +13.47%), CMCO (16.18 +12.66%), THRM (42.69 +18.78%), RNG (48.46 +17.28%), OII (52.90 +25.12%), VET (11.26 +14.5%).
Losers From The Week: CDXS -21.1%, KPTI (7.57 -20.4%), RUN (9.93 -16.24%), TSLA (310.99 -18.34%), RPD (9.48 -22.34%), SEDG (42.48 -20.56%), TENB (32.25 -19.13%), STM (51.34 -17.27%), PEGA (26.69 -17.01%), ADTN (9.84 -15.54%), BMI (126.43 -15.42%), LBRT (17.44 -26.85%)
News After The Close:
- Paramount Skydance (PSKY) extends note exchange and tender offers to Aug. 7.
- HF Sinclair (DINO) files suit against EPA over delays in biofuel-blending decision.
- Microchip (MCHP) to acquire edge AI chipmaker Hailo.
- Amazon (AMZN) |ticking lower on report TikTok is testing a rival to Amazon Prime. (Business Insider)
- US to resume cattle imports from Mexico. (WSJ)
- GD awarded a US Air Force contract, with a not-to-exceed value of $400,400,000.
- RTX awarded a $333.6 mln Defense Logistics Agency contract
- 10Q Delays – None of note.
Executive, Corporate Changes:
- CARR announces election of Neil Barua, President and CEO of PTC Inc, to its Board of Directors.
- MCHP COO Richard J. Simoncic, resigns, effective August 17, 2026 to become head of a private company, Menlo Microsystems.
- CACC CTO Ravi Mohan to step down.
Buybacks of Note:
Dividend Info:
- RY BNY WIT BCO USAC WMK LPG goes Ex-Div Monday.
- goes Ex-Div Tuesday.
- RBA increases quarterly cash dividend to $0.33/share from $0.31/share.
COMMENT -Tracking corporate action and filings after the close is tedious work but pays off. Especially filing see below. Normally Rebel Reoundup Pro susbcribers see this is the morning.
FILINGS – Undoubtedly, there will be more in the morning but this gives us a heads up.
- IPO Filings & News: None of note.
- Secondaries Filed Or Priced:
- Notes Filed Or Priced:
- Convertible Offerings Filed or Priced: None of note.
- Private Placement: None of note.
- Direct Offering: None of note.
- Exchangeable Subordinate Voting Shares: None of note.
- Selling Shareholders:
- MH files for 165,160,216 share common stock offering by selling stockholder.
- BBIO files for 24,628,286 share common stock offering by selling shareholders .
- REPL files for 25,103,489 share common stock offering by selling shareholders;
- Mixed Shelf Offerings:
- AMBO files for $100 mln mixed securities shelf offering.
- CEPL files for $500 mln mixed securities shelf offering.
- BAH files mixed securities shelf offering.
THE WEEK AHEAD – The goal of this is to uderstand what is going to move markets each day as well as what names are going to move. This appears in Rebel Squeeze Play Pro each week.
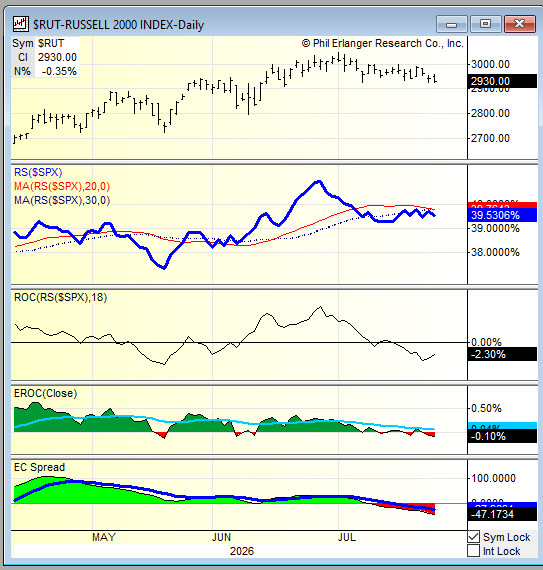
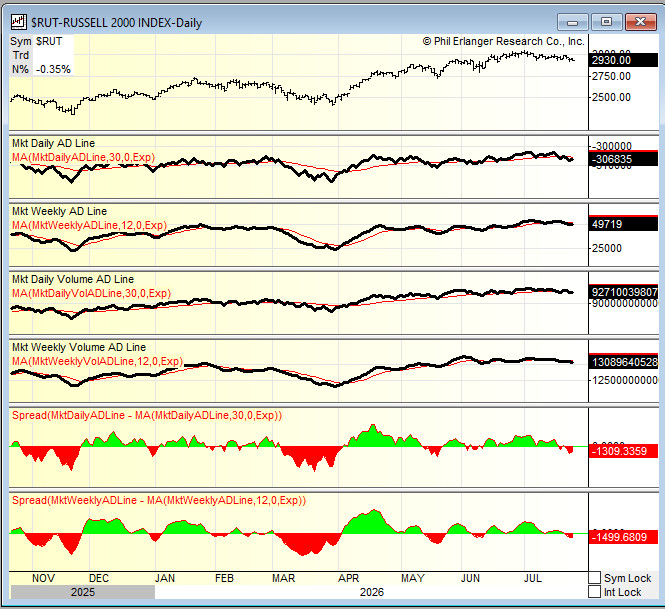
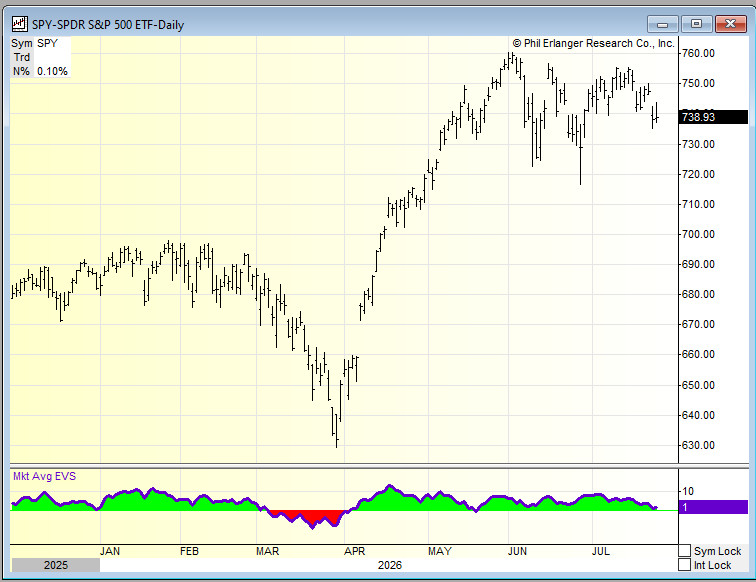
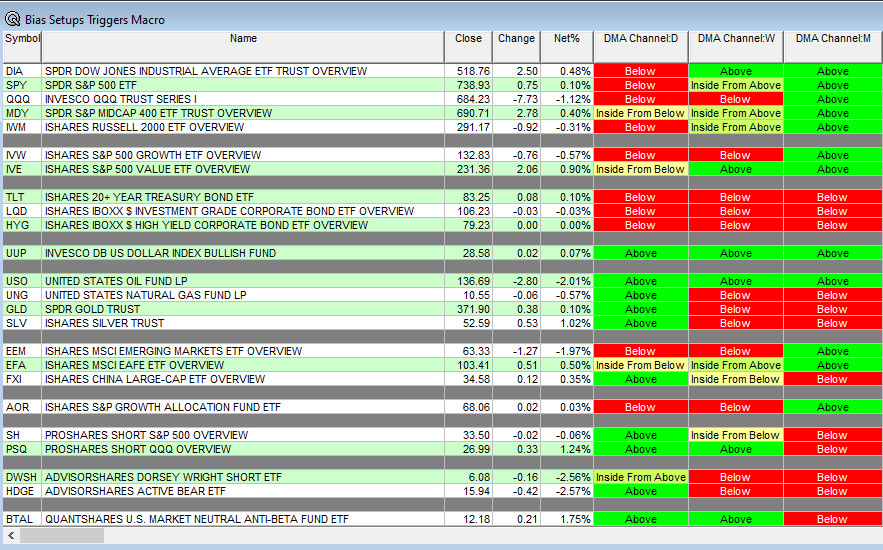
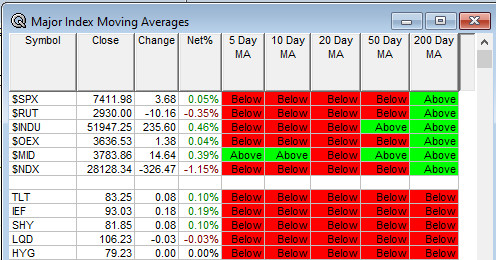
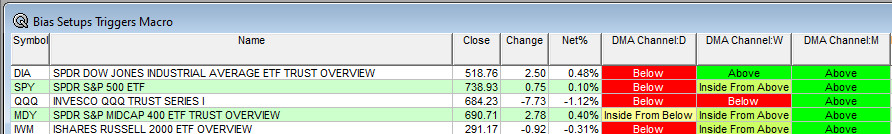
The major stock indexes were lower across the board. The S&P 500 is now in a range of 7500 to 7400 a drop from last week. The S&P 500 closed Friday at 7411.98 from 74571.69 on 7/17. Most equity indexes we track are below their Daily DMA Channels and in their Weeklies while still above the Monthlies. The Dow Jones Industrial Average 14-day Choppiness index is at 54 from 62 last week and the Russell 2000 is at 65 from 57. This week the S&P 500 is now at 60 from 57 while the NASDAQ 100 is at 54 from 53. Last, the S&P 400 is at 64 from 55.
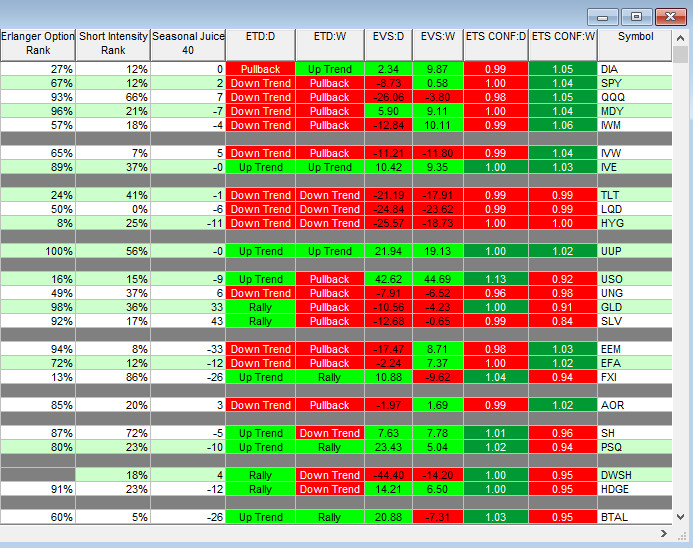
Below is our summary of the Current Moving Average Levels on our index tracking. There is weak action on both the equity and the bond side.
Moving Averages (updated through 7/24 Close)
The top four areas facing the market in this trading week are:
- Geopolitical and Fiscal Events. Watch our X (Twitter) feed Bullet86 for a last minute heads up on Federal Reserve speakers as well as Treasury auctions each day. Fed Speakers are now back in the blackout period until July 30th which is the day after the next FOMC meeting ends on the 29th.
- Economic Releases. Monthly Releases of note this week include Durable Goods, Consumer Confidence, Case-Schiller Home Price Index, FOMC Decision, Personal Income, PCE Core, Chicago PMI and University of Michigan Consumer Confidence.
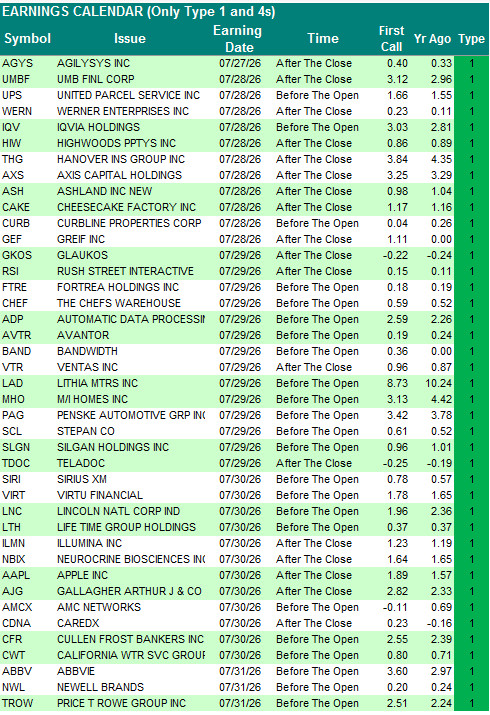
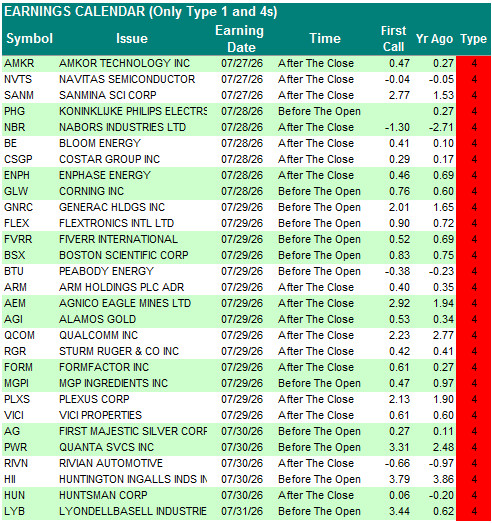
- Earnings Releases. Nothing notable in releases this upcoming week: Earnings season has basically concluded for the first quarter earnings. Second Quarter Earnings will continue this week led by CDNS BKR V KO MSFT META AAPL AMZN XOM CVX.
- Latest Short Interest Release – The NYSE and NASDAQ released their latest short interest data last week for the collection period of June 30th to July 15th. NYSE Short Interest fell by -1.57% and NASDAQ rose by 0.97%. The S&P 500 rose by 2.77% during the last reporting period. The next release date will be August 11th after the close and range from July 15th to July 31st. In that period, the S&P 500 has fallen by -2.12%.
Daily Alerts
- June Durable Goods are out at 8:30 a.m. EDT and are expected to fall to 0.90% from 1.30%.
- May Case Schiller Home Price Index is due out at 9:00 a.m. EDT and expected to rise to 1.3% from 1.1%.
- July Consumer Confidence is due out at 10:00 a.m. EDT and expected to rise to 92.10 from 91.20.
- The latest Federal Reserve Open Market Committee (FOMC) meeting will conclude at 2:00 p.m. EDT with an announcement and then a press conference at 2:30 p.m. EDT.
- June Personal Income is due out at 8:30 a.m. EDT and expected to fall to 0.3% from 0.70%.
- June PCE Core is also due out at 8:30 a.m. EDT and expected to fall to -0.10% from 0.40%.
- July Chicago PMI is due out at 9:45 a.m. EDT and expected to drop to 56.5 from 56.70.
- July University of Michigan Consumer Sentiment is due out at 10:00 a.m. EDT and expected to stay at 54.40.
TAKEAWAY – Fed and Earnings will drive the market along with some economic releases.
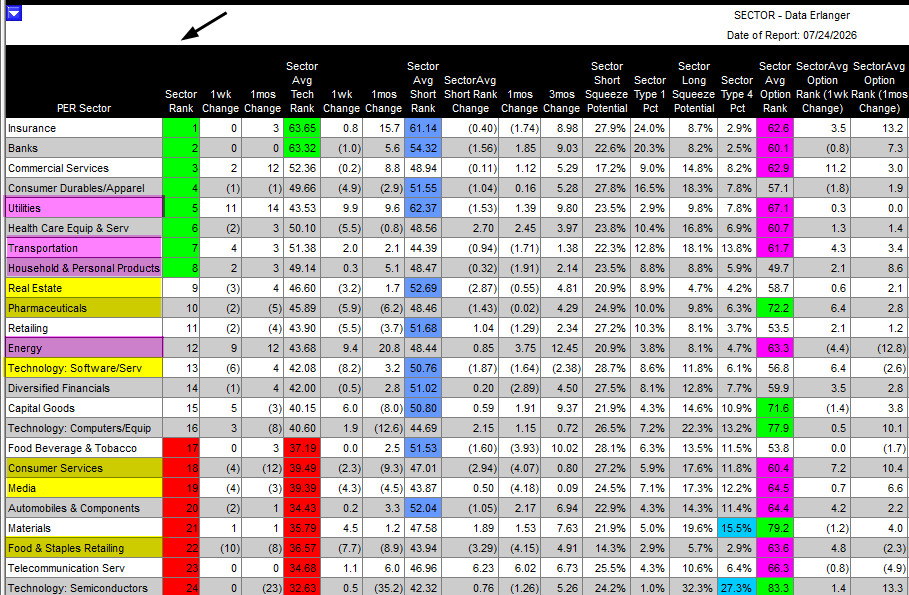
WEEKLY REPORT – The weekly report is divided into Macro and Micro. Each Week we highlight one of them. This is published in Rebel Squeeze Play Pro.