
Rebel`s Edge Notes
Rebel’s Edge Notes
U.S., equity indices are generally lower as investors await the Federal Reserve’s interest rate decision later today, with expectations leaning towards rates remaining unchanged at 3.50% to 3.75%. Tensions have escalated following joint U.S.-Saudi strikes on Iran-backed militia targets, which have contributed to rising oil prices; WTI crude is up by approximately 6.2%.
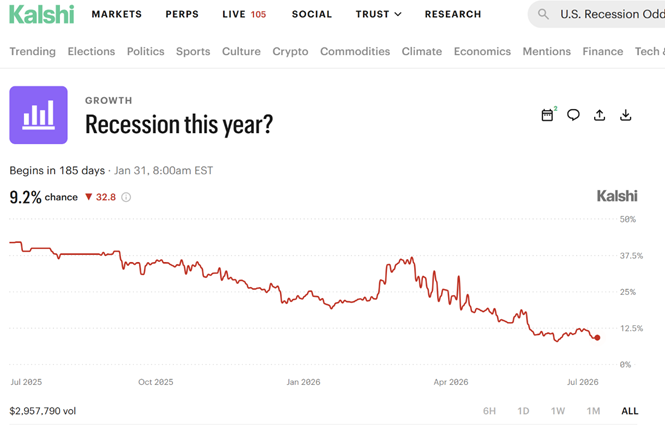
Prediction:
Recession odds drop 32% year over year.
GEHC up 12%: GE HealthCare Technologies is in focus today after reporting second-quarter 2026 results that beat expectations. The company posted adjusted EPS of $1.13, ahead of the roughly $1.04 consensus, with preliminary revenue of about $5.3 billion also coming in slightly above estimates. Management reaffirmed its full-year 2026 adjusted EPS guidance range of $4.80–$5.00 and highlighted continued business momentum, including solid order growth. The results come alongside a leadership change, as CFO Jay Saccaro is stepping down and George Newcomb has been named interim CFO. Despite the transition news, the earnings beat and maintained outlook appear to be supporting the stock
GRMN: Garmin is moving higher today after reporting a strong Q2 2026 earnings beat (adjusted EPS of $2.81 vs. expectations around $2.29) along with better-than-expected revenue and a raised full-year outlook. This was further boosted by its recent acquisition of TrainingPeaks and TrainHeroic that expands its fitness software offerings. The US health and fitness club (gym and studio) market is estimated at approximately $45–48 billion in 2025–2026.
LII: Lennox International is moving lower today after reporting second-quarter 2026 results. Revenue came in around $1.5–1.55 billion (up about 3% year-over-year but below some analyst expectations), while EPS of $7.72 was roughly in line. The Home Comfort Solutions segment was soft (revenue down ~7%), offsetting strength in Building Climate Solutions (up ~24%). Management reaffirmed overall revenue growth expectations but lowered full-year 2026 EPS guidance to $23.00–$24.00, which is weighing on the stock and driving a sharp decline.
VRT: Vertiv is also under pressure despite a solid earnings print. The company reported Q2 adjusted EPS of $1.52 (beating the $1.43 consensus) and revenue of $3.274 billion (up 24% year-over-year), while raising its full-year 2026 outlook to $13.8–14.2 billion in sales and adjusted EPS of $6.65–$6.75. Strong cash flow and ongoing AI/data-center demand were positives. However, revenue missed higher street expectations (partly due to supply-chain and project timing issues), triggering a classic “sell-the-news” reaction after Vertiv’s massive prior run-up on AI infrastructure optimism. The stock has seen a double-digit percentage drop in today’s session.