
Rebel`s Edge Notes
Rebel’s Edge Notes
In the U.S., core consumer prices rose by 0.2% in July, matching market expectations, while the annual inflation rate slowed to 3.4%, down from June’s rate of 3.5%. Wednesday’s figures could bolster officials at the Federal Reserve who believe the central bank can leave its key rate on hold at about 3.6% while inflation steadily declines on its own as those temporary factors fade. Norway’s $2.3 trillion sovereign wealth fund reported a record half-year profit of more than $184 billion on Wednesday, as a rally in Asian technology stocks helped the fund return 9.4%. The Fund invests revenues from the country’s oil and gas industry. The fund — currently valued at around $2.34 trillion —invests in more than 7,000 companies across over 50 countries and holds stakes in about 1.5% of the world’s publicly listed stocks.
Prediction: New York City Council Speaker Julie Menin announced just today an investigation into the marketing and advertising practices of major prediction market platforms. The probe focuses on potentially false, deceptive, or abusive tactics, with particular concern about marketing directed at young people and those with addictive tendencies. Letters were sent to four platforms—Kalshi, Polymarket, Coinbase, and Gemini Titan—requesting detailed information about their marketing practices that reach New Yorkers. The companies have been given 14 days to respond.
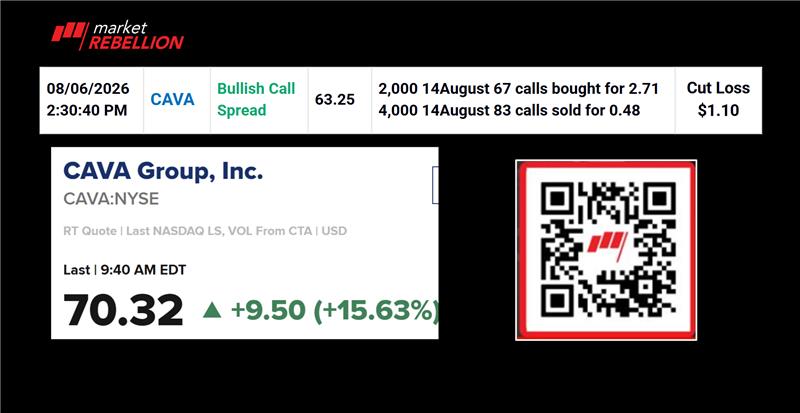
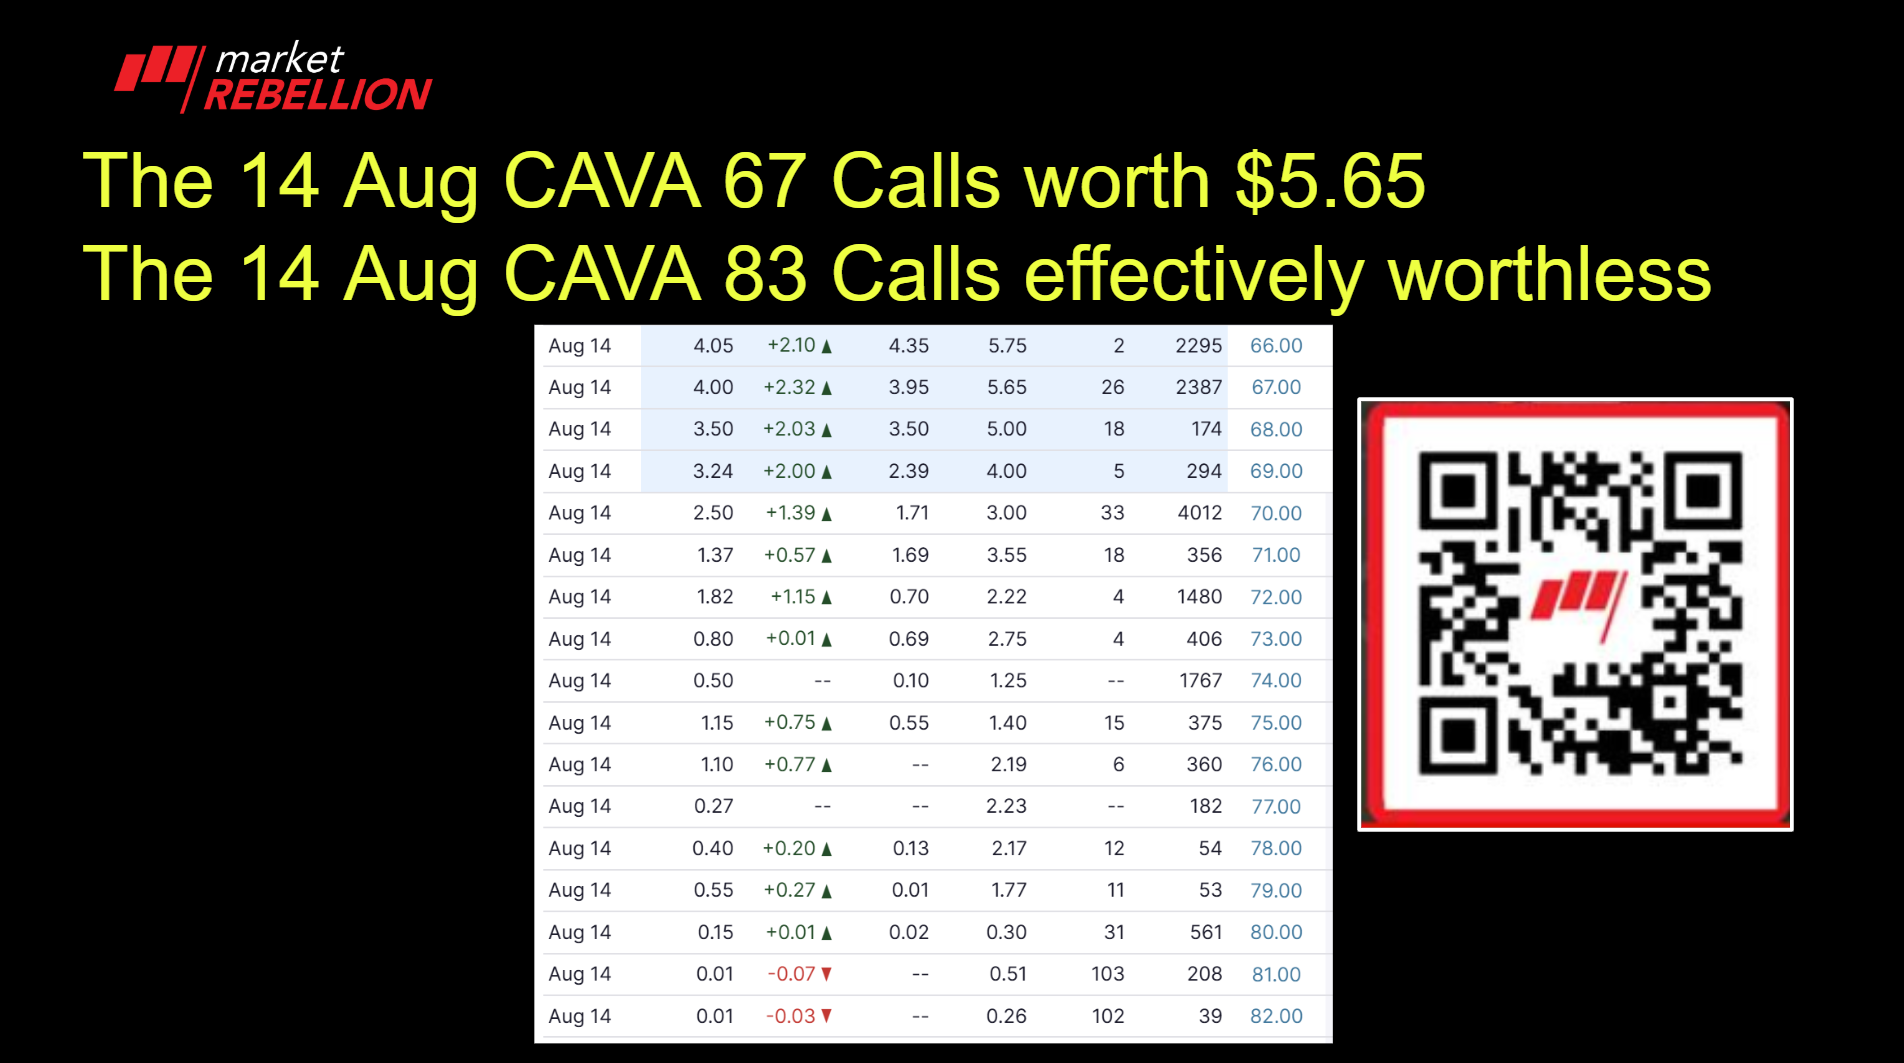
CAVA: CAVA Group is surging today (up roughly 11–12% in pre-market/early trading) after reporting strong Q2 results that beat estimates. Revenue rose 31.3% year-over-year to $365.4 million (vs. ~$360–361 million expected), with same-restaurant sales up 9% and traffic growth of 5.3%. The Mediterranean fast-casual chain opened 17 net new locations and maintained its full-year outlook for 75–77 net new restaurants, 4.5–6.5% same-store sales growth, and adjusted EBITDA of $181–191 million, despite some near-term caution around food-safety concerns in the broader industry. Technically, CAVA has broken above recent resistance near $64–66 and is testing higher levels around $68–70. Near-term support sits around the prior close zone of $60–62 and the 20-day moving average area; a sustained hold above $65–66 would strengthen the bullish setup toward the mid-$70s resistance. The 52-week range remains wide ($43–$99), so momentum is strong but the stock can be volatile.
CRWV: CoreWeave is one of the biggest movers, jumping about 18% after a solid Q2 report and raised guidance. Revenue more than doubled year-over-year (around $2.58 billion), the company posted a narrower-than-expected loss, and it highlighted a massive ~$104 billion backlog along with expanded power capacity and AI cloud demand. The beat and optimistic outlook reversed a pattern of post-earnings weakness and fueled a short-covering rally in this high-growth AI infrastructure name. On the charts, CRWV has broken above the $90–95 resistance zone and is challenging the $105–110 area. Key support now lies near $95–100 (prior resistance turned support) and the rising 20-day moving average; a failure to hold $90–95 could open a retest of the $80–85 zone. Longer-term resistance remains in the $120–150 range from earlier highs. Volatility remains elevated given the stock’s wide 52-week range.
LITE: Lumentum Holdings is up roughly 7–8% on strong fourth-quarter results and an outlook that topped consensus, driven by AI-related demand for optical components and datacom transceivers. The optical equipment maker is benefiting from the broader AI infrastructure buildout, with analysts highlighting positive momentum in cloud and networking end markets. Technically, LITE has cleared near-term resistance and is extending its strong 2026 uptrend. Support is building around the breakout levels near recent highs and the 20-/50-day moving averages; a hold above those would keep the path open toward higher resistance zones. The stock has been one of the year’s bigger percentage gainers in the optical space, so pullbacks to support are common after sharp moves.
SMCI: Fiscal Q4 (ended June 30, 2026) showed mixed but overall positive results that the market largely rewarded: Revenue: $11.12 billion, up ~93% year-over-year (from ~$5.8 billion). This came in slightly below analyst estimates (around $11.2–11.6 billion). Profitability: Adjusted EPS of $1.70 (vs. consensus estimates in the $0.92–1.59 range — a significant beat). Gross margin expanded sharply to ~17.5–17.6% (from 9.9% in the prior quarter and well above the company’s earlier low-single-digit guidance). Net income rose substantially. Guidance (the main catalyst): Q1 FY2027 revenue guided at $14.5–15.5 billion (well above the ~$11.8–12 billion consensus). Adjusted EPS guided at $1.01–1.10 (vs. ~$0.72 consensus). Full-year FY2027 revenue guided at $65–72 billion (far above the prior Street view of roughly $53–57 billion). Orders & backlog: Management highlighted more than $60 billion in new orders during the year and a record backlog heading into FY2027.