
Announcement
Morning Note – 08/07/26: Jobs Friday
Due to travel, today will be limited production. We will be back to normal next week. Overnight Summary and Early Morning Trading: The S&P 500 finished Thursday lower by -0.18% at 7709.96 from Wednesday lower by -0.17% at 7723.55. The S&P 500 sees support now at 7700 from 7600. Resistance is now at 7800 from…
Due to travel, today will be limited production. We will be back to normal next week.
Overnight Summary and Early Morning Trading:
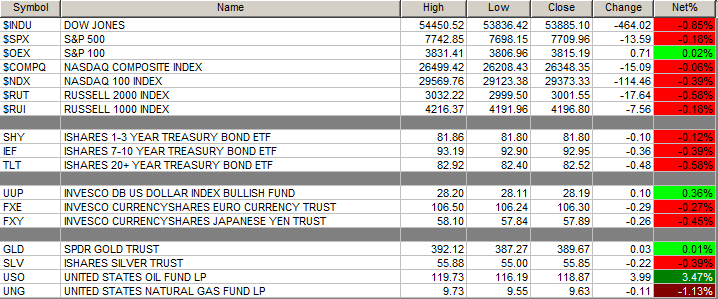
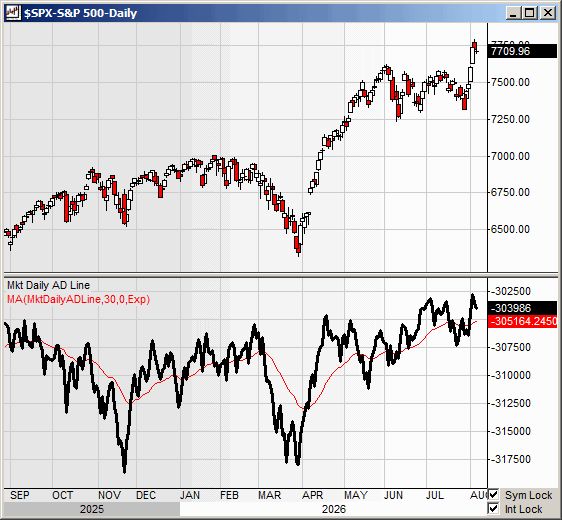
- The S&P 500 finished Thursday lower by -0.18% at 7709.96 from Wednesday lower by -0.17% at 7723.55.
- The S&P 500 sees support now at 7700 from 7600. Resistance is now at 7800 from 7700. In the last four months, support has moved from 6300 to 7700.
- Bond Market is lower today on price with the 10-Year Yield at 4.66% from 4.631%.
Executive Summary:
- Stocks are now in a one-week winning streak, with the S&P 500 rising 1.05% in the last week, ended 7/31. So far this week up 3.30%.
- U.S. moved into Week 24 of its attack on Iran, almost six months. Now we are back to negotiating a deal with Iran.
- We concluded a 4-day win streak on Wednesday and now are in a two day losing streak.
Key Geopolitical Events of Note:
- Economic news of note.
- Weekly – Baker Hughe Rig Count out at 1:00 p.m. EDT.
- Monthly – Monthly Jobs Report and Consumer Credit are due this morning and afternoon.
- President Trump’s schedule:
- Participates in Executive Time at 8:00 a.m. EDT.
- Participates in Policy Meeting at 11:00 a.m. EDT.
- Participates in Policy Meeting at 12:00 a.m. EDT.
- Participates in a roundtable at the State Department on American Mining at 3:00 p.m.
- Speakers of Note: Thomas Barkin Speaks 10:00 AM ET
Capital Raises of Note/Pricings:
- IPO Filings & News: ATTO BRVE OCLT VOGX are coming public this week.
- Secondaries Filed Or Priced: None of note.
- Notes Filed Or Priced: None of note.
- Convertible Offerings Filed or Priced: None of note.
- Private Placement: None of note.
- Direct Offering: None of note.
- Exchangeable Subordinate Voting Shares: None of note.
- Selling Shareholders: None of note.
- Mixed Shelf Offerings: None of note.
Notable Earnings Out After The Close:
- Beats: RGA +2.39, ARW +0.86, IRTC +0.62, AMN +0.58, HALO +0.49, ROKU +0.47, ICUI +0.46, ASTH +0.46, TEAM +0.37, MTW +0.35, BMRN +0.25, GMED +0.24, ONTO +0.24, RHP +0.23, PGNY +0.22, ZD +0.22, ICFI +0.21, YELP +0.21, INOD +0.20, FOXF +0.19, QDEL +0.18, XRAY +0.17, TTD +0.16, CRSR +0.16, NTGR +0.15, TWLO +0.15, PAR +0.14, CENX +0.13, CYTK +0.13, ALRM +0.12, ABNB +0.11, DV +0.11, CON +0.10, TXG +0.10, PK +0.10, SEZL +0.10, NAVI +0.09, AIG +0.08, ESE +0.08, POST +0.08, ARLO +0.08, FIGS +0.08, OFRM +0.07, DKNG +0.07, ED +0.07, MCHP +0.06, RMD +0.06, WPM +0.05, CARG +0.05, PRDO +0.05, LION +0.05, CWST +0.04, G +0.04, RSG +0.04, AAOI +0.04, AVPT +0.04, JHX +0.04, AHR +0.03, FROG +0.03, RLJ +0.03, WSC +0.03, GRDN +0.03, XENE +0.03, AKAM +0.02, XZO +0.02, GEN +0.02, MNST +0.02, NTRA +0.02, SYNA +0.02, TXRH +0.02, NET +0.02, FIVN +0.02, DBX +0.01, KRMN +0.01, TNDM +0.01, REAL +0.01, LASR +0.01 of note.
- Misses: MARA (1.77), CLSK (0.41), AGO (0.28), DNLI (0.17), KGS (0.14), XPOF (0.11), CART (0.09), SG (0.09), APC (0.07), WEST (0.07), AMRZ (0.07), CLNE (0.06), RCAT (0.06), ZYME (0.05), NOG (0.04), BTG (0.04), SARO (0.03), CPK (0.02), NRDS (0.02), AFL (0.01), DOCS (0.01), LYFT (0.01) of note.
- Flat: ARDX +0.00, INDI +0.00, MP +0.00, RGTI +0.00, RKT +0.00, SVV +0.00 of note.
Winners From After The Close: NOT UPDATED of note.
Losers From After The Close: NOT UPDATED of note.
News after the close:
- Mixed Post-Earnings Moves: Warner Bros. Discovery advanced following better-than-expected quarterly results, while AppLovin and Datadog faced heavy selling pressure after issuing softer-than-expected revenue guidance.
- SpaceX Expiration: Shares of SpaceX rose over 6% as 911 million shares became eligible for sale following the expiration of its insider lockup period.
- Eli Lilly ($LLY): Advanced nearly 3% after raising its full-year revenue outlook by $3 billion on soaring demand for its weight-loss and diabetes drugs Zepbound and Mounjaro, while beating Q2 EPS expectations.
- Monster Beverage ($MNST): Dropped over 8% after reporting quarterly revenue that missed consensus estimates, citing slowing consumer spending in non-alcoholic beverages and weaker convenience store foot traffic.
- Gilead Sciences ($GILD): Rose over 3% after-hours following strong Q2 results driven by higher sales of its HIV therapy Biktarvy and oncology treatments, leading the company to raise its full-year earnings guidance.
- Fastly ($FSLY): Plunged more than 18% in extended trading after posting lower-than-anticipated Q3 revenue guidance and lowering its full-year forecast due to enterprise customer spending cutbacks.
Executive, Corporate Changes: None of note.
Buybacks of Note:
- SUPX extends and updates repurchase program.
Dividend Info:
- Top Names Trading Ex-Div Today: MET $0.5925, BANR $0.52, FIBK $0.47, SRCE $0.45, SPH $0.325, LVS $0.30, ORRF $0.30, IBCP $0.28, AROC $0.23, CIVB $0.18, AMAL $0.17, FCCO $0.17, CCEC $0.15, BY $0.12
- Top Names Trading Ex-Div Monday: IDA $0.88, ATR $0.48, BPRN $0.35, SYF $0.34, AWI $0.339, SAR $0.25, HFWA $0.25, FUL $0.24, UVSP $0.23, CAG $0.17, EQT $0.165, MTG $0.15, CBAN $0.12, JMSB $0.10
What Happening This Morning:
Futures S&P 500 +18, NASDAQ 100 +172, Dow Jones +55. Europe is higher while Asia is lower. Bond yield is at 4.66% from 4.631% on the 10-Year. Crude Oil and Brent Crude are lower with Natural Gas higher. Gold and Silver are higher with Copper lower. The U.S. Dollar is lower versus the Euro, higher against the Pound and lower against the Yen. Bitcoin is at $65,138 from $64,562.
Sector Action:
- Daily Materials, Technology, Industrials, Consumer Cyclical, Healthcare and Financials led the way higher
- Daily: Energy was lower.
- One-Month Winners: Technology, Communication Services, Healthcare and Real Estate of note.
- Three-Month Winners: Energy, Materials, Utilities, Consumer Defensive and Industrials of note.
- Six-Month Winners: Energy, Materials, Utilities, Industrials, Healthcare and Consumer Defensive of note.
- Twelve-Month Winners: Materials, Energy, Industrials, Utilities, Communication Services and Technology of note.
- Year-to-Date Winners: Energy, B, Consumer Defensive, Utilities and Industrials of note.
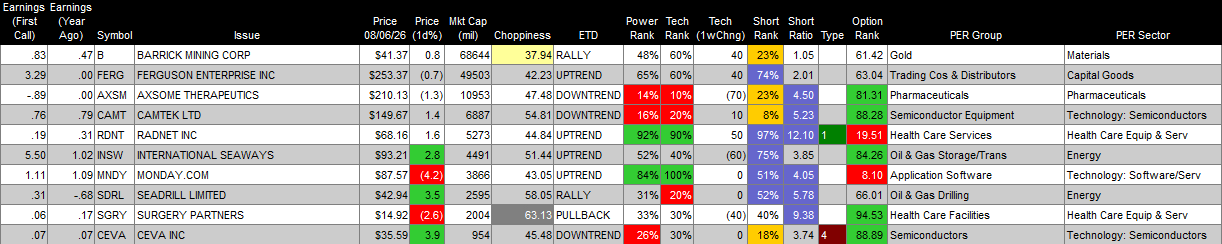
Upcoming Earnings Of Note: (Erlanger Chartroom Software – sorted by market cap, highest to lowest with most visible names)
- Friday After the Close: None of note.
- Monday Before The Open:
Notable Earnings of Note This Morning:
- Beat: TDS +2.15, SPB +1.33, ESNT +0.32, GTN +0.31, EMBC +0.29, TILE +0.24, FLR +0.21, BZH +0.20, ACMR +0.19, EMA +0.19, KRP +0.17, ANIP +0.17, ROAD +0.07, ATMU +0.04, UAA +0.03, PAA +0.03, TTWO +0.02, WEN +0.02, AQN +0.01, SLVM +0.01 of note.
of note. - Missed: CLMT (1.16), AMR (0.53), MBGL (0.28), OKLO (0.12), AD (0.12), PPL (0.01) of note.
- Flat: None of note.
- Still to Report: None of note.
Company Earnings Guidance:
- Positive Guidance: After The Close & This Morning: SOUN Raised FY26 revenue guidance to $150M–$170M (vs. prior $140M–$160M), TTD Issued above-consensus Q3 revenue guidance of at least $618M, EXPE Raised full-year booking and margin outlook on international demand growth, GILD Raised full-year EPS guidance following strong Biktarvy and oncology sales, LLY Raised full-year revenue guidance by $3B to $45B–$46B on robust Zepbound/Mounjaro demand.
- Mixed – None of none.
- Negative or Mixed Guidance: After The Close & This Morning FIVN Lowered FY26 revenue guidance and cut Q3 revenue outlook due to elongated sales cycles, DKNG Lowered full-year EBITDA guidance to $460M–$540M on elevated customer acquisition costs, FSLY Cut full-year revenue outlook and issued soft Q3 guidance on enterprise budget cuts, MNST Lowered second-half sales growth targets amid slowing convenience store foot traffic, PFSI Reduced full-year earnings guidance following mortgage originations shortfall.
Advance/Decline Daily Update:
Gap Ups & Down In Early Pre-Market: (Top 10 up and down):
- Gap Up: SOUN +12.00%, TTD +8.50%, ON +7.03%, EXPE +6.00%, MPC +5.86%, ACA +5.58%, EXR +5.05%, EQR +4.75%, ADM +4.66%, HPE +4.64% of note
- Gap Down: SHAZ -25.86%, FIVN -14.00%, URI -5.70%, MRSH -5.48%, DKNG -5.50%, PLD -3.69%, WAT -3.66%, PNW -2.74%, NKE -2.70%, LVS -2.45% of note.
Insider Action: None sees Insider Buying with dumb short selling. None see Insider Buying with smart short sellers. Above $100,000 in purchases with high shorts but no history: None of note.
Other Trading Action: None of note.
Rags & Mags: Repeated stories from prior days never listed, i.e. “rehashed news”. Sorted by Global, U.S. and stock specific. Bolded source means paywall.
- Atlassian (TEAM) up 29% beat on revenues and earnings against estimates.
- Wendy’s (WEN) beat on earnings, revenues and estimates but missed on global sales falling -6%. Withdrew guidance. Down -2%.
- Solar stocks rose as President Trump imposed tariffs on product to make solar panels.
- Airbnb (ABNB) jumped 7% on earnings and revenue beat.
- SoundHound AI ($SOUN): Surging +12% pre-market after posting Q2 revenue of $24.7M (up 54% YoY), beating consensus estimates and raising its full-year 2026 revenue guidance to $150M–$170M on strong enterprise adoption.
- Trade Desk ($TTD): Up +8.5% after beating Q2 top- and bottom-line estimates, reporting 26% revenue growth, and issuing higher-than-expected Q3 revenue guidance of at least $618M.
- Expedia Group ($EXPE): Gaining +6% pre-market following a Q2 earnings beat ($3.51 EPS vs. $3.18 est.), driven by a 10% increase in total gross bookings and strength in international travel markets.
- Five9 ($FIVN): Dropping -14% after delivering a weaker-than-expected Q3 outlook and cutting full-year revenue guidance, citing elongated sales cycles and tighter enterprise software budgets.
- DraftKings ($DKNG): Falling -5.5% despite beating Q2 expectations, as management lowered its full-year 2026 EBITDA guidance due to high customer acquisition costs and unfavorable sports outcomes early in the third quarter.
Economic & Geopolitical:
- Federal Reserve Speakers of note today:
- Thomas Barkin Speaks 10:00 AM ET
- President Trump’s schedule for today:
- Participates in Executive Time at 8:00 a.m. EDT.
- Participates in Policy Meeting at 11:00 a.m. EDT.
- Participates in Policy Meeting at 12:00 a.m. EDT.
- Participates in a roundtable at the State Department on American Mining at 3:00 p.m.
- Economic Data Out –
- Monthly
- July Monthly Jobs Data due out at 8:30 a.m. EDT and estimates are for a beat with 86,000 versus 57,000 in June.
- June Consumer Credit due out at 3:00 p.m. EDT and expected to rise by $7.5 billion from a drop of $0.2 billion in May,
- Weekly
- Baker Hughes Rig Count are due out at 1:00 p.m. EDT.
- None of note.
- Baker Hughes Rig Count are due out at 1:00 p.m. EDT.
- Monthly
M&A Activity & Daily: None of note.
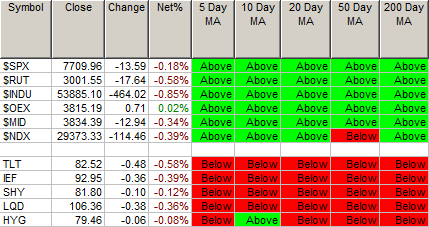
Moving Average Table: 97% from 100% of Equities are Positive, and 4% from 0% Bonds are Positive.
Meeting & Conferences of Note:
- Sellside Conferences:
- DB Data center Conference
- Opp. Biotech Conference
- Top Analyst, Investor:
- Shareholder Meetings:
- Fireside Chat: None of note.
- FDA Presentation: None of note.
- R&D Day: None of note.
- Meetings: None of note.
Upgrades & Downgrades:
The recommendations listed below in this “Upgrade/Downgrade” section are compiled from what we believe are Tier I, II and III firms. Recommendations posted are taken from a variety of sources each day and we only post upgrades or significant initiations as well as downgrades to underweight or sell. The purpose of this posting is to make the reader aware of market-moving recommendations.
Upgrades: None of note.
Downgrades: None of note.
Initiations: Buys: None of note. Sells: None of note.